
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
Real estate wealth isn't built on waiting for bank bureaucracy. When you need a cash out refi for investment property Florida lenders often stall your momentum with two months of paperwork and invasive tax audits. Trapped paper equity does nothing for your bottom line when time-sensitive acquisitions demand immediate liquidity.
You already know the frustration of institutional underwriters treating seasoned investors like credit risks, penalizing legitimate tax write-offs and walking away from properties that need repairs. That delay costs real money. Discover how Florida real estate investors tap trapped equity in days without traditional bank red tape, turning dormant equity into working capital for their next project.
Ahead, we break down how nimble, asset-based private financing works across the Sunshine State, outlining the exact steps to unlock rapid capital based on real property value rather than rigid credit scores.
Key Takeaways
- Understand how a tactical cash out refi for investment property Florida investors rely on converts stagnant paper equity into liquid capital for rapid acquisitions.
- Discover why asset-based private lenders prioritize protective property equity and viable exit strategies over rigid tax returns or strict debt-to-income limits.
- Learn how active portfolio builders use private liquidity bridges to execute the BRRRR method and fund urgent property renovations without conventional waiting periods.
- Identify the straightforward criteria direct lenders use to evaluate Florida asset values and market comparables, even for properties needing substantial repairs.
- Follow a streamlined process to secure preliminary loan approvals within 30 minutes and fund your transaction in 5 to 15 business days.
Understanding Cash Out Refi for Florida Investment Properties
A cash-out refinance replaces an existing mortgage with a brand-new loan secured by your real estate equity, delivering the difference directly to you in cash. For active real estate professionals, this transaction serves as an agile mechanism to reallocate stagnant equity into higher-yielding opportunities, capital expenditures, or portfolio restructuring. Rather than letting equity sit dormant on balance sheets, a tactical Cash Out Refinance taps into built-up property appreciation across Florida markets without requiring an outright property sale.
Unlike institutional mortgage originators that scrutinize years of personal W-2s and tax returns, private asset-based lenders look first at the strength of the underlying asset. Collateral value and protective equity take center stage, allowing real estate operators to access fast liquidity through specialized hard money loans designed for investment properties.
To better understand how restructuring property equity can accelerate your portfolio growth, watch this helpful breakdown:
How Real Estate Equity Creates Working Capital
Unlocking illiquid equity transforms paper wealth into dynamic capital ready for immediate deployment into high-upside acquisitions. Loan-to-value represents the ratio of your requested financing against the appraised market value of your property. Maintaining accessible liquidity reserves positions savvy operators to move fast, negotiate aggressive purchase terms, and take down off-market parcels throughout the state before competing offers materialize. Beyond immediate property transactions, aligning equity strategies with professional financial advice helps preserve long-term growth; for support with portfolio structuring and advisory solutions, visit KHT Accounting & Wealth.
Why Florida Real Estate Demands Rapid Liquidity
High-growth metros like Tampa, St. Petersburg, and Orlando consistently reward cash-ready buyers who can execute without financing contingencies. Motivated sellers regularly accept lower purchase prices from investors who guarantee swift funding over conventional buyers trapped in bureaucratic underwriting. Executing a timely cash out refi for investment property Florida holdings also gives landlords the liquid reserves needed to renovate units, elevate rental quality, and optimize cash flow right before high-demand seasonal leasing cycles arrive.
Traditional Mortgages vs. Hard Money Cash-Out Refinancing
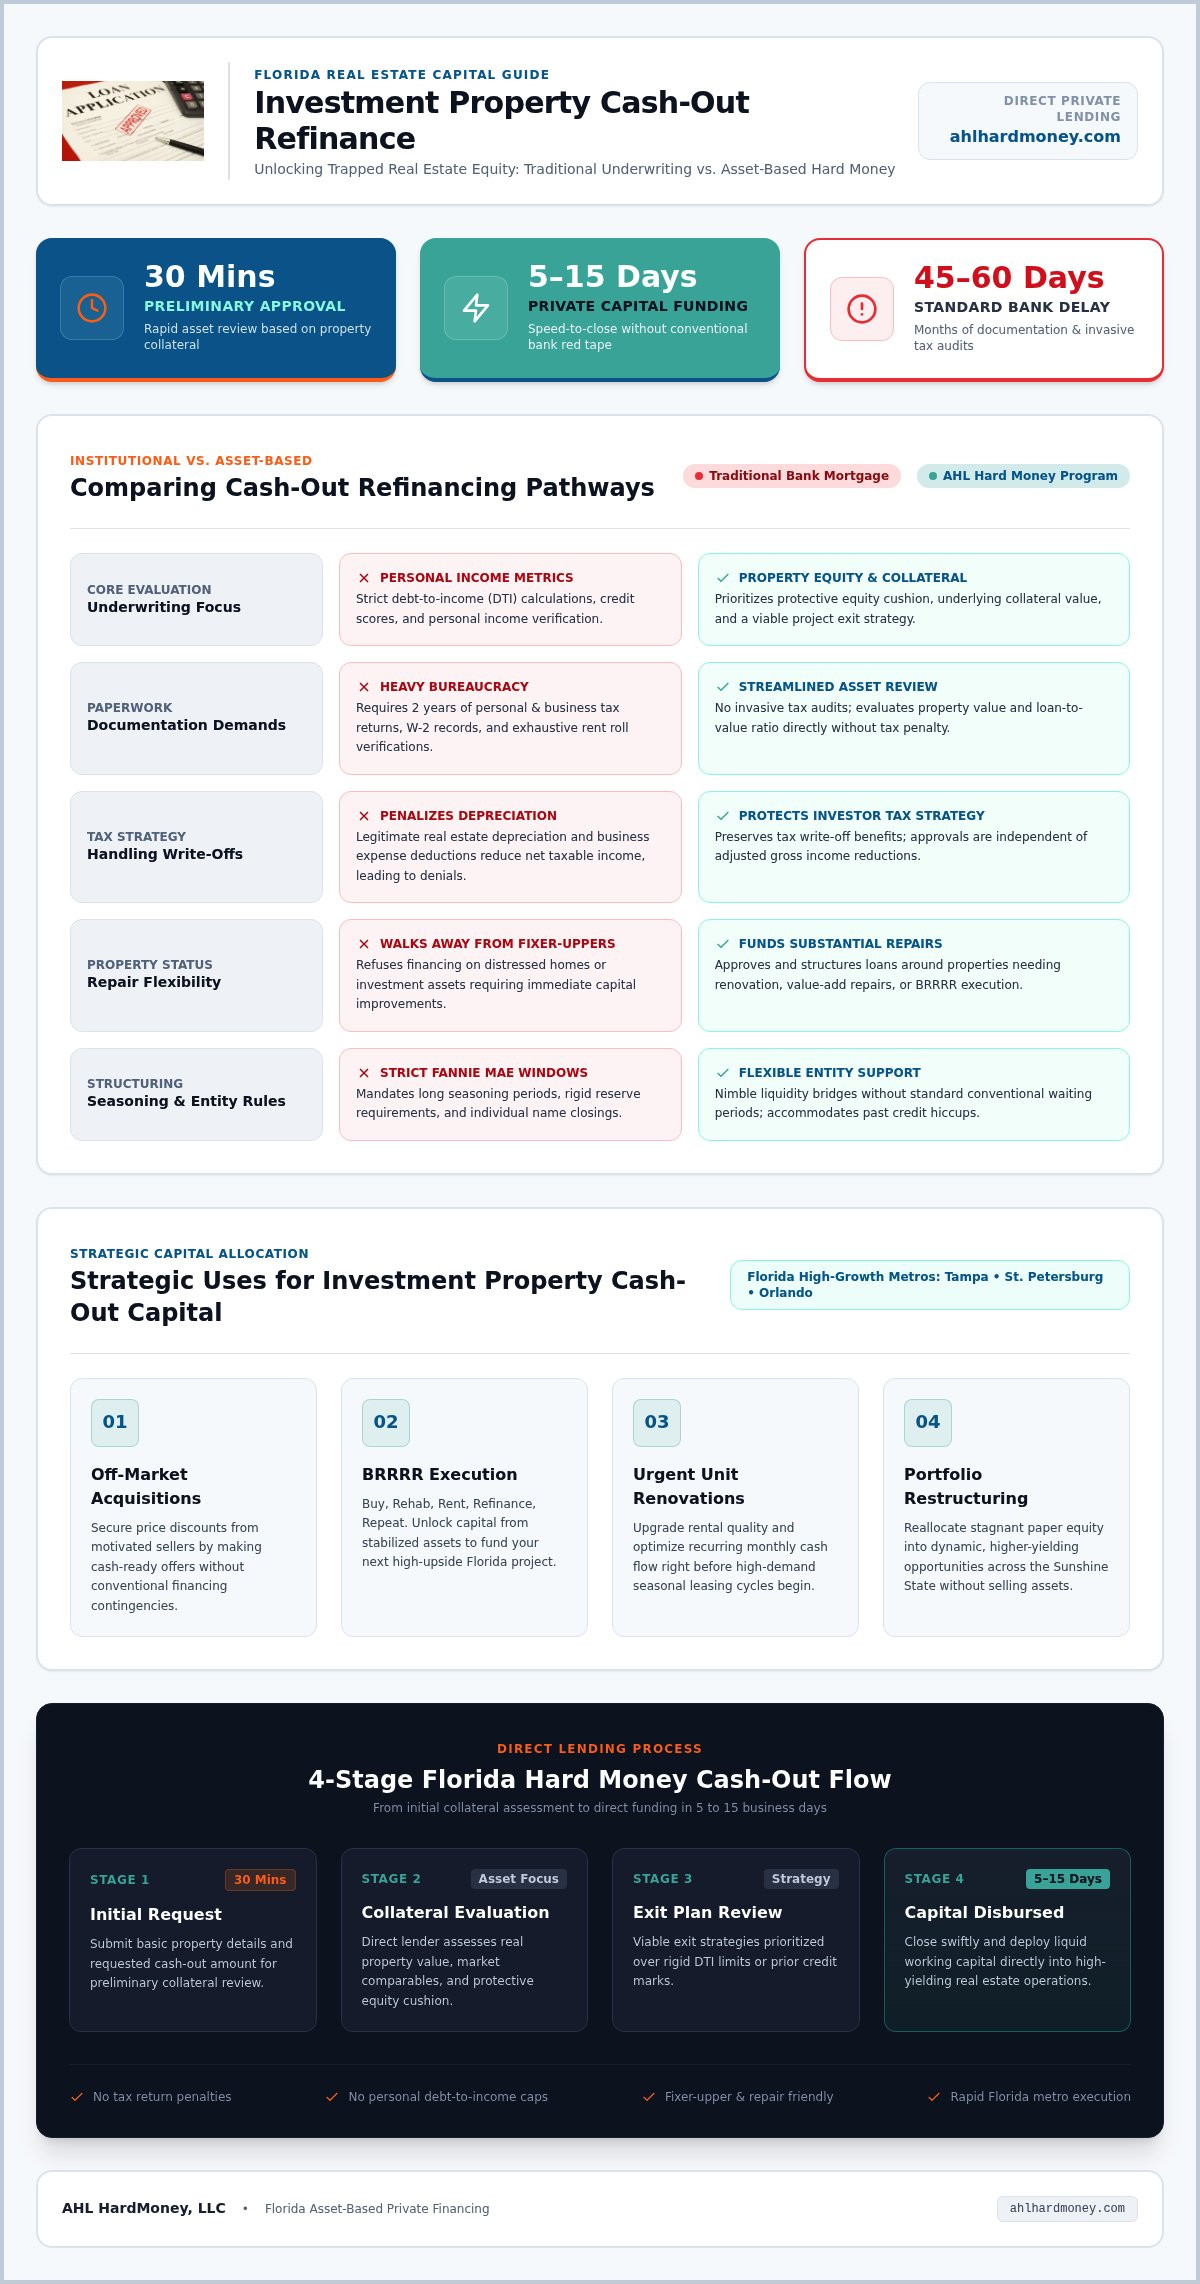
Traditional banks and private lenders approach capital deployment from entirely different worlds. When applying for an institutional cash-out loan, retail underwriters subject your portfolio to rigorous documentation cycles. They demand two years of personal and business tax returns, W-2 records, verification of rent rolls, and stringent debt-to-income calculations. According to standard Fannie Mae cash-out refinance guidelines, conventional lenders also mandate strict property seasoning windows and liquidity reserves, often stretching bank underwriting out for 45 to 60 days before releasing funds.
In contrast, private asset-based lenders focus on equity, collateral strength, and your overall project viability. Rather than disqualifying active investors over technicalities, direct lenders evaluate the property itself and can close transactions in 5 to 15 business days.
Underwriting Criteria: Paperwork vs. Property Value
Self-employed real estate investors routinely write off depreciation, repairs, and business expenses to minimize tax exposure. While this strategy preserves revenue, it slashes net taxable income, leading institutional loan officers to issue sudden denials. Asset-based programs operate differently. When structuring a cash out refinance, private lenders review the protective equity cushion in your real estate rather than your adjusted gross income. Past credit hiccups, foreclosure marks, or lower credit scores don't automatically derail approval when strong asset equity backs the transaction.
- Approval Focus: Banks prioritize personal debt-to-income ratios, while private lenders prioritize asset equity and practical exit strategies.
- Entity Flexibility: Conventional agency programs generally require closing in your individual name; private capital finances LLCs, corporate structures, and partnerships directly.
- Property Condition: Retail banks reject homes with deferred maintenance, whereas asset-based financing readily supports distressed assets earmarked for repositioning.
Speed of Execution When Opportunity Knocks
Florida's competitive real estate climate doesn't wait for committee reviews. Taking 60 days to process a cash out refi for investment property Florida acquisitions can easily cost you a high-margin off-market deal. Motivated sellers walk away when financing contingencies drag on. Direct private lenders evaluate deals quickly, frequently issuing preliminary terms within 30 minutes. Partnering with a dedicated Florida financing specialist gives you the liquidity to execute when profitable opportunities appear. If you want to see how an experienced team can assist your next investment move, take a moment to learn more about our local lending approach.
Strategic Uses for Investment Property Cash-Out Capital
Trapped equity earns zero yield sitting idle inside a property deed. Savvy operators structure a tactical cash out refi for investment property Florida portfolios to reclaim purchase capital, fund property improvements, or fortify their operations against sudden liquidity crunches. Rather than waiting a full year under conventional agency seasoning mandates, private asset-based financing releases substantial capital based on actual post-repair equity, allowing real estate professionals to compound their momentum.
When extracting equity from income properties, tax planning matters. Investors frequently align these transactions with IRS guidelines on rental property mortgage interest, ensuring that proceeds used for business expansion or property capital expenditures are treated accurately on Schedule E or corporate filings.
Scaling Your Florida Rental Portfolio
Recycling initial capital drives the BRRRR (Buy, Rehab, Rent, Refinance, Repeat) strategy. Investors acquiring single-family rentals and small multi-family assets across Hillsborough, Pinellas, and Polk counties tap built-up equity to fund down payments on their next off-market acquisitions. Utilizing flexible private money refinance options creates a dependable liquidity bridge between project completion and permanent stabilization. This approach eliminates the delays caused by institutional seasoning guidelines, letting you scale across active submarkets simultaneously.
Extracted capital serves several key growth strategies across Florida:
- Accelerated Acquisitions: Deploy liquid cash to secure off-market parcels or auction listings before competing buyers finalize financing.
- Value-Add Renovations: Finance major roof replacements, modern HVAC upgrades, or cosmetic modernizations that increase monthly rental rates and asset value.
- Deposit & Earnest Reserves: Keep immediate liquid reserves available to fund large earnest money deposits on multi-family syndications.
Clearing Urgent Financial Bottlenecks
Surprise capital calls can stall an otherwise performing real estate business. Investors frequently extract equity to resolve urgent municipal code violations, satisfy pressing contractor liens, or address state and federal tax obligations before compounding penalties occur. Moving quickly protects clear title status and shields performing assets from forced legal action. If you are dealing with compounding high-interest business debts or short-term liabilities, consider how a debt consolidation hard money loan Florida structure can stabilize balance sheets while keeping your properties producing consistent revenue.
Qualifying for a Florida Investment Property Cash-Out Loan
Institutional underwriters treat mortgage applications like personal forensic investigations. Private asset-based lending operates on a simpler principle. Securing a cash out refi for investment property Florida real estate relies on the tangible value of your collateral rather than your personal W-2 forms. Direct lenders look closely at property condition, neighborhood absorption rates, and recent comparable sales instead of disqualifying you over personal debt ratios.
Ownership flexibility is another major distinction. Conventional loans routinely force investors to hold titles in their individual names, exposing them to personal liabilities. Direct private lenders structure loans directly to LLCs, corporations, and real estate partnerships. Underwriters verify two core fundamentals: sufficient equity in the real estate and a credible exit strategy to settle the balance, whether through refinancing, steady rental income, or an eventual sale.
Determining Usable Equity and Loan-to-Value Limits
Lenders calculate usable equity by analyzing current property values against existing debt. A professional evaluation of recent neighborhood sales establishes the realistic market ceiling. Owning a free and clear Florida property provides the cleanest path to maximum liquidity, as there are no senior mortgages to pay off first. This allows you to convert unencumbered brick and mortar into immediate working capital for your next venture.
Overcoming Credit Imperfections and Title Hurdles
Conventional banks drop applicants the moment a credit score dips or an old derogatory mark surfaces. Private equity programs take a holistic view. Prior bankruptcies, past foreclosures, or low credit scores don't automatically trigger a denial when solid equity protects the loan. As long as title searches show clear ownership and existing liens can be satisfied at closing, direct lenders can structure an approval. This asset-backed approach serves as an essential bridge, allowing you to stabilize the property and build equity while preparing for permanent long-term options.
How to Secure Fast Cash-Out Refinancing with AHL HardMoney
Securing private financing should be direct, responsive, and free of bureaucratic hurdles. When timing dictates your profit margins, navigating a cash out refi for investment property Florida portfolios requires a lender capable of moving at the speed of the market. AHL HardMoney delivers a four-step framework designed to put cash in your hands without the delays of conventional underwriting.
- Step 1: Submit Property Details: Provide basic information regarding your Florida investment real estate, current liens, and your cash-out objectives through our simple online portal or over the phone.
- Step 2: Rapid Initial Review: Speak directly with an asset-based specialist. Preliminary approvals and clear term proposals are often delivered within 30 minutes of review.
- Step 3: Valuation and Title Processing: We order an agile property appraisal or equity valuation alongside local title verification, skipping repetitive tax audits and personal underwriting delays.
- Step 4: Closing and Capital Disbursement: Sign final loan documents at a local Florida title company and receive your wired funds in as few as 5 to 15 business days.
The AHL HardMoney Direct Lending Advantage
Working with an agile, Tampa-headquartered private direct lender means you collaborate directly with regional decision-makers. We know the nuances of Hillsborough, Pinellas, Pasco, Orange, and statewide Florida markets firsthand. Institutional committees sitting hundreds of miles away often fail to understand entrepreneurial strategies, leading to arbitrary loan denials. In addition to commercial bridge options, we structure customized home equity loans and tailored refinancing products designed around your collateral rather than rigid credit guidelines.
Taking Action on Your Next Florida Deal
Speed creates a measurable competitive edge across Florida's active metro areas. Preparing basic property details, your existing mortgage statement, and a clear capital deployment timeline is all it takes to start. While traditional institutions spend months sifting through tax filings and profit-and-loss statements, direct private capital closes your transaction before their first review cycle concludes. Contact AHL HardMoney today to unlock your Florida equity in as few as 5 days and keep your investment pipeline moving forward.
Accelerate Your Florida Portfolio With Agile Asset-Based Capital
Waiting months for traditional bank red tape can stall your investment momentum. Tapping into accrued equity gives you the liquid leverage needed to capture high-margin deals, fund major rehabs, and resolve unexpected property bottlenecks. Choosing a direct cash out refi for investment property Florida holdings lets you focus on real asset value and clear exit strategies rather than personal tax write-offs or restrictive corporate ratios.
AHL HardMoney serves as your agile local financing partner. Headquartered in Tampa with statewide lending coverage, our team delivers preliminary loan approvals within 30 minutes and completes closings in 5 to 15 business days. You don't have to let lucrative opportunities slip away while waiting on slow institutional loan committees.
Your real estate equity should work as hard as you do. Step forward with confidence, take command of your balance sheet, and build lasting portfolio wealth across the Sunshine State.
Frequently Asked Questions
Can I get a cash out refi on an investment property in Florida with bad credit?
Yes, you can secure a cash out refi for investment property Florida holdings regardless of your credit score. Private lenders evaluate the protective equity cushion in your real estate rather than your personal FICO history. Derogatory marks like prior bankruptcies, collections, or past foreclosures don't prevent approval as long as the property holds sufficient market value. This allows active Florida investors to access capital based on real equity.
How quickly can a private lender close an investment property cash-out refinance in Florida?
A direct private lender can complete closings in as few as 5 to 15 business days. Preliminary decisions and term proposals often arrive within 30 minutes of submitting your property details. Because private capital bypasses institutional bureaucracy, property valuations and title reviews proceed quickly without waiting for corporate loan committees. This rapid turnaround helps investors capture time-sensitive deals across Tampa, Clearwater, St. Petersburg, and Orlando.
Do I need to submit tax returns or W-2s for a hard money cash-out loan?
No, private asset-based lenders do not require personal tax returns, W-2 forms, or traditional pay stubs. Self-employed investors often reduce taxable income through legal deductions and depreciation write-offs, which causes conventional bank denials. Private lenders focus on the collateral property itself, checking current market valuation, local comparable sales, and overall equity instead of dissecting your personal debt-to-income ratio.
What types of investment properties qualify for hard money cash-out refinancing in Florida?
Most non-owner-occupied residential and commercial real estate assets qualify for asset-based cash-out programs across Florida. Eligible properties include single-family rental homes, duplexes, multi-family apartment buildings, townhomes, and mixed-use commercial buildings. Even distressed properties needing significant roofing, HVAC, or structural repairs can qualify, because direct lenders evaluate the equity cushion rather than requiring move-in turnkey conditions.
Can I complete a cash-out refinance on a property owned by an LLC?
Yes, direct private lenders routinely close cash-out transactions directly in the name of an LLC, corporation, or partnership. Unlike conventional mortgage agencies that force owners to hold real estate in their personal names, private financing supports business entities. This protects your personal liability while keeping your corporate entity structure completely intact. For real estate entrepreneurs looking to strengthen an entity's profile without risking personal credit, setting up vendor trade credit through The CEO Creative provides net-30 accounts with no personal guarantee. You don't have to transfer deed title back and forth to access your capital.
What can real estate investors use cash-out refinance proceeds for in Florida?
Investors can deploy cash-out proceeds toward any legal business purpose with total flexibility. Common uses include funding down payments on new acquisitions, completing value-add renovations, or executing BRRRR portfolio expansions. Florida operators also structure a cash out refi for investment property Florida assets to pay off pressing municipal code violations, clear tax liens, or eliminate expensive short-term liabilities to stabilize cash flow.
What happens if my Florida investment property currently has no mortgage?
If your property is owned free and clear, you can complete a cash-out refinance with maximum borrowing efficiency. Since there is no existing senior mortgage to pay off at the closing table, the entire net loan balance goes straight to you as liquid cash. This creates immediate working capital for buying additional properties or handling major renovations throughout Florida without navigating traditional bank restrictions.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


