
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
What if the hard-earned equity in your real estate mattered far more to your lender than a temporary credit setback? When you're up against an urgent deadline, like a looming balloon payment or a sudden tax lien, waiting 45 to 60 days for a traditional mortgage isn't just stressful; it can cost you your property. You already know your asset holds strong value, but institutional gatekeepers continue to reject solid deals over automated FICO algorithms. Working directly with a dedicated Florida hardmoney lender changes the entire equation by focusing on the real security of your property rather than past credit challenges.
You deserve a straightforward financing path that moves at the speed of the local market. In this 2026 guide, you'll discover how to secure fast Florida hard money financing using your property's equity to consolidate debt, resolve liens, or safeguard your investments. We explore how direct, asset-based underwriting works, what documentation you actually need, and how partnering with an experienced local lender can turn a pressing financial roadblock into reliable funding within 5 to 15 business days.
Key Takeaways
- Understand how partnering with a direct Florida hardmoney lender allows you to unlock substantial property equity regardless of credit setbacks or automated scoring hurdles.
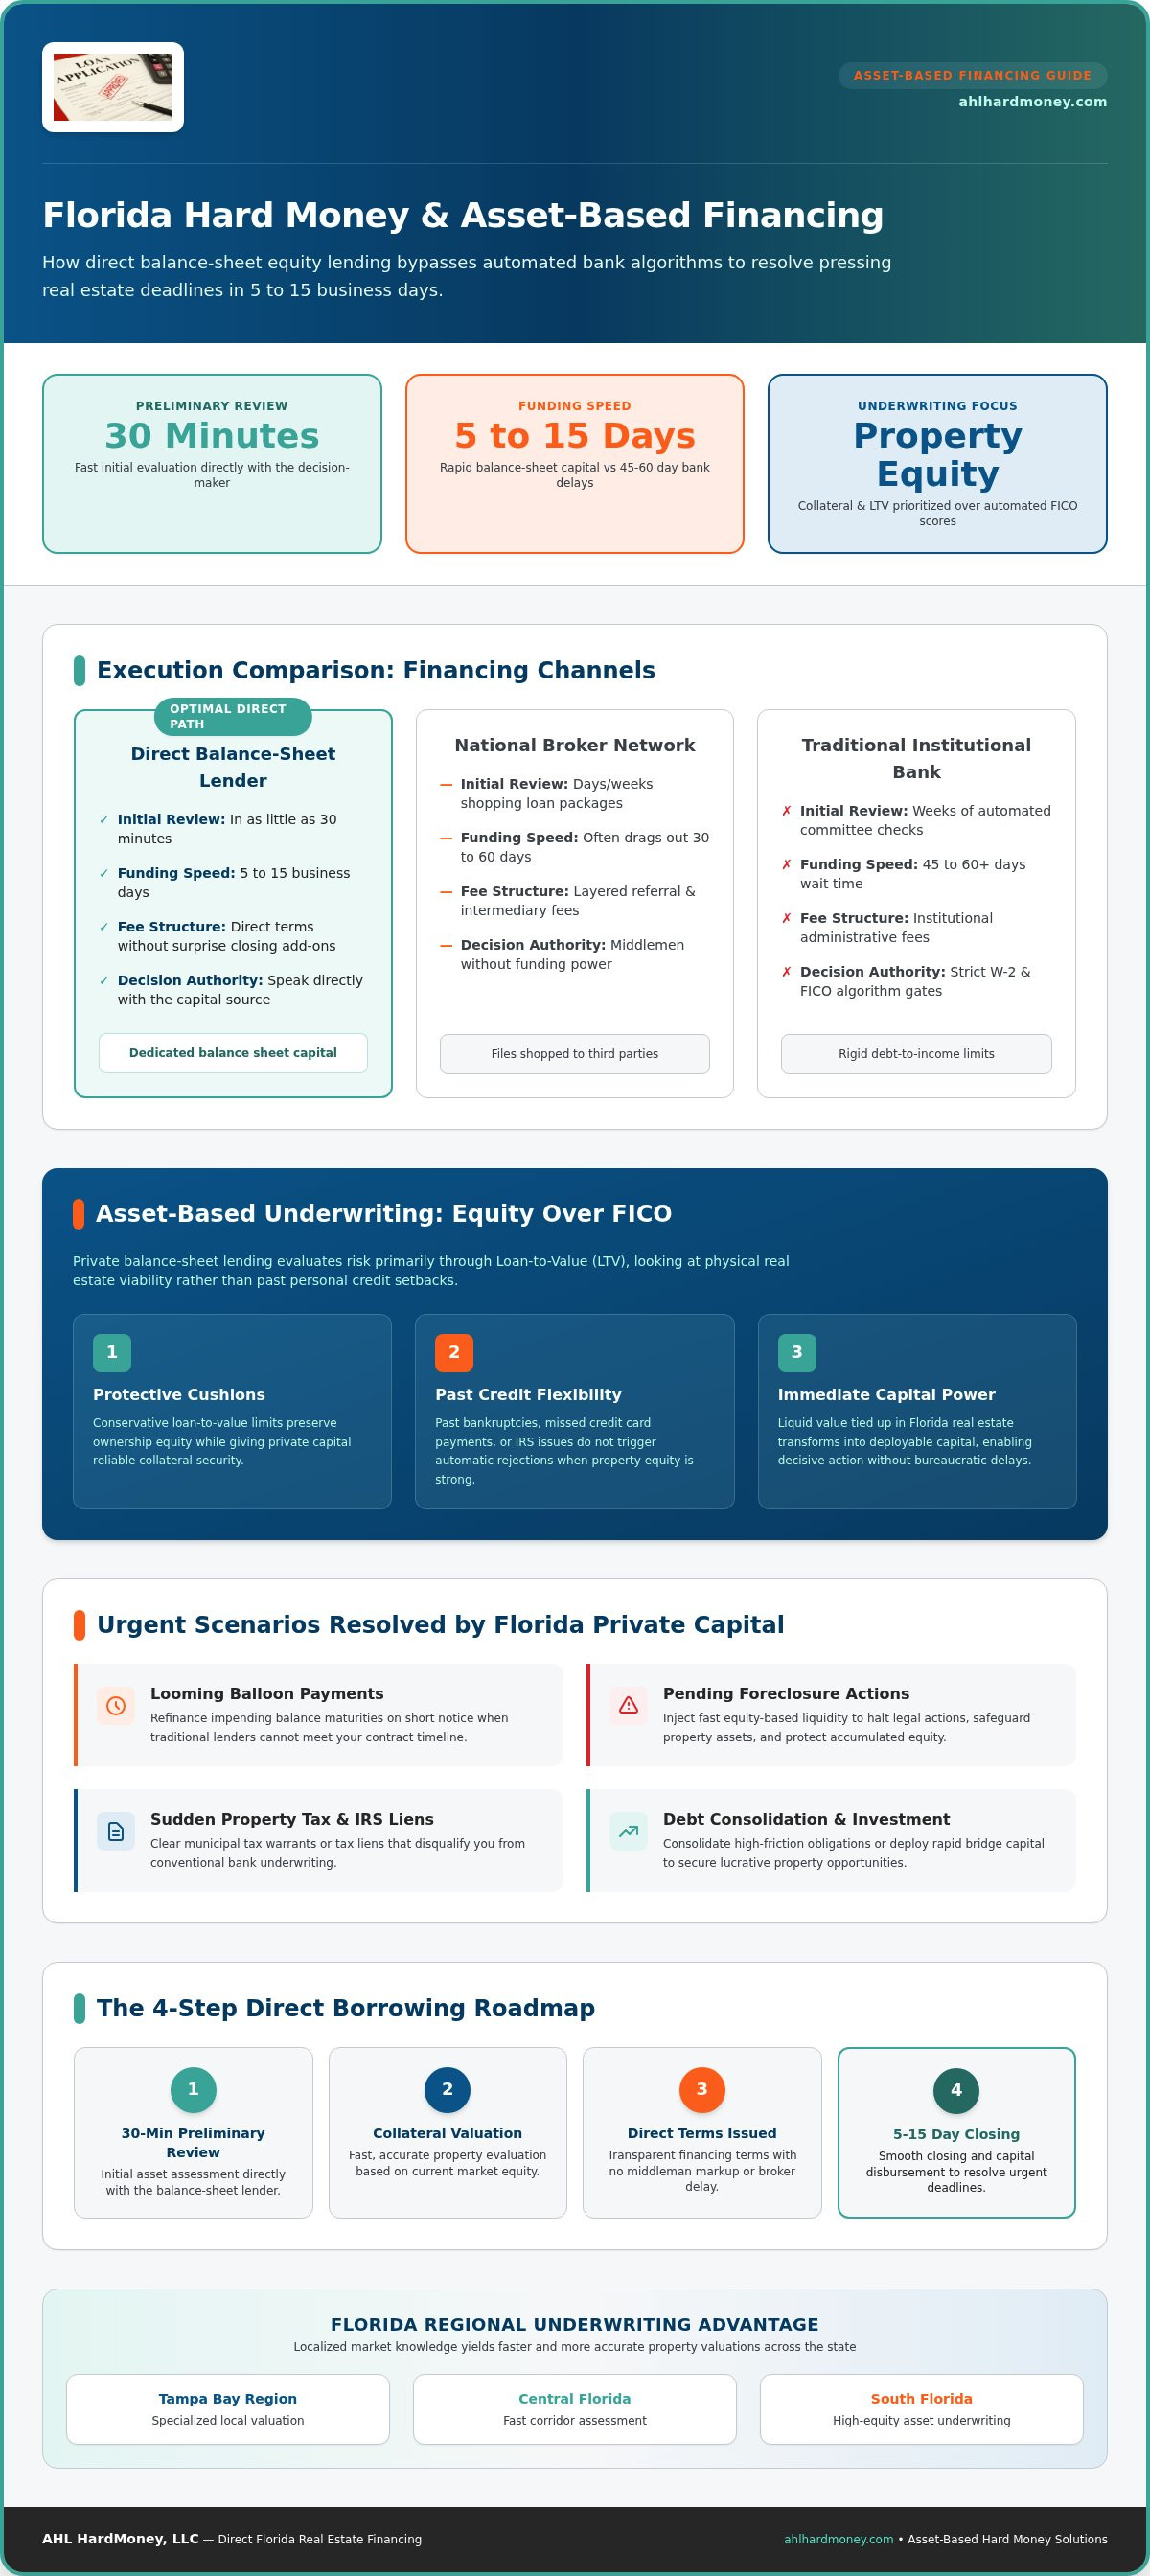
- Discover the key operational differences between direct balance-sheet lenders and national brokers to avoid unnecessary middleman delays and fund within 5 to 15 business days.
- Identify urgent financial scenarios where private capital provides immediate relief, including pending foreclosure actions, balloon payments, and property tax liens.
- Follow a clear, four-step borrowing roadmap designed to take you from a 30-minute preliminary review straight through to a smooth closing.
- Learn why localized underwriting across Tampa Bay, Central Florida, and South Florida yields faster, more accurate property valuations.
What Is a Florida Hard Money Lender and How Does Private Financing Work?
Conventional banks operate like bureaucratic review boards. They evaluate applicants through automated underwriting software, obsessing over W-2 forms, debt-to-income ratios, and strict credit score thresholds. When unexpected life events disrupt those numbers, institutional doors close immediately. A Florida hard money lender operates on a completely different model. A Florida hard money lender issues short-term real estate financing secured directly by property equity rather than personal borrower credit scores. Instead of judging your past, these private asset-based lenders look at the physical real estate and its market viability.
Because private capital comes from dedicated balance sheets rather than government-insured retail deposits, underwriting moves quickly. A typical hard money loan focuses squarely on the collateral value protecting the investment, bypassing weeks of committee reviews. That fundamental difference allows private transactions to close in days rather than months.
To better understand how private capital works across the state, watch this helpful video:
Asset-Based Underwriting: Why Property Equity Outweighs FICO Scores
Equity is your greatest leverage. Private lenders evaluate risk primarily through the loan-to-value ratio, ensuring that the property holds sufficient value to secure the loan balance. This structure protects both parties without requiring flawless personal financial statements.
- Protective Cushions: Conservative loan-to-value limits preserve ownership equity while giving private capital providers reliable security.
- Past Credit Flexibility: Past bankruptcies, missed credit card payments, or sudden IRS issues won't trigger automatic rejections when real estate equity is substantial.
- Immediate Purchasing Power: Liquid value tied up in Florida real estate transforms into deployable capital, enabling you to take decisive action quickly.
Direct Lenders vs. Mortgage Brokers in Florida
Not every private financing source is structured the same way. Working directly with a direct balance-sheet lender gives you straight communication with the actual decision-maker who signs off on your funds. Approvals can happen in as little as 30 minutes, with closings completed in 5 to 15 business days.
Mortgage brokers, by comparison, act as intermediaries. They package your file, shop it around to outside capital sources, and inevitably add extra fees and communication delays. Before handing over sensitive documentation, always confirm whether you're speaking to the direct funding source or an unlicensed middleman.
Evaluating Florida Hard Money Lenders: Key Criteria Beyond Interest Rates
Advertised rates tell only half the story. When an unexpected tax lien, balloon payment, or auction date is closing in, an attractive rate quote means nothing if the lender fails to execute before your deadline. Finding the right Florida hardmoney lender requires evaluating decision-making authority, transparency, and execution speed. Review our hard money lenders Florida guide to benchmark standard market expectations across the Sunshine State.
| Evaluation Factor | Direct Balance-Sheet Lender | National Broker Network |
|---|---|---|
| Underwriting Speed | Initial review in as little as 30 minutes | Days or weeks spent shopping loan packages |
| Funding Timeline | Closes within 5 to 15 business days | Often drags out 30 to 60 days |
| Fee Transparency | Direct terms without surprise closing add-ons | Layered referral fees and middleman markups |
| Market Knowledge | Florida-specific valuation expertise | Out-of-state call centers using detached models |
Approval Speed and Closing Timelines in the Sunshine State
Time is your most valuable asset during a financial crunch. While traditional commercial banks drag borrowers through 60 days of endless paperwork, your equity stays locked up while penalties accumulate. Direct private capital cuts through institutional delay. Because capital resides on the lender's own balance sheet, preliminary loan reviews take as little as 30 minutes, paving the way for closings within 5 to 15 business days.
Loan Flexibility and Customized Payoff Terms
Every real estate challenge has distinct moving parts. A reliable Florida hardmoney lender structures bridge financing around your exact exit strategy, whether you are renovating a distressed property, clearing an IRS lien, or positioning an asset to qualify for long-term conventional refinancing. Flexible loan durations give you breathing room to stabilize your finances on your own schedule. Explore our dedicated background on our about us page to see how direct lending protects your equity.
Common Scenarios Where Florida Hard Money Financing Solves Urgent Needs
Real-world financial challenges rarely conform to traditional lending checklists. Unexpected probate complications, IRS tax encumbrances, or sudden business obligations can paralyze your cash flow. When personal debt ratios disqualify you from conventional bank underwriting, an experienced Florida hardmoney lender looks directly at the real estate collateral. Tapping equity through a Florida cash-out refinance delivers immediate liquidity, while structuring a dedicated debt consolidation hard money loan Florida enables property owners to eliminate high-interest liabilities under one streamlined repayment plan.
The Equity Advantage: Institutional lenders automatically reject borrowers with high debt-to-income ratios or damaged personal credit. Asset-based financing sets those rigid formulas aside. If your Florida real estate holds sufficient protective equity, your loan qualifies based on the security of the property itself.
Halting Foreclosure and Resolving Outstanding Tax Liens
Florida is a judicial foreclosure state where legal filings move swiftly toward court-ordered auctions. Waiting on conventional financing during legal proceedings isn't an option. Securing an emergency Florida foreclosure refinance loan halts foreclosure filings by paying off delinquent balances before auction dates arrive. Private balance-sheet capital can also satisfy municipal tax certificates and federal IRS liens, restoring clear, marketable title to your property.
Unlocking Liquidity from Free and Clear Florida Properties
Substantial real estate wealth often remains trapped in unencumbered assets. Accessing private funds against a free and clear Florida property lets you seize time-sensitive opportunities, such as purchasing discounted inventory or managing emergency operational expenses. Read our cash out refinance hard money Florida guide to evaluate practical timing and repayment structures.
Managing Large Equity Needs with Jumbo Hard Money
High-value residential and commercial properties throughout coastal Florida frequently exceed conventional conforming loan limits. An agile Florida hardmoney lender evaluates unique collateral without arbitrary secondary market caps. Our breakdown of jumbo hard money loans Florida outlines how owners of high-end estates unlock significant capital against substantial property equity when standard lenders say no.
The Florida Hard Money Lending Process: From Application to Fast Closing
Securing private financing doesn't involve navigating a maze of red tape. While institutional underwriting drags on indefinitely, a reliable Florida hardmoney lender relies on a streamlined four-step progression designed to fund urgent transactions efficiently:
- Deal Submission: Submit basic property information, desired loan amounts, and current payoff balances for an initial review completed in as little as 30 minutes.
- Collateral Evaluation: The lender conducts a targeted property valuation based on local comparable sales, bypassing the multi-week appraisal queues typical of depository banks.
- Title and Legal Review: A licensed Florida title company or real estate attorney runs a municipal lien search, confirms payoff figures, and issues a title commitment.
- Closing and Funding: Execute final loan documents in person or via remote online notarization, followed by immediate escrow wire disbursement within 5 to 15 business days.
Streamlined Documentation: What Borrowers Actually Need
Forget providing three years of federal tax returns, endless W-2 schedules, and exhaustive profit-and-loss statements. Asset-based private lenders keep document requests straightforward and practical:
- Government-Issued ID: A valid driver's license or passport confirming borrower identity.
- Property Information: Basic county parcel details, current lease agreements if tenanted, and photos of the real estate.
- Payoff Statements: Current balance verifications for existing mortgages, municipal liens, or tax certificates requiring clearance.
Omitting burdensome personal tax documentation eliminates the standard underwriting roadblocks that frequently derail self-employed business owners and 1099 independent contractors.
Navigating Florida Title Search and Closing Logistics
Smooth execution hinges on thorough title coordination. Licensed Florida title agents examine county land records to identify municipal code enforcement violations, utility assessments, and unrecorded liens before documents reach the table. Because Florida recognizes remote online notarization, borrowers can execute closing paperwork digitally from any location worldwide, ensuring funds wire on schedule without logistical friction.
Choosing Your Florida Lending Partner: Local Knowledge Across Regional Markets
Florida's property landscape is uniquely varied. Coastal micro-markets behave completely differently from suburban developments or expanding inland corridors. When out-of-state institutional lenders attempt to evaluate collateral in Tampa Bay or Central Florida using generic national algorithms, they often panic over local flood zones, insurance shifts, or regional architectural nuances, slashing loan amounts unexpectedly. Choosing a knowledgeable Florida hardmoney lender ensures your real estate is evaluated based on ground-level reality rather than distant guesswork. Read our localized analysis on hard money lenders Pasco County FL to see how suburban county dynamics affect borrowing power.
Why Local Florida Market Experience Matters
Regional awareness makes or breaks an appraisal. A national call center in New York or California rarely understands why a waterfront parcel in Saint Petersburg commands a premium compared to an inland tract just two miles east, or how booming sub-markets across Orlando, Daytona, and Palm Beach sustain high property valuations.
Local experience also streamlines the closing process itself. Handling county recording quirks across Florida's 67 counties demands established working relationships with municipal offices and regional title examiners. When immediate lien payoffs or municipal permit checks are required, local expertise cuts days off the timeline, preventing procedural hiccups that stall closings.
Partnering with AHL HardMoney for Equity-Driven Results
Securing private funding from a reputable Florida hardmoney lender should provide relief, not create additional hurdles. AHL HardMoney operates as a dedicated balance-sheet lender holding NMLS ID 380601, delivering transparent decisions without passing your file to remote committees or unverified brokers. If you have substantial equity in Florida real estate, credit blemishes, prior bankruptcies, or tax challenges won't stop you from securing the capital you need.
Our team delivers initial loan reviews in as little as 30 minutes and funds closings within 5 to 15 business days. When pressing financial deadlines demand direct answers and immediate action, connect with the AHL HardMoney team to discuss your situation. Take charge of your property equity and explore private financing solutions tailored to your goals.
Unlock Your Real Estate Value with Direct Florida Private Capital
Navigating time-sensitive property challenges doesn't require waiting on institutional bureaucracy. Partnering with a dedicated Florida hardmoney lender ensures your real estate equity remains your strongest financial tool. Whether you need to halt an impending foreclosure, resolve urgent IRS tax liens, or pull liquidity from an unencumbered asset, asset-based underwriting prioritizes tangible collateral over automated FICO formulas.
As a direct balance-sheet lender holding NMLS ID 380601, AHL HardMoney delivers fast, practical financing solutions tailored to your unique circumstances. With loan reviews delivered in as little as 30 minutes and closings completed within 5 to 15 business days, past credit hurdles won't prevent you from securing reliable capital when timing matters most.
Take the next step with confidence, knowing you have a resourceful local partner ready to help you protect your assets and move your investments forward.
Frequently Asked Questions
What is a Florida hard money lender and how does it differ from a bank?
A Florida hard money lender is a private, asset-based financing source that secures loans directly against real estate equity rather than personal credit scores. Unlike traditional depository banks that rely on automated algorithms, W-2 tax forms, and lengthy underwriting committees, private lenders make direct balance-sheet funding decisions. This allows for much faster approvals and flexible terms focused purely on the property's protective value.
Can I qualify for a Florida hard money loan with bad credit or past bankruptcy?
Yes, you can qualify for financing even with severe credit blemishes, open collections, or prior bankruptcies. Because private asset-based underwriting prioritizes your property's equity over your FICO score, your credit history isn't the deciding factor. If your real estate holds sufficient protective equity to secure the loan balance, a direct Florida hardmoney lender like AHL HardMoney can approve your request regardless of past financial setbacks.
How fast can a private hard money loan close on a Florida property?
A private hard money loan can close within 5 to 15 business days from your initial application. Because direct balance-sheet lenders bypass traditional banking committees and automated federal red tape, initial approvals often take as little as 30 minutes. Once clean title work, municipal lien checks, and basic property verifications are complete, loan proceeds are wired directly to escrow for immediate disbursement.
Can a Florida hard money loan stop a scheduled foreclosure sale?
Yes, securing an emergency foreclosure refinance loan can effectively halt a pending auction by paying off delinquent mortgage balances before the sale date. In Florida's judicial foreclosure system, time is critical. Direct private lenders move rapidly to coordinate with your payoff servicer and closing title agent, clearing outstanding default amounts and preserving your hard-earned property equity before the court-ordered auction takes place.
What types of real estate can be used as collateral for private loans in Florida?
Private capital can secure a wide spectrum of Florida properties with sufficient equity. Collateral options include single-family residential properties, multi-family apartment buildings, commercial real estate, mixed-use buildings, and high-value luxury estates. Whether your property is located in dense metro areas like Tampa, Orlando, and Saint Petersburg or growing secondary markets across Pasco and Polk counties, solid equity makes the transaction viable.
What documentation is required to apply for asset-based financing in Florida?
Applying requires minimal documentation compared to the exhaustive audits demanded by conventional banks. You typically need a valid government-issued photo ID, basic details about the real estate, and current payoff statements for existing liens or mortgages. Borrowers don't need to submit years of personal tax returns, W-2s, or complex debt-to-income schedules, which makes asset-based financing ideal for self-employed professionals and real estate investors.
Is an upfront appraisal always required before approving a Florida private loan?
No, an expensive, slow bank appraisal isn't always required. Experienced private lenders often evaluate property value using localized comparative market analyses, recent neighborhood sales, and direct internal reviews. Working with an established Florida hardmoney lender that understands regional market values across Tampa Bay and Central Florida prevents weeks of appraisal delays, allowing underwriting decisions to finalize in just minutes.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


