
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
Could the equity in your Tampa home help cover an urgent expense without putting your long-term stability at risk? If “emergency home equity loan Tampa” is the search that brought you here, start with three essentials: the equity that may be available, your deadline, and a realistic repayment plan.
An urgent bill or repair can make speed feel like the only thing that matters. But a home equity loan is secured by your property, so understand the trade-offs before moving forward. Your equity, existing mortgage and liens, credit history, and ability to repay all help shape the decision. If repayment becomes difficult, your home could be at risk.
This 2026 guide explains how equity-based financing works, how a home equity loan compares with a cash-out refinance, and what information to gather before discussing a potential loan. AHL HardMoney, LLC is headquartered in Tampa and offers home equity loans and cash-out refinance options using an asset-based approach. The company serves Florida borrowers in Tampa, Clearwater, Saint Petersburg, Palmetto, Largo, Newport Richey, Port Richey, Brooksville, Brandon, Orlando, Daytona, Naples, Ocala, Deltona, Deland, Jupiter, Palm Beach, Lakeland, and Boca Raton. Use the guidance below to prepare for a focused discussion and evaluate your options.
Key Takeaways
- Before pursuing an emergency home equity loan Tampa, identify the expense, estimate your usable equity, and build a realistic repayment plan.
- Understand the steps from property and lien review through closing. Treat approval and funding timelines as estimates, not promises.
- Compare a home equity loan with a cash-out refinance by considering your current mortgage, lien structure, and financing goals.
- Gather key financial and property information, then test repayment against realistic income and expenses before securing debt against your home.
- AHL’s asset-based approach considers the property alongside other borrower information. The loan remains secured by your home, so repayment risks matter.
Emergency Home Equity Loans in Tampa: Start With the Urgent Need
An urgent expense can make a home equity loan seem like a straightforward answer. But urgency doesn’t eliminate the need to review the property, existing liens, documents, repayment plan, and collateral risk. An emergency home equity loan Tampa homeowners consider is secured by their property, so weigh both the immediate need and the longer-term cost of taking on debt.
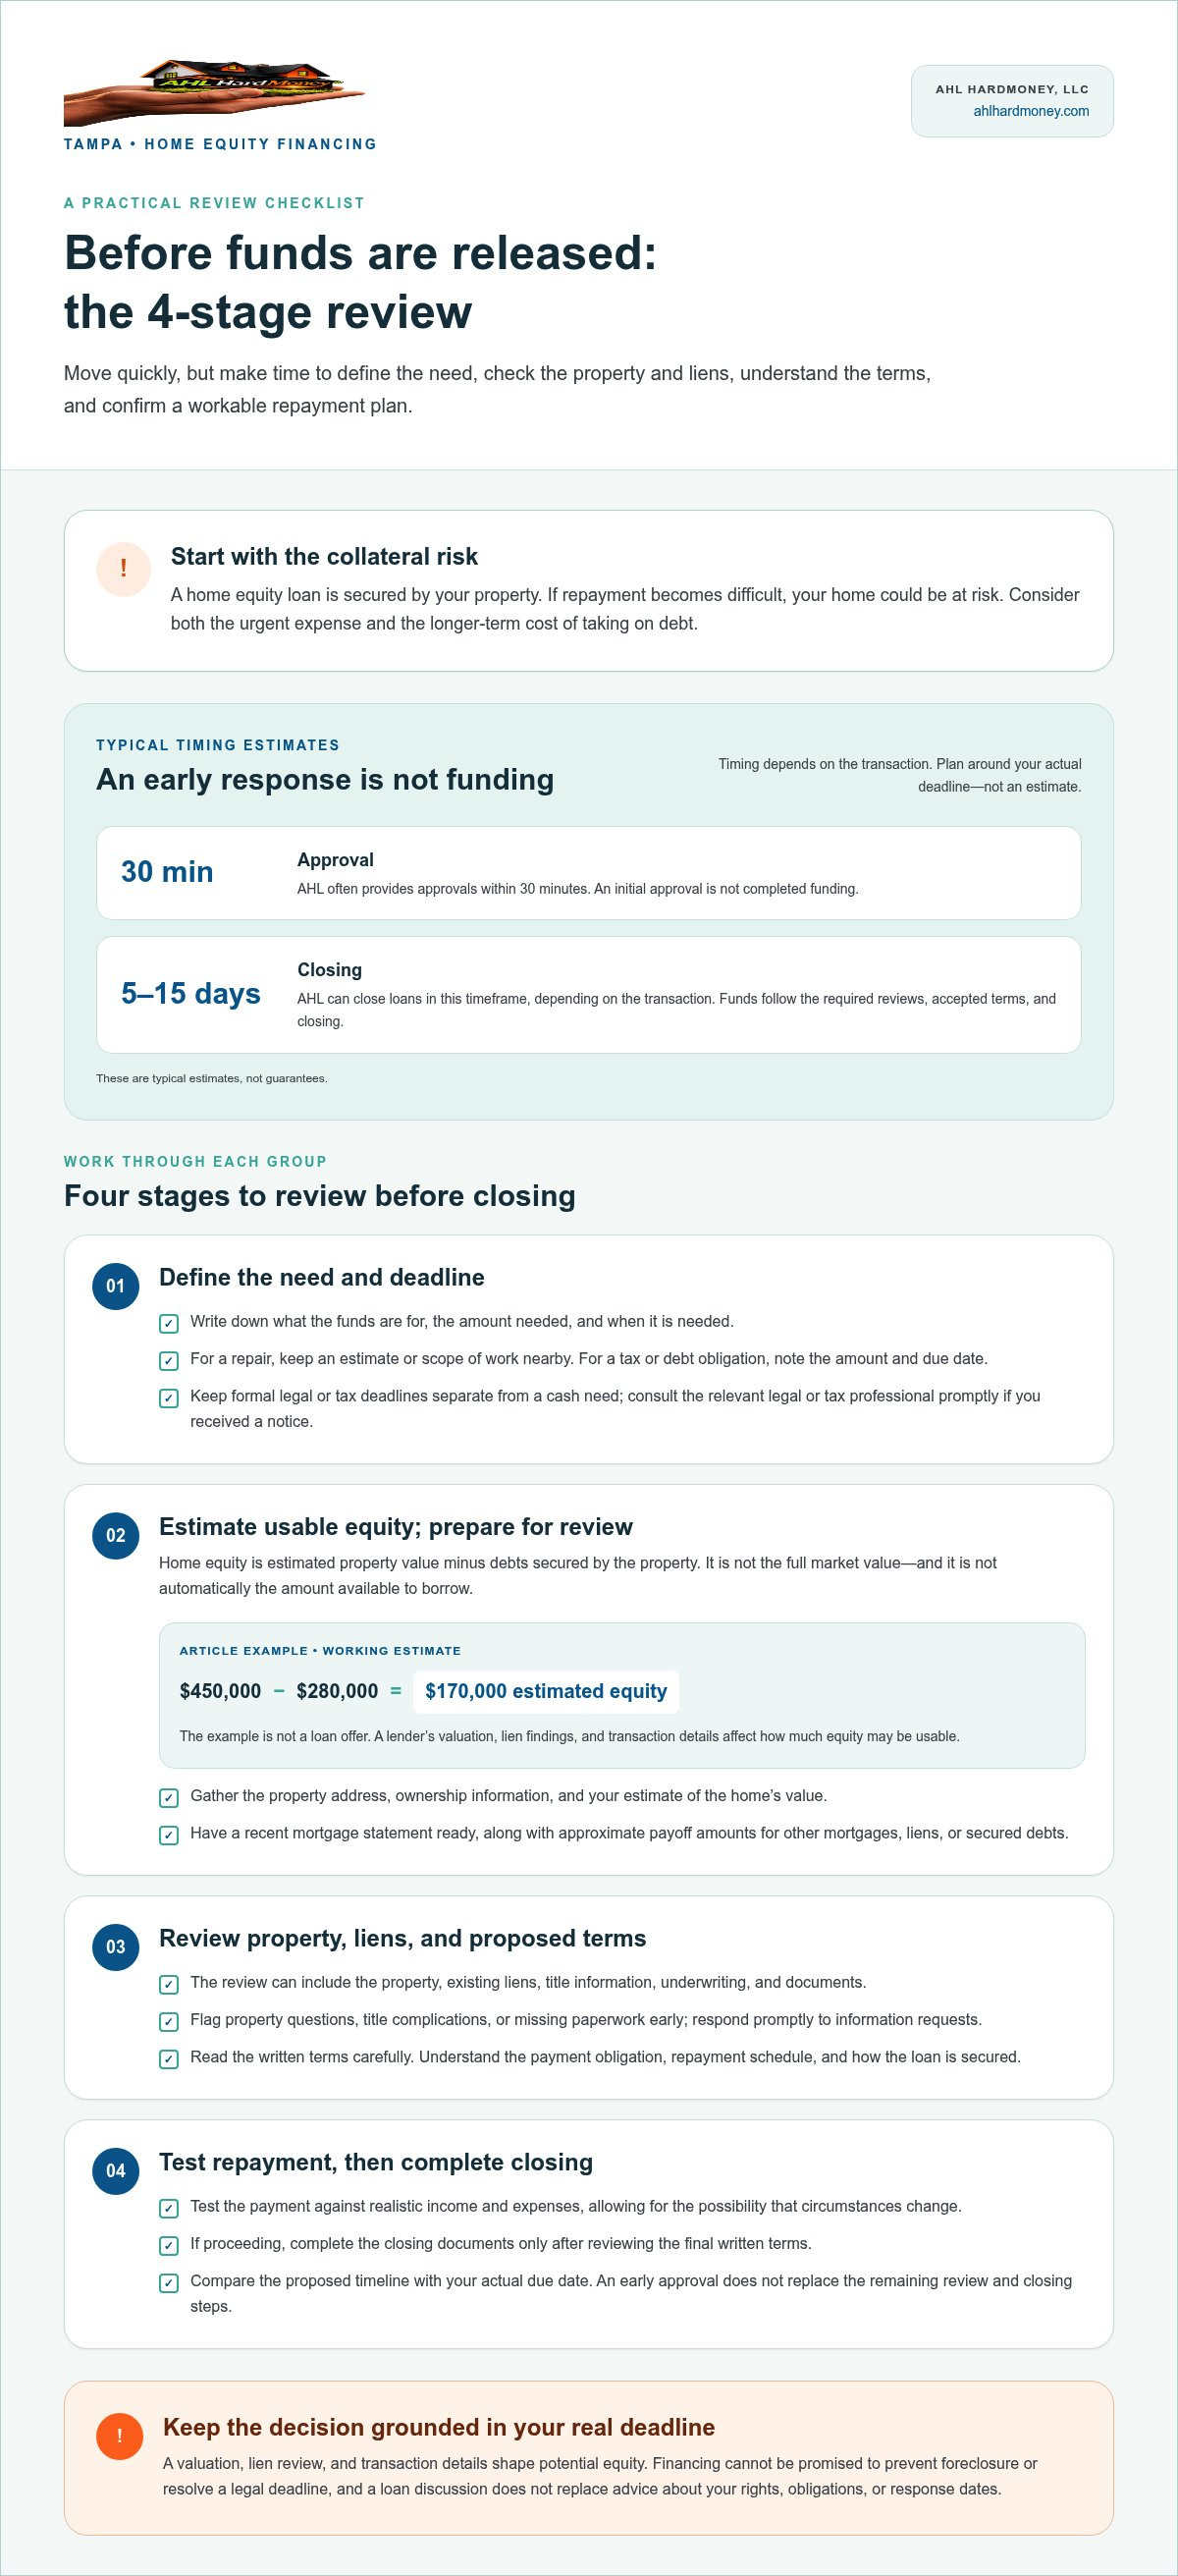
Home equity is the estimated value of your property minus the debts secured by it; it isn’t the home’s full market value. A lender’s property valuation and lien review help determine whether equity may be available to borrow. The general concept is covered in this overview of the Home equity loan.
For a clear introduction to how this type of financing works, watch:
What does home equity mean for a Tampa homeowner?
Start with a working estimate: subtract the mortgage balance and other debts secured by the property from its estimated value. For example, if a home is estimated at $450,000 and its mortgage and other secured debts total $280,000, the estimated equity is $170,000. That is not a loan offer, and it doesn’t mean the full amount is available to borrow. A lender’s valuation, lien findings, and transaction details affect how much equity may be usable.
Gather a recent mortgage statement and details of any other liens or secured obligations. These figures help frame an initial conversation, but they don’t replace the lender’s review.
Which emergencies may prompt an equity-based loan?
The reason for the request affects what you need to consider. A major roof leak or another urgent home repair may call for a defined amount and a clear repair timeline. Tax obligations or mounting debt raise different questions: how much is due, when it’s due, and whether a new payment fits your budget. An approaching foreclosure concern is especially time-sensitive. AHL offers Florida foreclosure refinance loans, but financing can’t be promised to prevent foreclosure or resolve a legal deadline.
Separate an immediate cash need from a formal legal or tax deadline. If you’ve received a notice, consult the relevant legal or tax professional promptly. A loan discussion does not replace advice about your rights, obligations, or response dates. Then test repayment against realistic income and expenses, allowing for the possibility that circumstances change.
There’s no universal fit. A home equity loan adds debt secured by your home, and missed repayment can put the property at risk. Move quickly, but define the need, confirm the deadline, and consider whether the payment is sustainable before using your home as collateral.
How Tampa Home Equity Loans Work When Time Matters
A clear process helps you use limited time well. An emergency home equity loan Tampa request typically moves through an initial assessment, property and lien review, review of proposed terms, closing, and funding. Each stage answers a different question: Is there potential equity? What claims are already recorded against the property? Do the terms and repayment fit? What must be completed before funds can be released?
AHL HardMoney, LLC often provides approvals within 30 minutes and can close loans in 5 to 15 days, depending on the transaction. These are typical estimates, not guarantees. An initial approval is not completed funding; funds follow the required reviews, accepted terms, and closing. Plan around your actual deadline rather than treating an early response as money in hand.
What information helps assess available equity?
Having key details ready can make the first assessment more focused. Gather the property address, ownership information, your estimate of the home’s value, and a recent mortgage statement showing the balance. Also note approximate payoff amounts for any other mortgages, liens, or debts secured by the property. These figures help frame the review, but they don’t establish the lender’s valuation or determine how much may be available.
Summarize what the funds are for and when they’re needed. For a repair, keep an estimate or scope of work nearby. For a tax or debt obligation, identify the amount and due date. The goal is to explain the need clearly, not to assume the financing will match it.
What happens between review and closing?
After the initial assessment, the lender reviews the property and existing liens, evaluates title information, and completes underwriting and document review. You then review the proposed terms and, if proceeding, complete the closing documents. Property questions, title complications, or missing paperwork can add time, so respond promptly to requests and flag anything unusual early.
Before signing, read the written terms carefully. Make sure you understand the payment obligation, repayment schedule, and how the loan is secured by the property. Don’t rely on an informal estimate in place of the final documents. AHL’s home equity loans are secured by real estate, so clarity about the commitment matters as much as speed.
To keep the process organized, make a short file with ownership and mortgage details, lien information, the purpose and deadline, and documents that support the request. Compare the proposed timeline with your actual due date. If there isn’t room for review and closing before the deadline, recognize that early rather than assuming the transaction can meet it.
For context on AHL’s Tampa-based approach, learn about the team and its lending focus. A responsive process can clarify next steps, but it doesn’t remove property review, documentation, or repayment responsibilities.
Home Equity Loan vs. Cash-Out Refinance in Tampa
Both options use home equity to access funds, but they affect your mortgage obligations differently. A home equity loan generally adds a separate debt secured by the property. A cash-out refinance replaces an existing mortgage with a new refinanced loan structure that provides funds from the equity. The right comparison depends on your current mortgage, other secured debts, the amount and purpose of the funds, and the written terms available to you.
| Consideration | Home equity loan | Cash-out refinance |
|---|---|---|
| Existing mortgage | Generally remains in place. | Is replaced by a new refinanced mortgage. |
| Lien structure | Typically creates a separate obligation secured by the property, in addition to existing secured debt. | Uses a new mortgage structure; existing mortgage debt is addressed through the refinance. |
| Purpose | May suit a defined expense when the borrower wants to leave the existing mortgage in place. | May be considered when replacing the mortgage and accessing equity are both part of the goal. |
| Decision considerations | Review the added payment, combined secured obligations, and repayment capacity. | Review the new mortgage terms, total debt, and implications of replacing the current loan. |
This is a structural comparison, not a promise that one option costs less. Actual terms depend on the borrower and transaction, so compare the complete written terms rather than focusing on a single feature or initial estimate.
When might a home equity loan fit the situation?
A homeowner who wants to keep an existing mortgage in place may consider a separate home equity loan for a defined need. For example, someone facing a major repair could compare the proposed new payment with household cash flow while accounting for the original mortgage and other liens. AHL offers home equity loans in Florida, providing one option to explore. Available equity and loan terms depend on the review.
When might cash-out refinance deserve consideration?
A cash-out refinance may merit a closer look if replacing the current mortgage is part of the broader plan, rather than simply adding another secured obligation. Consider how the new loan would address the existing mortgage, what additional debt remains, and whether the resulting payment and terms are sustainable. AHL’s cash-out refinance options are distinct from a home equity loan. This Florida cash-out refinance equity guide offers further context for evaluating the structure.
For an emergency home equity loan Tampa borrowers are considering, map the existing mortgage and every other property-secured obligation before choosing a path. Then compare how each option changes your debt, not just how much cash it may provide. Neither structure is automatically cheaper or better; weigh the specific terms, repayment plan, and risk to the home.
Tampa Borrower Checklist: Risks, Deadlines, and Documents
Before discussing an emergency home equity loan Tampa homeowners may be considering, gather the facts in one place. A clear snapshot of your property, existing debts, funding need, and timing can make a financing review more focused. It can also surface questions to address before taking on another obligation secured by your home.
What should Tampa homeowners prepare before applying?
Organize the information you have, even if some figures are estimates. A tidy file can make it easier to explain your circumstances and respond to follow-up requests.
- Property and ownership: Property address, ownership records, and a reasonable estimate of current value.
- Mortgage and liens: Recent mortgage statements, approximate payoff balances, and details of other debts or liens secured by the property.
- Finances: Income information, recurring household expenses, and current debt payments to help assess whether a new payment could fit your budget.
- Identity and purpose: Identification, the amount you need, how you intend to use it, and documents that explain the expense, such as a repair estimate or tax notice.
- Timing: The date funds are needed and copies of formal notices, including when you received them and any stated response date.
Use realistic figures, not best-case assumptions. Consider whether the payment remains manageable if income falls or expenses rise. Equity in a home doesn’t remove the obligation to repay. If you default, your home may be at risk because it secures the debt. Pause if the proposed payment would leave too little room for essential expenses or other obligations.
How should borrowers assess foreclosure-related urgency?
A financing conversation and legal advice serve different purposes. If you’ve received a foreclosure notice, court document, or other formal communication, promptly consult a qualified legal professional about its meaning and any response dates. For a tax notice, seek advice from a qualified tax professional. Don’t assume a loan review will pause a deadline, prevent foreclosure, or resolve a legal matter.
AHL offers Florida foreclosure refinance options, but financing remains subject to review and repayment obligations. For additional background, this Florida foreclosure bailout loan guide discusses the topic. Treat reading about or discussing financing as one part of your response, not a substitute for addressing formal notices with the appropriate professional.
Before moving forward, write down the actual deadline, the amount needed, your current secured debts, and the payment your budget can support. Compare that payment against income and expenses you can reasonably expect, not an optimistic forecast. If the plan only works under perfect conditions, reconsider the risk before pledging your home.
Explore Emergency Home Equity Financing With AHL in Tampa
An urgent expense can leave little time to sort through financing choices. AHL HardMoney, LLC is a Tampa-headquartered private lender offering home equity loans and cash-out refinance options to borrowers throughout Florida. Its asset-based approach considers the real estate securing the financing alongside borrower and transaction information. Asset-based lending doesn’t mean every applicant qualifies or that repayment risk disappears.
What distinguishes AHL’s approach to property-backed financing?
Property value and the liens against it are important parts of the review. AHL considers the real estate as collateral alongside information about the borrower and transaction. This means a credit score is not the only factor, but credit history may still be considered. Any financing is secured by real estate, so review the terms and your ability to repay carefully.
AHL HardMoney, LLC’s NMLS ID is 380601. Approvals often take 30 minutes, but that is an estimate, not a guarantee or a promise of completed funding. Closings can take 5 to 15 days, depending on the transaction. Property and lien review, required documents, and closing steps all affect timing. An initial approval estimate is not the same as funds being available.
What is the next step for a Tampa homeowner?
Make an initial discussion more useful by collecting a few essentials first. Note the property address and ownership details, your current mortgage balance, and approximate amounts owed on other liens secured by the property. Write down how much you need, what it’s for, and when it’s due. Bring a realistic picture of income, expenses, and existing debt payments so repayment can be considered alongside the urgent need.
Frame the conversation around what you need to understand: whether the property and lien picture may support a financing discussion, what information is still needed, and what the next review steps involve. If you have a formal legal or tax notice, keep its deadline visible and seek advice from the appropriate qualified professional. A financing discussion isn’t legal or tax advice, and funding can’t be promised by a particular date.
If you’re weighing an emergency home equity loan Tampa homeowners might pursue, bring the details together before making a decision. A clear starting point can help you discuss your situation and understand potential next steps without treating an early estimate as final. Because the home secures the debt, understand the written terms and make sure you can reasonably manage repayment before proceeding.
Take Your Next Step With a Clear Plan
An urgent need can make every choice feel immediate. Separate what must happen by a specific deadline from what you can evaluate carefully. For an emergency home equity loan Tampa homeowners are considering, turn the situation into a short decision brief: what the funds are for, when they’re needed, what repayment could realistically look like, and what questions remain.
You don’t need every answer before starting a conversation. Bring the facts you have and be candid about the pressure you’re facing. Keep your home’s security and your long-term budget in view as you consider financing.
A steady, informed decision starts with one clear step. You can move forward with care, even when time feels short.
Frequently Asked Questions
Can I get an emergency home equity loan in Tampa with poor credit?
Possibly, but poor credit doesn’t guarantee approval or rule it out by itself. AHL uses an asset-based approach, giving the property and its equity an important role in the review, while credit history may still be considered. Be ready to explain recent credit challenges and provide accurate information about the property, liens, income, and current obligations. The full financial picture matters.
How fast can a Tampa home equity loan close?
AHL can close loans in 5 to 15 days, depending on the transaction, but this is an estimate, not a promise. Timing may be affected by the property and lien review, title matters, and whether requested documents are complete. An early approval or preliminary response isn’t the same as a completed closing or funds in hand, so compare the estimated process with your actual deadline.
Is an emergency home equity loan the same as a cash-out refinance?
No. A home equity loan is generally a separate debt secured by the property, while a cash-out refinance replaces an existing mortgage with a new refinanced loan structure and provides access to equity. The distinction matters if you want to keep your current mortgage in place or are considering replacing it. Compare the full proposed terms and resulting obligations rather than assuming one structure is automatically less costly.
Can I use a home equity loan to address foreclosure pressure in Florida?
A property-secured loan may be considered as part of a borrower’s response, but financing isn’t guaranteed to prevent foreclosure or meet a court or notice deadline. If you receive a formal foreclosure document, promptly consult a qualified legal professional about its meaning and any response dates. Keep the financing discussion separate from legal advice, and don’t assume a loan review changes the timeline stated in a notice.
What documents should I prepare for an emergency home equity loan?
Gather identification, property ownership records, a recent mortgage statement, and information about other liens or debts secured by the home. A lender may also request income and debt details to understand your financial picture. Include documents that explain the need, such as a repair estimate or a notice showing a tax obligation. Keep copies organized, and note which figures are estimates so they aren’t mistaken for confirmed payoff amounts.
Does a Tampa home equity loan put my house at risk?
Yes. Because the loan is secured by your property, failing to meet repayment obligations can put the home at risk. Before proceeding, test the proposed payment against regular expenses and existing debt, leaving room for unexpected costs or changes in income. If the payment only seems manageable under unusually favorable circumstances, pause and reconsider whether adding property-secured debt is sustainable.
Can I use a home equity loan for taxes or urgent home repairs?
Home equity financing may be considered for needs such as an urgent repair or a tax obligation, subject to the transaction review and loan terms. For example, a roof repair estimate can help define the need, while a tax notice can clarify the amount and due date. Financing is still debt secured by your home. For tax-related notices, get qualified tax advice about your obligations and deadlines.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


