
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
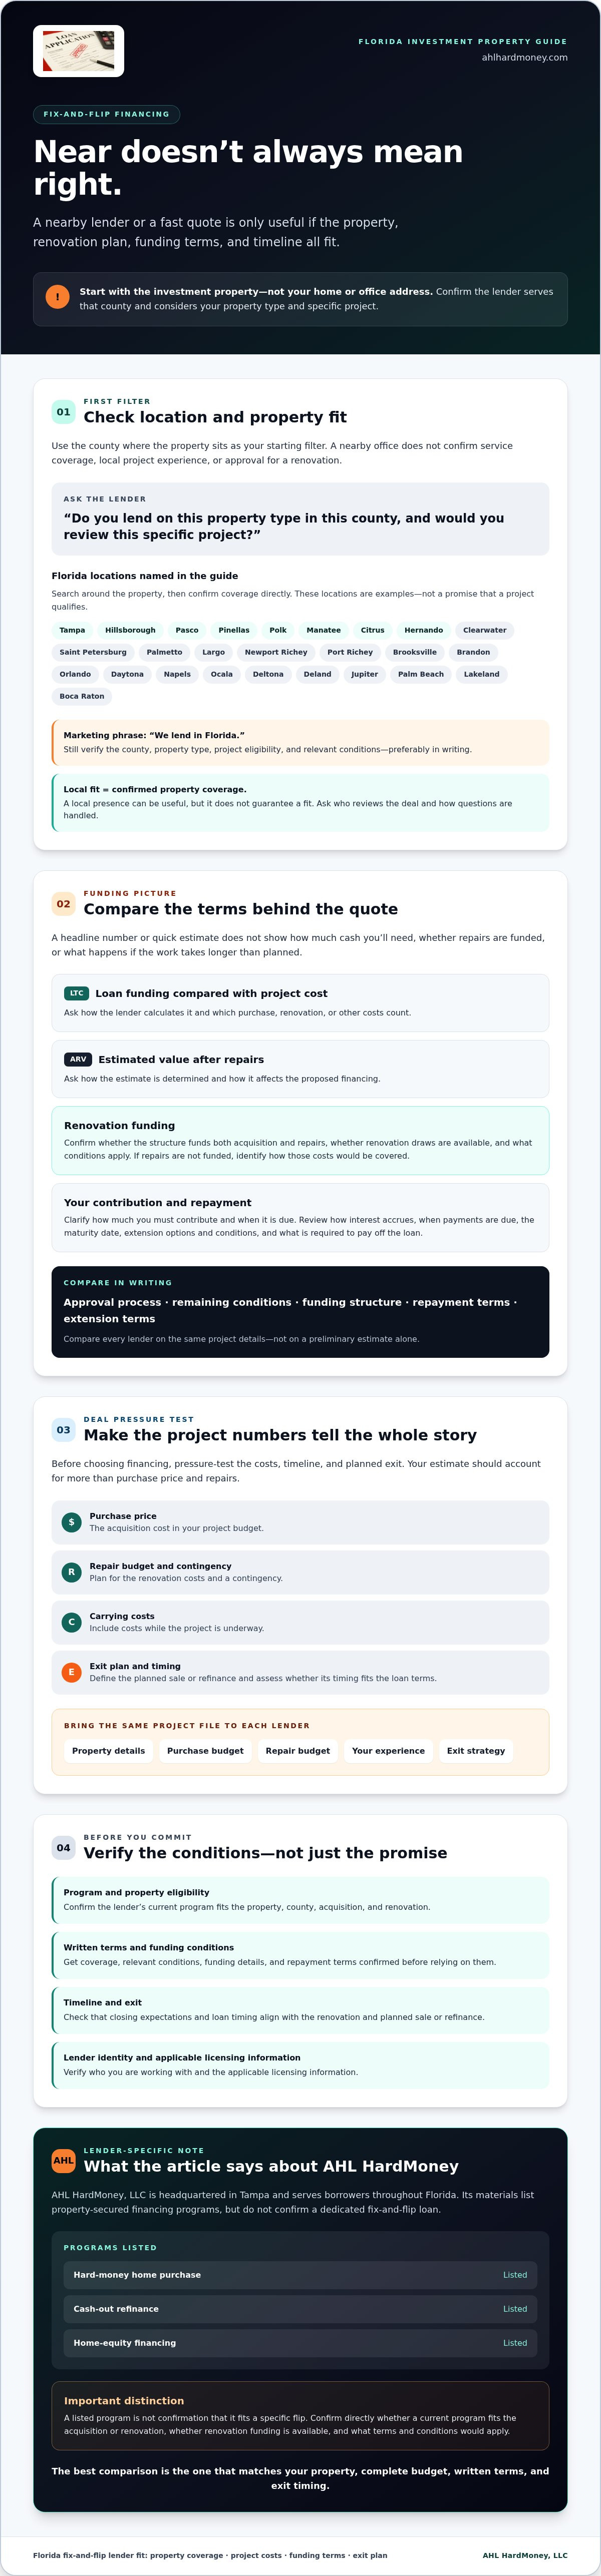
The closest lender may not be the right one for your next Florida flip. Searching “fix and flip lenders near me” is a sensible starting point, especially when a purchase deadline is approaching. But proximity and advertised speed don’t confirm that a lender serves your property’s county, funds renovations, or can work with your project’s numbers. A quick quote only helps when you understand the conditions behind it.
Before you commit, get clear answers about property and project eligibility, your required contribution, renovation funding, repayment terms, and possible delays. Prepare details about the property, purchase and repair budgets, your experience, and your exit strategy so you can compare lenders on the same basis. AHL HardMoney, LLC, headquartered in Tampa and serving borrowers throughout Florida, lists property-secured financing programs, but its materials don’t confirm a dedicated fix-and-flip loan. Confirm directly whether a current program fits your acquisition or renovation and what terms would apply. This guide can help you assess the fit before a funding gap threatens your purchase or project timeline.
Key Takeaways
- Search for fix and flip lenders near me based on the property’s Florida county, then confirm the lender serves that location and property type.
- Compare the full funding picture, including your required contribution, repayment structure, and whether renovation funds and draws are available.
- Pressure-test your purchase price, repair budget, contingency, carrying costs, and planned sale or refinance before choosing financing.
- Verify program fit, written terms, funding conditions, exit timing, and the lender’s identity and applicable licensing information.
- AHL HardMoney, LLC lists hard-money home purchase, cash-out refinance, and home-equity financing. Ask directly whether a program fits your project and whether renovation funding is available.
How to Find Fix and Flip Lenders Near You in Florida
Start with the property, not your home or business address. A lender’s office may be nearby while the investment property falls outside its service area. When searching for fix and flip lenders near me, filter by the property’s county and confirm that the lender considers both that location and your property type.
Florida investors might search around Tampa, Hillsborough, Pasco, Pinellas, or Polk, then expand the search if the deal is elsewhere. If your property is in Clearwater, Saint Petersburg, Palmetto, Largo, Newport Richey, Port Richey, Brooksville, Brandon, Orlando, Daytona, Napels, Ocala, Deltona, Deland, Jupiter, Palm Beach, Lakeland, or Boca Raton, name the location when you contact lenders and ask them to confirm coverage. The basic idea of buying, improving, and reselling property is commonly described as real estate flipping, but financing eligibility depends on the lender’s actual program and the individual project.
For a helpful overview of how fix-and-flip loans work, watch this video:
Which Florida location should determine your lender search?
Use the county where the property sits as your first filter. Ask directly: “Do you lend on this property type in this county, and would you review this specific project?” AHL HardMoney identifies Florida counties including Hillsborough, Pasco, Pinellas, Polk, Manatee, Citrus, and Hernando. Treat its service-area information as a starting point, not confirmation that a particular renovation or acquisition qualifies. Verify current coverage and project fit with the lender.
How can you tell whether a lender is genuinely local?
A nearby office can be useful, but location alone doesn’t establish local project experience. Ask who will review the deal, how you can reach that person with questions, and whether local valuation or closing partners may be involved. Then compare local specialists with statewide or national lenders using the same questions. A larger footprint isn’t automatically better, and a local presence doesn’t guarantee a fit.
Separate specific answers from broad marketing language. “We lend in Florida” doesn’t tell you whether the lender serves your county, accepts your property type, or considers renovation projects. Get coverage and relevant conditions confirmed directly, preferably in writing, before relying on them for a purchase timeline.
Local fit means confirmed property coverage, not just a nearby office. Once you’ve established that a lender can consider the location and project, compare the financing details that shape your deal.
Compare Florida Fix and Flip Lenders by the Terms That Shape Your Deal
Once a lender confirms it can consider your property, compare the written terms with your project budget and schedule. Search results for fix and flip lenders near me may emphasize quick decisions or high leverage, but one headline number won’t tell you how much cash you’ll need or what happens if renovations take longer than planned.
Which loan terms matter most for a fix-and-flip project?
LTC compares loan funding with project cost; ARV estimates the property’s value after repairs. Ask how the lender calculates each figure and which purchase, renovation, or other project costs count. Confirm whether the proposed structure can fund both the acquisition and repairs, or whether you’ll need another source for renovation costs.
Compare the full repayment picture: how interest accrues, when payments are due, the maturity date, any extension options and conditions, and what’s required to pay off the loan. Review the written terms, not just a preliminary estimate. Also check whether the amount you must contribute is due at closing, during the renovation, or at another point in the project.
| Compare | Ask each lender |
|---|---|
| Approval process | What information is needed, who reviews the deal, and what conditions remain? |
| Closing schedule | What steps remain for underwriting, valuation, title, closing, and funding? |
| Borrower contribution | How much cash must I bring, and when will I need it? |
| Repayment structure | What payments are due, when does the loan mature, and what are the payoff or extension conditions? |
How should you compare renovation draws and closing timelines?
Renovation funding may depend on a draw process, so ask whether it’s available and how it works. What evidence is required for each draw: inspections, invoices, or proof that work is complete? Find out who reviews submissions, how funds are released, and whether the process could affect contractor payments or your schedule. If the lender doesn’t offer renovation draws, account for how you’ll pay for the work.
Request a written timeline that identifies underwriting, valuation, title, closing, and disbursement steps, including what could delay each stage. Treat advertised timelines as estimates, not guarantees. Compare the conditions attached to each lender’s schedule alongside your required contribution and repayment obligations.
For consumer mortgage topics, the Consumer Financial Protection Bureau’s mortgage resources offer a useful reference. The rules and protections that apply can depend on the loan and its purpose, so ask a qualified professional about your specific situation.
AHL HardMoney lists property-secured financing options, but whether any option fits a fix-and-flip acquisition or renovation requires direct confirmation. You can review AHL HardMoney’s company background as one part of your lender research.
Does a Fix and Flip Loan Fit Your Property, Budget, and Exit Plan?
A financing offer only fits if it supports the whole project, from acquisition through payoff. Before choosing among fix and flip lenders near me, map out the purchase basis, repair scope, contingency, and carrying costs. Then test whether expected sale proceeds or a refinance can support a realistic exit. A low initial cash requirement won’t help if the funding structure leaves a gap during construction or the repayment date arrives before the property is ready.
Check the project in stages: purchase and closing, repairs, holding period, and sale or refinance. For each stage, estimate when cash is needed and ask which costs, if any, the proposed structure can cover. Build a contingency into your own budget for unexpected work, and test how a slower renovation or lower-than-planned resale price could affect your ability to repay.
What project details should you prepare before contacting lenders?
Give each lender the same clear snapshot so you can compare responses. Prepare:
- The property address or county, property type, and purchase contract status.
- Your intended repairs, preliminary scope and budget, plus a contingency.
- Available comparable sales or valuation information for the lender to review.
- Your relevant investment or renovation experience and the exit you’re considering.
Be ready to discuss property condition, title questions, and valuation assumptions. Share your research, but ask how the lender will conduct its review rather than assuming it will use your estimates. A lender’s assessment of the property and proposed project may differ from yours.
When might another property-backed financing route be more relevant?
If you haven’t bought the property, ask whether a purchase financing option can be considered for your situation. AHL HardMoney lists hard-money house purchase financing, but that doesn’t establish that it covers a fix-and-flip acquisition, renovation costs, or your project. Confirm availability, use, eligibility, and terms directly before relying on it.
Already own the property? If your goal is to access its equity, a cash-out refinance may be worth discussing. AHL lists this as an offering, but don’t assume it will fund a purchase-and-rehab plan or meet a particular project’s needs. Explain whether you’re acquiring, renovating, or using existing equity, and outline your intended exit so the lender can clarify whether a listed financing route may fit.
Fit is project-specific. Make the decision against your property, complete budget, and exit timeline, not a broad product description.
What Florida Investors Should Verify Before Choosing a Fix and Flip Lender
A lender’s initial interest isn’t the same as confirmed funding. Before committing to a purchase or renovation, get clear answers about the property, financing program, and every condition that could affect timing. Use this checklist to turn a promising conversation into details you can verify.
- Confirm property coverage. Ask whether the lender serves the property’s Florida county and considers its property type. Get a direct answer for the specific location rather than relying on broad claims about statewide service.
- Confirm program fit. Explain whether you’re acquiring, renovating, or both. Ask whether the lender currently considers this project and whether renovation funding is available. Don’t assume a general property-backed program covers every stage.
- Get the terms in writing. Review the proposed amount and borrower contribution, payment schedule, maturity date, costs, payoff requirements, and any extension conditions. Check that verbal explanations match the written terms.
- Map the funding process. Ask what documents, valuations, insurance information, inspections, or other conditions are needed, and when funds can be disbursed. Identify anything outstanding that could delay closing or renovation work.
- Test the exit timeline. Compare the loan maturity with your renovation schedule and expected sale or refinance. Ask what happens if work or the exit takes longer than planned.
Which questions should you ask a prospective Florida lender?
Be specific: “Do you serve this county and consider this property type and repair plan?” “Are renovation funds available, and what controls their timing and release?” “Which costs, deadlines, extension terms, and payoff requirements will appear in the written documents?” Ask for unclear conditions to be explained before you rely on them.
Also verify the lender’s identity and check relevant licensing information through appropriate official sources, such as NMLS Consumer Access or the Florida Office of Financial Regulation. Requirements can depend on the lender and transaction, so confirm what applies rather than assuming a listing alone answers the question. Have qualified professionals review the loan documents before accepting conditions or committing to a purchase.
How can you reduce avoidable delays before closing?
Prepare the purchase contract, title and property information, repair scope and budget, and borrower details before submitting the deal. Ask early who coordinates valuation, what insurance information is needed, how closing is handled, and which conditions are still open. A written list of responsibilities and deadlines can help you spot gaps while there’s still time to address them.
For broader context on property-backed financing, consult a Florida hard-money lending guide and compare its general information with the terms offered for your specific project.
How to Explore AHL HardMoney for a Florida Investment Property
Searching for fix and flip lenders near me can lead you to Florida-based lenders with related property-backed programs, but a listed offering doesn’t automatically cover a purchase-and-renovation project. AHL HardMoney, LLC is headquartered in Tampa and lists hard-money home purchase, cash-out refinance, and home-equity financing. Its available information doesn’t confirm a dedicated fix-and-flip program, so ask directly before treating any option as a fit.
What financing options does AHL list for Florida borrowers?
AHL lists hard-money home purchase and refinance options, including cash-out refinance, along with home-equity financing. These are confirmed categories, not a promise that a particular loan can fund both an acquisition and renovation. If foreclosure risk is part of your situation, review the Florida foreclosure refinance information and confirm whether it applies to your circumstances.
AHL reports that approvals often occur within 30 minutes and closings in 5 to 15 days. These are reported timeframes, not guarantees. Before relying on them for a purchase deadline, confirm current eligibility, conditions, required documentation, and the steps that affect the approval and closing schedule.
What should you share when asking about project fit?
Give the lender a clear outline so it can respond to the actual deal. Include:
- The property county, type, and whether you already own it or are under contract.
- The planned work, preliminary repair budget, and how you expect to manage the project.
- Your intended exit, such as resale or refinance, and the timeline you’re working toward.
Then ask plainly: “Can a current program support this purchase-and-renovation transaction?” If the answer is yes, request written clarification of eligibility, funding structure, renovation funding availability, timeline, and all applicable conditions. If the project is in Pasco County, identify that location upfront and confirm current coverage directly rather than relying on a general Florida service statement.
Share the same project details with any lender you’re considering. That makes it easier to distinguish a program that may be relevant from one that actually addresses your acquisition, work, and planned exit. Don’t commit based on a product label or an initial conversation alone.
To discuss your Florida property financing needs with AHL HardMoney, prepare your property location, ownership or purchase status, planned work, and exit strategy, then confirm directly whether a current offering may fit.
Make Your Next Financing Decision With Clarity
The right search for fix and flip lenders near me starts with the property’s county, then moves to the details that can make or break a project: written terms, renovation-funding conditions, your full budget, and a realistic exit timeline. Confirm each lender’s coverage and project fit before you rely on an estimate or commit to a purchase.
AHL HardMoney is headquartered in Tampa and serves borrowers throughout Florida. Its listed programs include hard-money home purchase and refinance-related options, but current fix-and-flip financing availability and renovation funding must be confirmed directly. AHL reports approvals often within 30 minutes and closings in 5 to 15 days. Verify current conditions and timelines, since these are not guarantees.
Have your property location, purchase or ownership status, planned work, budget, and exit strategy ready for a focused discussion. Clear questions now can help you assess your options with greater confidence.
With careful preparation and verified terms, you can take the next step toward a well-planned investment.
Frequently Asked Questions
How do I find fix and flip lenders near me in Florida?
Start with the county where the property is located, then confirm each lender serves that county and considers your property type. AHL HardMoney is headquartered in Tampa and lists Florida counties including Hillsborough, Pasco, Pinellas, Polk, Manatee, Citrus, and Hernando. Investors searching around Clearwater, Saint Petersburg, Orlando, Lakeland, and other Florida communities should still confirm coverage for the specific property. Compare written terms, renovation funding, closing steps, and repayment conditions. A nearby office alone doesn’t confirm project eligibility.
What should I compare when choosing a fix and flip lender?
Compare the complete financing structure, not just an advertised rate or closing speed. Ask how the lender calculates project cost and after-repair value, whether funding may cover the purchase, renovations, or both, and how renovation draws are handled. Review payment schedules, maturity dates, extension conditions, fees, and payoff requirements in writing. Then assess the offer against your project budget, available cash, timeline, and planned exit. A term that looks attractive upfront may not fit your project’s cash needs.
Can a hard money lender finance both a property purchase and renovations?
Some lenders may consider financing that covers both acquisition and repairs, but availability and terms vary. Ask whether the specific program covers purchase costs, renovation costs, or both, and what conditions control each disbursement. Don’t assume a home-purchase loan automatically includes renovation funding. Confirm the current program, eligible property types, borrower requirements, and required project documents before committing. Get the funding structure in writing so you can identify any cash gaps between purchase, construction, and completion.
How quickly can a Florida fix and flip loan close?
Closing time depends on the lender’s review, property valuation, title work, borrower documents, and outstanding conditions. Treat advertised timelines as estimates, not promises for your transaction. Ask for the expected steps and timing in writing, including what you need to provide and what could delay closing. AHL reports approvals often within 30 minutes and closings in 5 to 15 days, but current eligibility, conditions, and timelines should be confirmed directly. Compare the expected schedule with your contract deadlines.
Does AHL HardMoney offer fix and flip loans?
The available company information doesn’t confirm a dedicated fix-and-flip loan program. AHL lists hard-money home purchase, cash-out refinance, and home-equity financing, but that doesn’t establish that any option covers a particular acquisition and renovation. Contact AHL with the property location, ownership or purchase status, planned repairs, and exit strategy. Ask whether a current program fits, then request written details on eligibility, funding structure, timing, and loan conditions before relying on it.
What documents should I prepare before contacting a fix and flip lender?
Prepare the property address and county, purchase contract or ownership details, a repair scope, a preliminary project budget, and your intended exit strategy. Include relevant property and borrower information the lender requests, but ask for its specific document checklist rather than assuming every lender follows the same process. Raise valuation, title, insurance, and renovation-documentation requirements early. Knowing what’s missing can help you address open questions before they affect the proposed closing or funding schedule.
Is a nearby fix and flip lender always the best choice?
No. Local knowledge may help with property-area coverage and communication, but distance alone doesn’t show whether a lender can consider your project or offer suitable terms. Compare local, statewide, and national options using the same questions: Does the lender serve the property’s county? Is the program a fit? Are funding conditions and repayment obligations clear in writing? Verify the closing process and project requirements before choosing. The best fit is the lender that can clearly address your specific deal.
Ready to discuss a Florida property? Contact AHL HardMoney with the property location, purchase or ownership status, planned work, budget, and exit strategy to ask whether a current financing option may fit.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


