
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
What if qualifying for real estate financing had everything to do with the actual value of your property and almost nothing to do with an arbitrary credit score? When you're up against a tight purchase deadline or an impending foreclosure, watching a conventional bank stall over tax returns is exhausting. You've worked hard to build value in your real estate, yet traditional underwriters treat you like a risk on a spreadsheet. In these high-stakes moments, securing a Florida private money mortgage flips the script by prioritizing tangible equity over bureaucratic red tape.
You shouldn't have to wait months for capital that's already sitting in your property. In this guide, you'll discover how private money mortgages work across the Sunshine State, empowering you to leverage existing property equity for fast, transparent funding when traditional lenders say no. We'll walk through the equity-based approval process, Florida-specific closing requirements, and how a flexible short-term loan can bridge the gap to stabilize your financial position.
Key Takeaways
- Understand how a Florida private money mortgage secures fast capital by using your real estate equity rather than strict credit scores or complex tax returns.
- Compare private lending directly against institutional banks to see how asset-based approvals bypass months of red tape.
- Identify how specialized options like a private money refinance can halt foreclosure, resolve tax liens, or unlock cash for urgent opportunities.
- Learn the five-step Florida qualification roadmap to calculate your usable equity and determine workable loan-to-value targets.
- Discover why partnering with a direct, local Florida lender ensures rapid decisions and smooth closings tailored to regional property markets.
What Is a Private Money Mortgage and How Does It Work?
A private money mortgage is a non-institutional loan secured directly by real estate equity rather than a borrower's W-2 tax forms or personal credit history. Instead of relying on deposit-taking banks or government programs, capital flows from private investment groups, dedicated balance-sheet lenders, and individual investors. Often referred to interchangeably with a Hard money loan, this structure shifts the underwriting focus entirely to property value and tangible protective equity.
Mainstream finance often mislabels private lending as an option of last resort. In reality, it functions as a strategic transition tool. When institutional underwriters stall over self-employment income or temporary credit dips, an asset-backed loan provides immediate liquidity. These agreements typically feature short-to-medium-term structures, giving property owners breathing room to acquire, renovate, or stabilize their assets before securing long-term takeout capital or selling.
To see how private lending deals are structured in the real world, watch this practical breakdown:
The Core Mechanics of Asset-Based Lending
Asset-based underwriting replaces tedious red tape with straightforward mathematics. Traditional banks analyze complex debt-to-income (DTI) ratios, scrutinizing years of tax returns and paystubs. Private lenders focus primarily on loan-to-value (LTV) ratios. By measuring the loan request against the realistic market value of your Florida real estate, the lender uses protective equity as the primary loan security benchmark. If the property retains sufficient equity cushion, funding moves forward fast without institutional friction.
Who Funds Private Money Mortgages?
Private capital comes from accredited individual investors, dedicated lending entities, and private capital pools seeking secured returns. In Florida, professional direct lenders operate under strict state licensing oversight to protect consumers. Working with a state-credentialed direct lender means your deal is reviewed by actual local decision-makers rather than an out-of-state automated underwriting algorithm. For an in-depth breakdown of these structural fundamentals, explore what is a hard money loan and how direct capital operates statewide.
Private Money Mortgage vs. Traditional Bank Loan: Key Differences
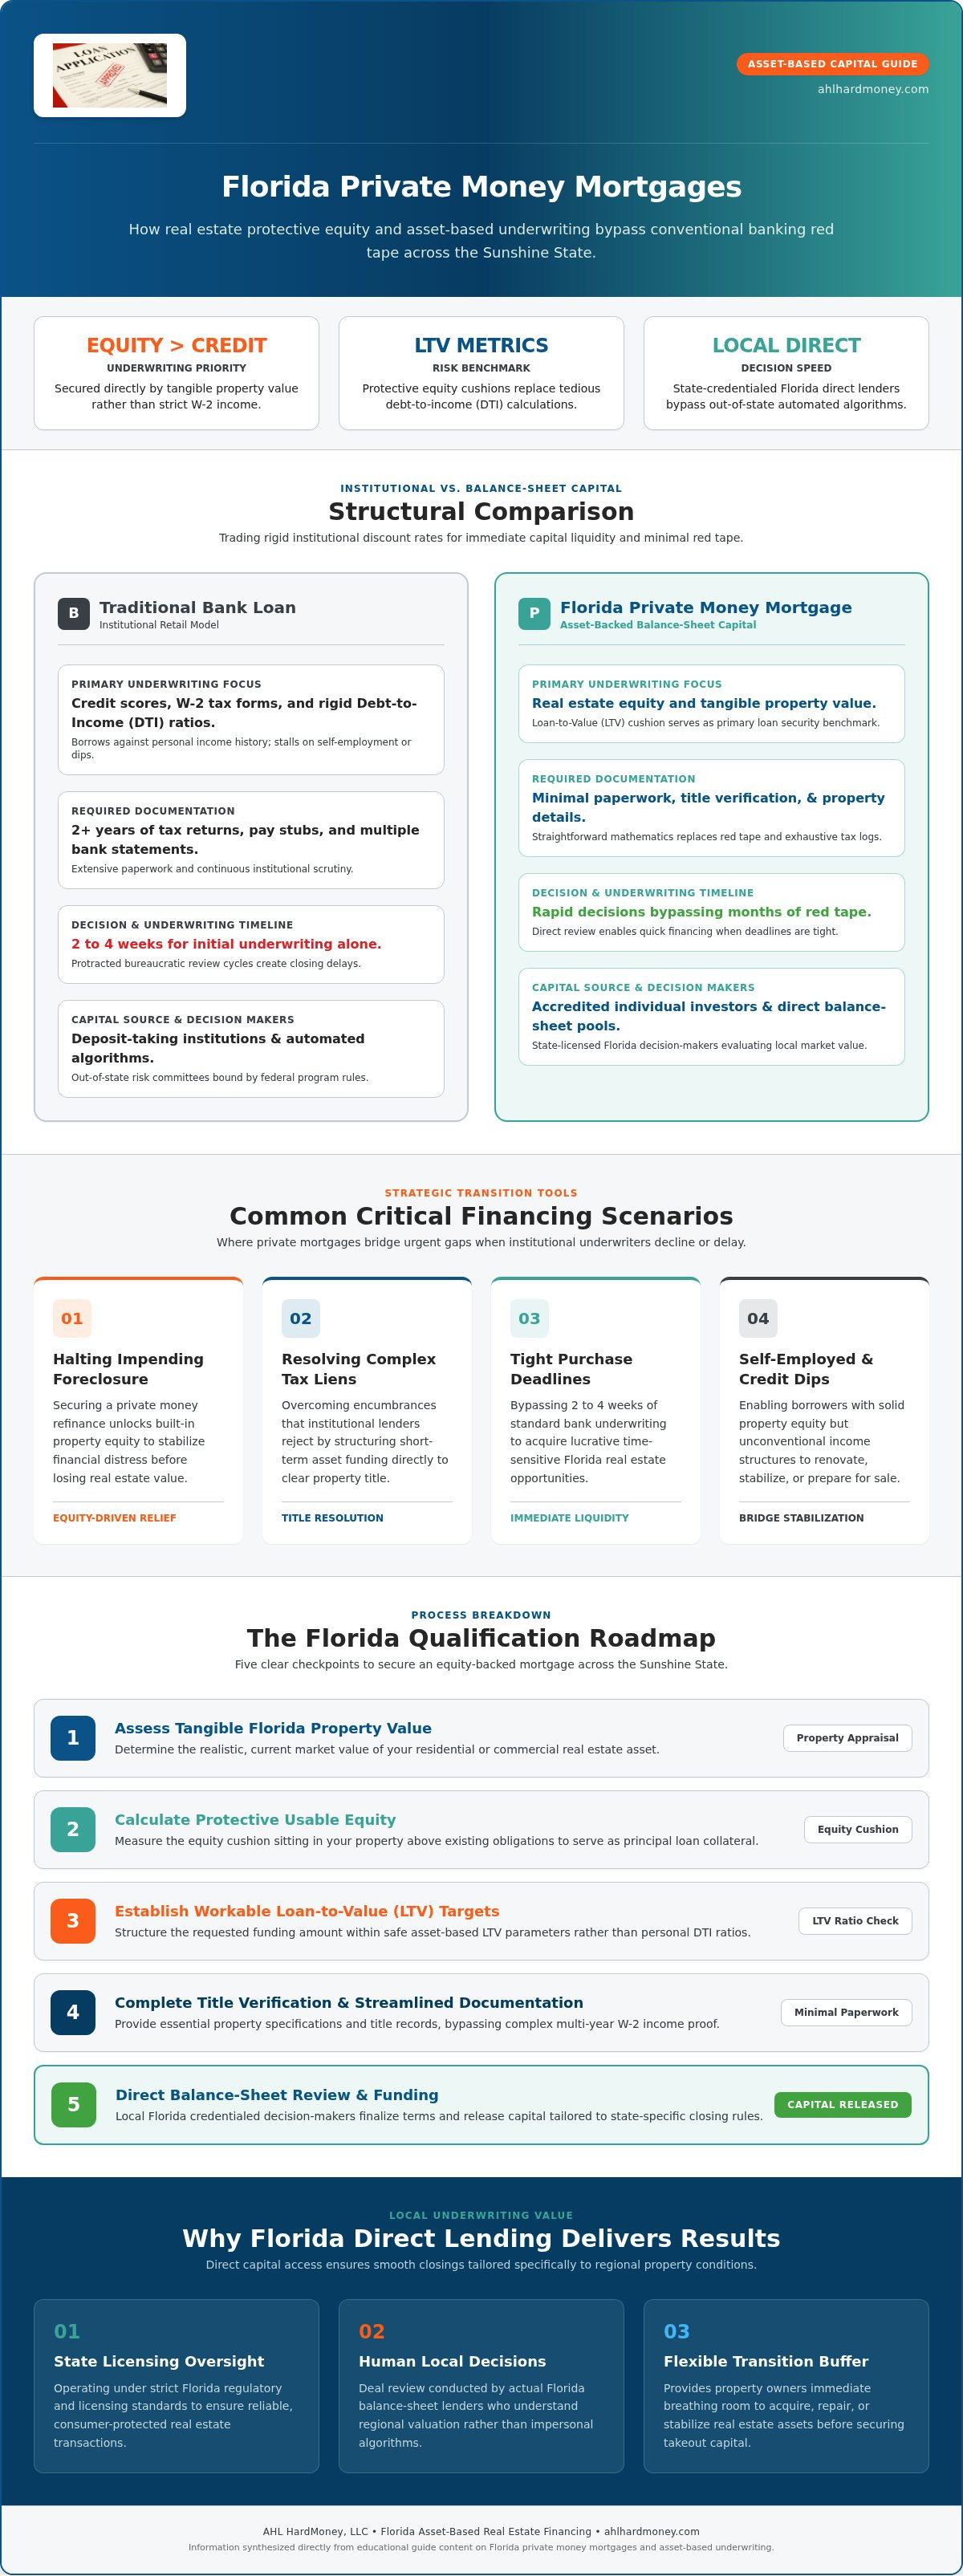
Choosing between conventional bank financing and a private money mortgage comes down to your primary priority: lowest possible interest rates or immediate capital access. While institutional banks compete on retail rates, their rigid underwriting models often fail borrowers who have substantial equity but unconventional profiles. Private lenders operate on asset value, trading the discount rates of institutional lending for rapid decisions and flexible paperwork.
| Feature | Traditional Bank Mortgage | Florida Private Money Mortgage |
|---|---|---|
| Primary Focus | Credit score, W-2 income, DTI ratios | Real estate equity and property value |
| Documentation | 2+ years of tax returns, pay stubs, bank statements | Minimal paperwork, title verification, property details |
| Decision Speed | 2 to 4 weeks for initial underwriting | Approvals in as little as 30 minutes |
| Closing Timeline | 30 to 45+ days | 5 to 15 days statewide |
Underwriting Criteria: Equity vs. Credit Score
Institutional underwriters lean heavily on algorithms. A single tax write-off or an old credit ding can trigger an instant rejection. In contrast, asset-based lending looks at the bigger picture. Self-employed business owners, independent contractors, and investors frequently write off expenses to lower their taxable income, making them appear unqualified to conventional loan software. Because private underwriting focuses on property equity, past credit hiccups or non-standard income records don't stop the process. Review our complete checklist on hard money loan requirements Florida to see exactly how equity thresholds work.
Approval Speed and Closing Timelines
Timing often makes or breaks Florida property transactions. Institutional loan committees move through layers of review, creating multi-week delays that can jeopardize time-sensitive contracts. Working directly with asset-based decision-makers removes those administrative barriers. When an urgent opportunity or financial deadline arises, getting approved within 30 minutes and closing in 5 to 15 days keeps your purchase or recapitalization on track. You can learn more about how our team operates as an approachable local champion on our about our lending team page.
Common Scenarios Where Private Mortgages Solve Critical Financing Gaps
National portals often portray non-bank funding strictly as speculative fix-and-flip capital. That narrow lens ignores real-world challenges property owners encounter across Florida. When life events create urgent liquidity needs, rigid underwriting algorithms cannot assess individual nuance. A private money mortgage serves as an adaptable bridge, transforming trapped balance-sheet wealth into immediate working capital to resolve time-sensitive complications.
Asset-based loans resolve several distinct financial hurdles that traditional lenders refuse to touch:
- Extracting substantial equity from unencumbered residential or commercial holdings
- Halting mortgage default proceedings before judicial auctions occur
- Clearing federal or state tax obligations that prevent conventional refinancing
- Consolidating high-interest short-term debt into a single, manageable real estate note
Accessing Trapped Home Equity Without Bank Delays
Substantial real estate appreciation has left many Florida owners rich in equity but temporarily light on cash. Conventional banks drag out equity lines for months, demanding exhausting paperwork trails. Homeowners seeking immediate funds for major property upgrades, emergency business capital, or strategic market opportunities can deploy a cash out refinance. This path proves especially powerful for real estate owned free and clear, turning locked property value into rapid liquidity without bureaucratic friction.
Preventing Foreclosure and Resolving Tax Liens
Florida operates as a judicial foreclosure state. Once a lender files a lis pendens, the legal clock starts ticking fast. Institutional lenders immediately slam the door on borrowers with active defaults or outstanding IRS encumbrances. Utilizing a dedicated florida foreclosure refinance loan halts court auctions in their tracks. By paying off default balances and municipal liens, borrowers protect accumulated equity and secure the necessary time to reorganize finances comfortably.
Overcoming Self-Employment and Irregular Income Hurdles
Florida's thriving entrepreneurial economy features thousands of business owners, freelancers, and independent contractors. Typical tax strategies legitimately maximize business deductions, yet this lowers adjusted gross income on paper. Conventional loan officers see high risk; direct asset lenders see valuable collateral. Exploring a tailored private money refinance Florida allows self-employed individuals to bypass tax return scrutinization entirely, qualifying on the verified strength of their underlying property equity.
How to Qualify and Apply for a Private Money Mortgage in Florida
Securing a private money mortgage doesn't require months of balance-sheet preparation or complex corporate filings. The qualification process moves quickly because it prioritizes property fundamentals over personal paperwork. Follow this straightforward five-step roadmap to fund your Florida real estate:
- Estimate your equity: Calculate your current property value against any outstanding loan balances.
- Submit property details: Provide basic asset data, location, and your requested loan amount.
- Receive rapid approval: Direct lenders evaluate the asset and issue decisions in as little as 30 minutes.
- Verify title and valuation: Complete a streamlined property check and title search to confirm clear ownership.
- Execute closing: Sign loan documents and receive your funds within 5 to 15 days statewide.
Calculating Your Available Equity and LTV
Loan-to-value (LTV) measures total mortgage debt against the realistic market value of your real estate. If your property appraises at $500,000 and you need a $300,000 loan, your LTV sits at 60%. Private underwriters prioritize this protective equity buffer to mitigate lending risk. A conservative equity cushion lets you access capital on single-family homes, commercial buildings, or investment properties without relying on debt-to-income algorithms.
Preparing Your Essential Property Information
Documentation requirements remain refreshingly straightforward compared to institutional red tape. You only need to provide your recorded deed, current mortgage payoff statements, and property insurance information. Direct lenders inspect physical asset quality, local market demand, and title clarity rather than personal tax write-offs. This focused underwriting bypasses lengthy third-party appraisal gridlocks to keep your transaction on schedule.
Structuring a Practical Exit Strategy
Responsible private lending always includes a realistic repayment horizon. Because a private money mortgage functions as a flexible short-to-medium-term bridge, establishing a clear exit strategy protects your long-term wealth. Common exit paths include refinancing into conventional institutional financing after rebuilding credit, selling the property at peak market value, or utilizing incoming business capital. Having a practical roadmap ensures your equity bridge leads directly toward lasting financial stability.
Why Working with a Local Florida Direct Lender Delivers the Best Outcome
National aggregator websites often route your sensitive financial information to third-party call centers or broker networks. These out-of-state intermediaries lack genuine regional insight and tack on unnecessary layers of broker fees. When you need a private money mortgage to resolve an urgent deadline, dealing directly with a local Florida balance-sheet lender eliminates middleman confusion. You converse directly with the people underwriting and funding your loan, ensuring total accountability from initial review to final settlement.
Working directly with regional decision-makers delivers distinct operational benefits over detached national platforms:
- Immediate direct communication with the lending principals controlling the capital
- Elimination of third-party broker markups and administrative delays
- Deep familiarity with local Florida municipal codes, property appraisers, and title practices
- Agile decision structures that prioritize problem-solving over automated declines
Local Knowledge Across Florida Markets
Florida real estate moves according to hyper-local dynamics. Underwriting an investment property in Hillsborough or Pinellas County requires an entirely different perspective than assessing coastal acreage in Pasco, emerging subdivisions in Polk, or high-density tracts in Orange County. Out-of-state underwriters rely on automated valuation algorithms that frequently misjudge regional market demand. Local lending specialists assess actual neighborhood comps and physical asset strengths immediately, accelerating the equity verification stage. To evaluate regional lending standards and market dynamics across the state, consult our comprehensive resource on hard money lenders Florida.
The AHL HardMoney Direct Lending Advantage
AHL HardMoney operates as Tampa's trusted direct private lender, serving borrowers across the entire state of Florida under Florida NMLS ID 380601. Instead of passing your deal through endless loan committees, our seasoned principals evaluate equity directly. We issue loan approvals in as little as 30 minutes and fund transactions within 5 to 15 days statewide. Whether you need fast funding for urgent recapitalization, debt restructuring, or tailored home equity loans, partnering with a dedicated local champion ensures your equity works for you without institutional red tape.
Take Control of Your Florida Real Estate Equity
Institutional loan rejections don't have to derail your financial timeline. Securing a Florida private money mortgage cuts through bureaucratic delays, giving you the immediate power to halt foreclosure proceedings, clear burdensome liens, or capture urgent real estate opportunities based strictly on your property's value.
As a direct private mortgage lender licensed under Florida NMLS ID 380601, AHL HardMoney supports property owners across Tampa, St. Petersburg, Orlando, and statewide. Our team evaluates your protective equity directly, issuing decisions within 30 minutes and executing closings in 5 to 15 days without middleman markups.
You've built substantial equity in your Florida real estate. Partnering with a dedicated local team ensures that value works for you immediately, providing the rapid bridge you need to achieve long-term financial freedom.
Frequently Asked Questions
Can I get a private money mortgage with bad credit or past bankruptcy in Florida?
Yes, you can qualify regardless of your past credit history or prior bankruptcies. Direct asset-based lenders focus on the usable equity in your Florida real estate rather than your credit score. If your property holds sufficient protective equity to secure the loan amount safely, your application moves forward smoothly without the rigid credit score thresholds required by traditional banks.
How fast can a private money mortgage close compared to a traditional bank loan?
A private money mortgage closes significantly faster than conventional bank financing, often completing within 5 to 15 days across Florida. Traditional banking institutions generally take between 30 and 45 days due to committee approvals and endless paperwork. AHL HardMoney reviews requests directly, providing loan approvals in as little as 30 minutes to accommodate urgent transaction deadlines.
What property types qualify for a private money mortgage with AHL HardMoney?
Qualifying real estate includes single-family homes, luxury estates, multi-unit residential spaces, and diverse commercial properties throughout Florida. Financing extends across key regional markets from Tampa, Clearwater, and St. Petersburg to Orlando, Daytona, and Boca Raton. As long as the property retains clear market value and adequate equity, direct lenders can structure tailored financing to fit the scenario.
What is the maximum loan-to-value (LTV) ratio for a private money mortgage?
Direct private lenders generally structure loans with conservative loan-to-value ratios to ensure a safe protective equity buffer. While institutional lenders push high leverage backed by personal paystubs, asset-based underwriting bases loan amounts strictly on physical property value. Exact ratios depend on property condition, location, and asset class, keeping financing safe for both the borrower and the lender.
Do I need to show income tax returns to qualify for a private money loan?
No, you do not need to provide years of complicated tax returns or W-2 records to qualify. Approval relies on real estate equity, property condition, and title clarity rather than personal tax write-offs. This streamlined approach offers immediate relief to self-employed business owners, contractors, and retirees across Florida whose tax documentation doesn't reflect their true property wealth.
What happens if I need to pay off my private mortgage early?
Early payoff terms vary based on how your individual loan agreement is structured. Because private financing serves primarily as a short-to-medium-term bridge, many borrowers repay their balance early by refinancing through conventional channels or selling the underlying asset. Reviewing note terms upfront ensures complete transparency regarding minimum interest commitments or prepayment schedules before signing.
How does an asset-based private mortgage differ from a predatory hard money loan?
A legitimate private mortgage comes from a licensed, transparent balance-sheet lender dedicated to realistic borrower success. Reputable firms operate under state credentials, such as Florida NMLS ID 380601, offering clear closing terms and feasible exit strategies. Predatory lenders, by contrast, hide inflated backend fees and design unaffordable terms intended to claim property equity through manufactured defaults.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


