
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
What if the right hard money lender is less about a perfect credit profile and more about the equity in your property? If you're searching for hard money lenders Pinellas County, it can be tough to tell which options fit your situation, especially when a refinance, debt, home improvement, or foreclosure concern feels urgent.
That pressure is real, but a clear picture of the property and your financing goal can make the next step easier. Hard money lending is property-based: available equity and value can weigh heavily in a loan discussion, while credit history may also be considered. It helps to know whether you’re speaking directly with a lender or using a directory that refers inquiries elsewhere.
This guide explains how Pinellas County hard money lending works, which financing purpose may align with your needs, and what property and loan details to gather before speaking with a lender. AHL HardMoney, LLC is headquartered in Tampa and provides hard money financing in Florida, including Pinellas County. Its options include cash-out refinance, home equity loans, debt consolidation, home improvement, and foreclosure refinance. You’ll leave with a clearer view of what to prepare and what the process may involve.
Key Takeaways
- Hard money lending uses real estate as security, so the property and its existing obligations help frame the loan discussion.
- When comparing hard money lenders Pinellas County, start with your financing goal and the type of property-based loan that may fit it.
- Prepare for a more productive conversation by identifying the property, gathering details about current liens, and outlining your repayment plan.
- Cash-out refinance, home equity, private money refinance, and debt consolidation address different needs, so clarify what you want the financing to accomplish.
- AHL HardMoney serves Pinellas County from its Tampa headquarters, with multiple financing purposes to consider alongside your property and repayment plan.
Pinellas County Hard Money Lenders: Roles and Clients
Property owners and real estate investors in St. Petersburg, Clearwater, Largo, and other Pinellas County communities may consider hard money financing when a property-related need calls for a different route than an institution-led mortgage process. That need might be refinancing an existing loan, accessing property equity, funding improvements, or consolidating debt as part of a broader financial plan. The appropriate financing purpose depends on the property and borrower’s circumstances, not simply the city or urgency of the request.
A hard money loan is financing secured by real estate. In an asset-based discussion, the property’s value and equity help a lender assess the collateral, alongside existing obligations and the proposed loan purpose. Property equity can support an asset-based lending discussion, but it doesn’t by itself guarantee approval or determine the final loan terms. Credit history may also be considered. The hard money loan overview offers broader context on how this type of financing differs from conventional lending.
For local borrowers, the distinction between a direct lender and a directory matters. A directory connects people with lenders or collects inquiries for referral; it isn’t necessarily the source of financing. A direct lender discusses its own lending process with the borrower. AHL HardMoney, LLC is a privately owned, non-institutional Florida lender headquartered in Tampa and serving Pinellas County, so local property owners can discuss real-estate-secured financing directly with the company.
Which Pinellas County borrowers may explore hard money financing?
Consider a Clearwater owner looking to refinance, a Largo homeowner exploring equity for a property improvement, or a St. Petersburg investor considering financing for a real estate project. Each has a different objective, and each conversation starts with the property and intended use of funds. AHL’s property-secured options include home equity loans, cash-out refinance, debt consolidation, and home improvement financing. Exploring an option isn’t the same as qualifying for it.
How hard money lending differs from a traditional bank mortgage
A traditional bank mortgage generally follows an institution’s mortgage process and eligibility criteria. A non-institutional, asset-focused discussion gives particular attention to the real estate securing the financing and the borrower’s plan for repayment. That difference doesn’t mean credit history is ignored or approval is automatic. Hard money financing carries repayment obligations, and the property is collateral. Borrowers should understand the commitment and consider how the planned repayment fits their wider financial picture.
How property equity and credit history shape a Pinellas loan discussion
For a property-backed loan conversation, equity is a starting point for understanding what the real estate may support, not a shortcut to an answer. In simple terms, equity is the property’s estimated value considered alongside the debts secured against it. A property with a mortgage needs to be discussed differently from one with no mortgage or with additional liens. The amount of equity available can’t be judged from value alone.
The purpose matters, too. A request to refinance, access funds for improvements, or consolidate debt raises different questions about the property and the borrower’s plan. A Florida cash-out refinance discussion, for instance, is clearer when the owner explains both the obligations connected to the property and how the proceeds would be used.
What property and debt details help frame the conversation?
Before speaking with hard money lenders Pinellas County, assemble a concise picture of the property and the request. You don’t need to have every answer in hand; organized, accurate details help make the initial conversation more focused.
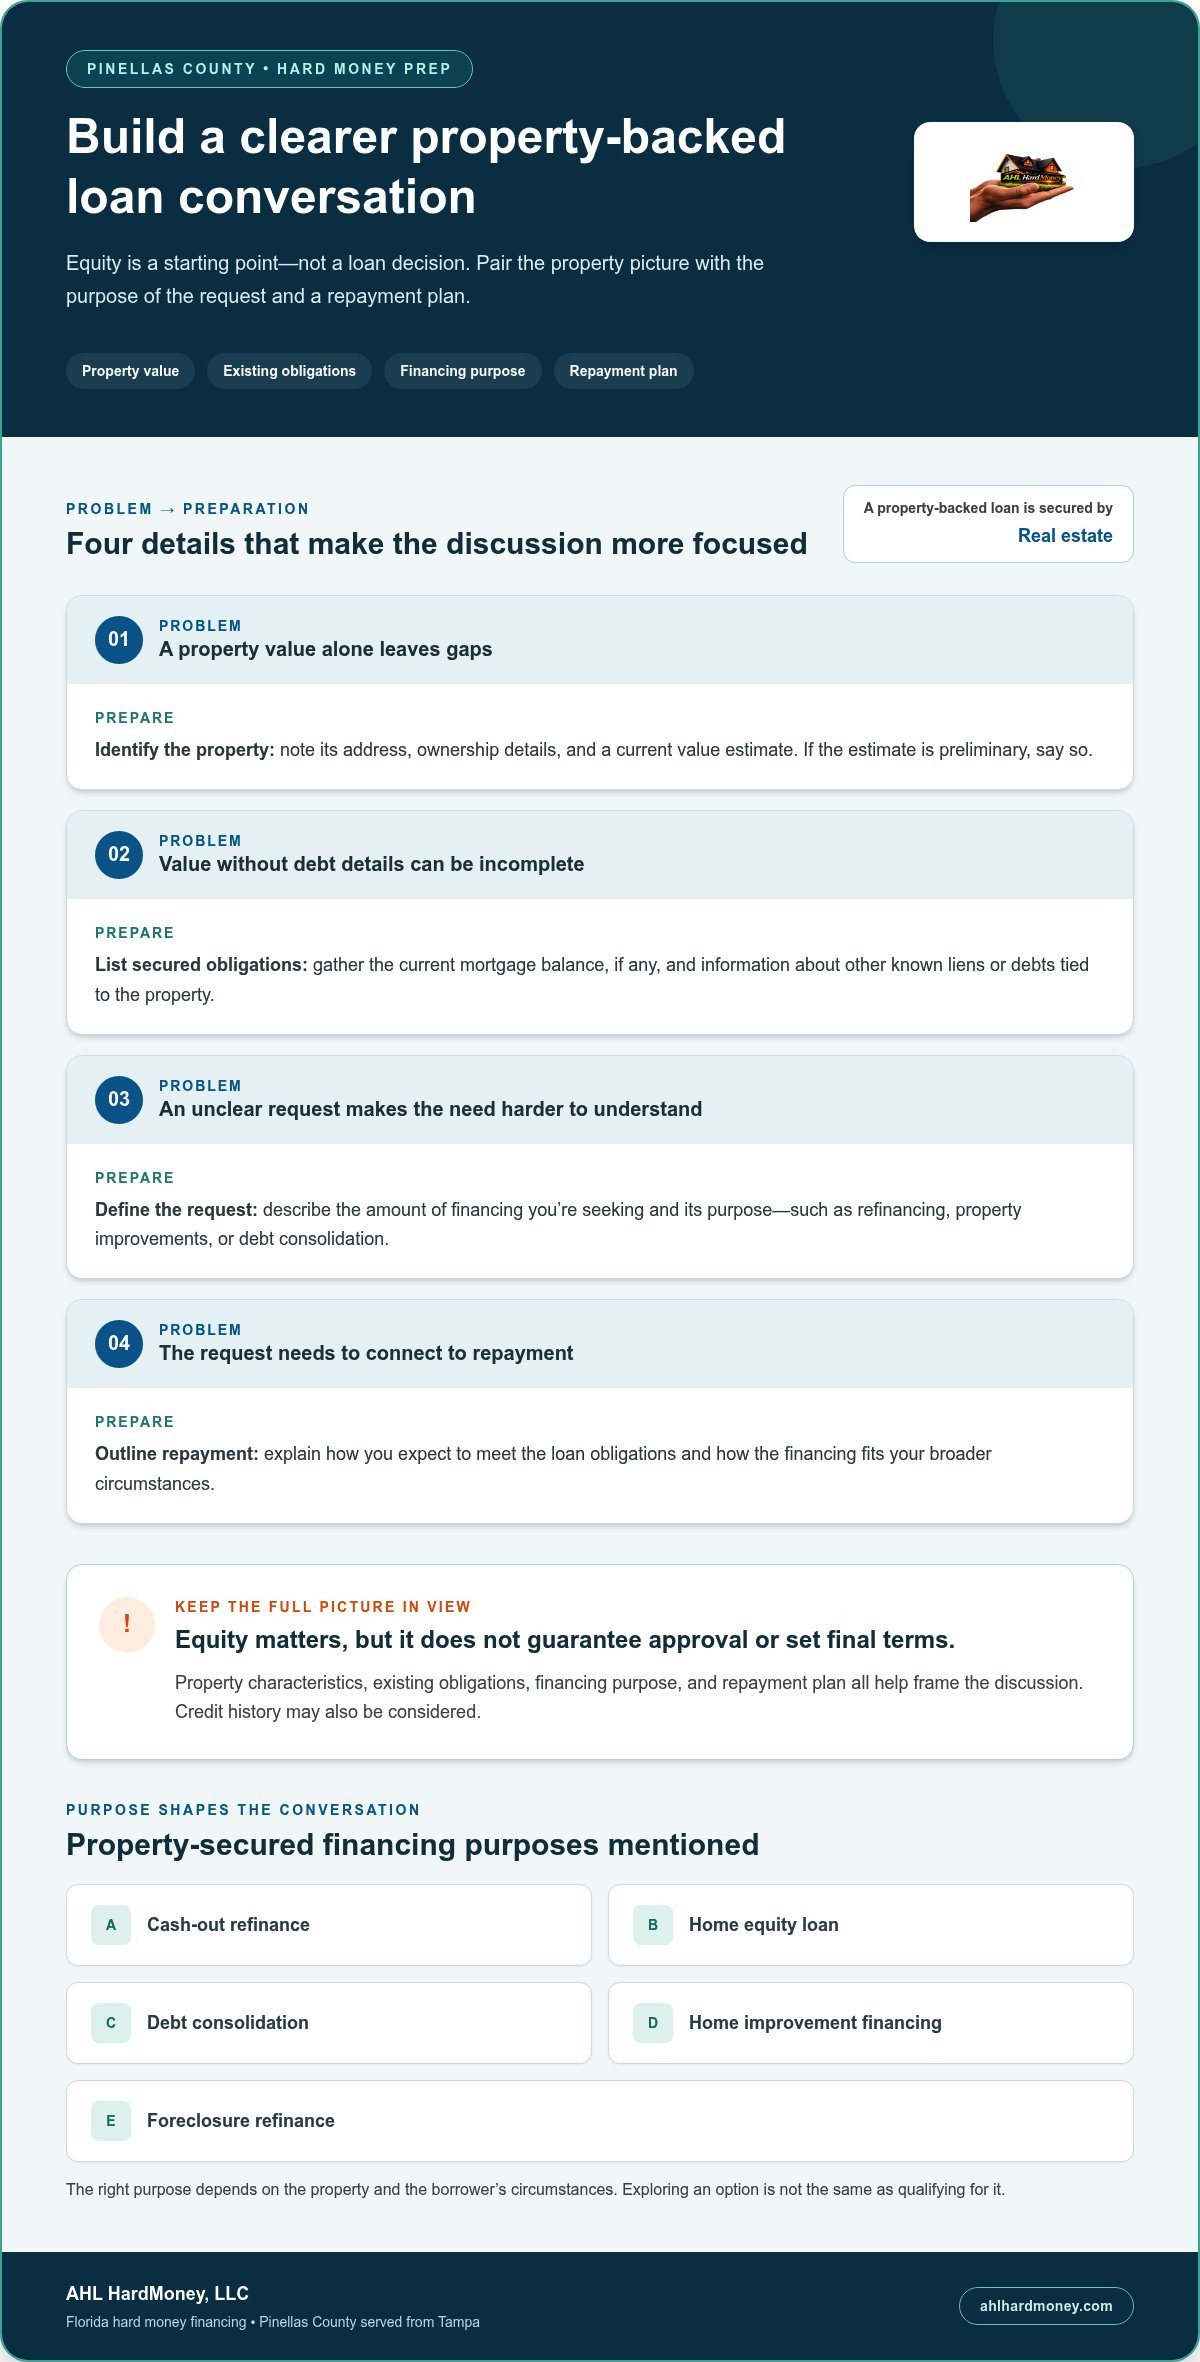
- Identify the property: Note its address, ownership details, and a current estimate of its value. If the estimate is preliminary, say so.
- List secured obligations: Gather the current mortgage balance, if any, and information about other known liens or debts tied to the property.
- Define the request: Be ready to describe the amount of financing you’re seeking and its purpose, such as refinancing, improvements, or debt consolidation.
- Outline repayment: Explain how you expect to meet the loan obligations. A clear plan connects the requested financing to your broader circumstances.
These details work together. A value estimate without information about existing liens may give an incomplete picture, while a loan request without a stated purpose makes it harder to understand the financing need. Be straightforward about what you know and what is still an estimate.
Why equity does not mean guaranteed approval
Equity can be relevant, but it doesn’t promise approval or establish final terms. Property characteristics, existing obligations, the financing purpose, and the repayment plan all help shape the discussion. Credit history may also matter as part of the overall picture. A difficult credit history doesn’t automatically end every asset-based lending conversation, but it shouldn’t be treated as irrelevant or as a guarantee that financing will be available.
Approach the conversation as a review of the whole situation, not a single-number test. AHL HardMoney, LLC serves Pinellas County from its Tampa headquarters. Learn more about AHL HardMoney, LLC as you prepare your property and loan details.
Compare hard money loan purposes for Pinellas County properties
The financing purpose helps frame a useful conversation. A borrower refinancing an existing mortgage may have a different goal from an owner seeking funds for improvements or someone dealing with several obligations. Comparing the purpose, property, and repayment plan can help you explain what you’re trying to accomplish to hard money lenders Pinellas County.
Loan-purpose fit depends on the property and the borrower’s stated goal, not just the name of the financing option. Use this comparison as a starting point, then consider how each purpose relates to your situation.
| Borrower need | Potential financing purpose | Key discussion point |
|---|---|---|
| Refinance and access property equity | Cash-out refinance | Explain the existing mortgage, the requested funds, and how you plan to use them. |
| Explore financing based on home equity | Home equity loan | Describe the property, current obligations, and reason for accessing equity. |
| Replace or restructure existing financing | Private money refinance | Clarify what you want the refinance to address and how you plan to repay. |
| Address multiple financial obligations | Debt consolidation | Be prepared to outline the obligations and the role property-secured funds may play. |
When might refinance, home equity, or debt consolidation be relevant?
A cash-out refinance discussion connects an existing mortgage with a goal of accessing available property equity. Home equity financing focuses on the property’s equity as part of the request; explore Florida home equity loan options in relation to your current obligations and intended use. Debt consolidation is a separate purpose: a borrower may explore property-secured funds to address multiple obligations. In each case, describe the goal clearly rather than assuming one option fits every circumstance.
Private money refinance is another distinct purpose for borrowers seeking to refinance existing financing through a non-institutional lender. Explain the current arrangement and what the proposed refinance is intended to change. A clear purpose makes it easier to discuss the property and repayment plan in context.
How do foreclosure, tax, and improvement needs differ?
Foreclosure-related refinance deserves its own discussion because it involves a specific, time-sensitive property concern, not simply a general wish to access equity or combine debts. AHL offers Florida foreclosure refinance options, but financing isn’t a guaranteed resolution. Tax-related financing is another distinct purpose, while home improvement financing centers on planned work to the property. For each, explain the need and how repayment fits your plan.
Prepare for a hard money lender conversation in Pinellas County
A focused first conversation starts with a clear picture, not a perfect application file. Before contacting hard money lenders Pinellas County, organize the basics: what you want to accomplish, which property is involved, what obligations are connected to it, and how you expect to repay the financing. This keeps the discussion specific, especially if timing is a concern.
Use these four steps to get ready:
- Define the goal. State whether you’re exploring a refinance, accessing equity, consolidating debt, or funding property improvements.
- Identify the property. Gather its address, ownership information, and a current estimate of value. Note whether that estimate is informal or based on a recent valuation.
- Gather obligations. List existing mortgage balances and other known liens connected to the property. Prepare the amount of financing you’re seeking.
- Outline repayment. Describe how you expect to meet the loan obligations. If repayment depends on a future event, explain the plan without treating that outcome as certain.
What information should borrowers organize first?
Keep relevant details together so you can summarize them without searching through scattered notes. Include the property’s location and ownership details, estimated value, current financing, and major obligations. Then connect the amount requested to a specific use. For example, distinguish funds intended for planned improvements from funds intended to address existing debt. A concise, accurate overview is more useful than a lengthy explanation with key details missing.
If some figures are estimates, label them clearly. It’s better to describe what you know and what still needs clarification than to present a rough value or balance as final.
How to make a focused initial lending inquiry
Prepare a short summary covering the property, financing purpose, requested amount, timing, and major obligations. AHL HardMoney, LLC states that approvals often take 30 minutes, but timing depends on the individual case and this is not a guarantee of approval. The company also states that closings can take 5 to 15 days; timing for an individual transaction can vary. An early approval discussion and a completed closing are separate steps.
Share urgent dates or deadlines plainly, without assuming when financing will be completed. AHL HardMoney, LLC is headquartered in Tampa and serves Pinellas County. A well-organized overview can help frame the property and financing discussion. For background on the lender, you can learn about AHL before making your inquiry.
Find a Pinellas County financing path with AHL HardMoney
A useful financing discussion brings five pieces together: the property, its equity, the purpose of the financing, existing obligations, and a realistic repayment plan. Keeping those factors in view can help you compare options without assuming that one loan purpose fits every property or borrower. For property owners and investors researching hard money lenders Pinellas County, the next step is to match the need to a relevant financing purpose and share the details plainly.
AHL HardMoney, LLC is a privately owned, non-institutional Florida lender headquartered in Tampa and serving Pinellas County and other Florida counties. Its real-estate-secured financing purposes include property equity access, refinancing, debt consolidation, home improvement, tax-related needs, foreclosure refinance, and home purchases. Each purpose starts with a different borrower goal, and a possible fit is not a promise of approval or a particular result.
AHL’s Florida lending is relevant to property owners across the region, including Tampa, Clearwater, St. Petersburg, Palmetto, Largo, New Port Richey, Port Richey, Brooksville, Brandon, Orlando, Daytona, Naples, Ocala, Deltona, DeLand, Jupiter, Palm Beach, Lakeland, and Boca Raton. For Pinellas County borrowers, the property location, financing purpose, and repayment plan are useful details to include from the outset.
Which AHL programs may align with a property-backed need?
If you’re exploring access to property equity, cash-out refinance and home equity loans may be relevant starting points for a discussion. Private money refinance addresses a separate goal: refinancing existing financing. Debt consolidation focuses on obligations the borrower wants to address, while home improvement financing relates to planned work on the property. The details of the property, the request, and the repayment plan help put each purpose in context.
A foreclosure-related concern is distinct from a general refinance or equity request. AHL offers foreclosure refinance loans for this stated financing purpose, but no loan should be treated as a guaranteed way to prevent foreclosure or resolve a specific situation. Tax-related financing is another separate purpose. Describing the need accurately helps keep the conversation focused on the appropriate type of property-backed financing, rather than treating all requests as interchangeable.
What happens after a borrower identifies a possible fit?
Bring a concise overview of the property, your financing purpose, current obligations, requested amount, and timing. Include what you know about the property’s value and any existing mortgages or liens. If information is estimated, label it clearly. Then explain how you expect to repay the financing. This gives the lender a more complete starting point for discussing the request and next steps.
The first step is a conversation and review, not a commitment or approval. AHL states that approvals often take 30 minutes and closings can take 5 to 15 days; these are company-stated timelines, not guarantees, and outcomes vary by transaction. Keep any time-sensitive dates clear, but don’t rely on a stated timeline as a promise that a particular loan will be approved or close by a specific date.
With the property, equity, purpose, obligations, and repayment plan in view, you can approach the discussion with greater clarity. Learn about AHL HardMoney and prepare for a focused financing conversation.
Take the Next Step With Confidence
A financing conversation doesn’t have to begin with every detail settled. It can begin with a clear question: what would you need to understand before deciding whether a property-backed loan makes sense for you? Write down concerns about repayment, how the financing purpose fits your plans, or what information you still need to evaluate your options. That gives you a practical way to keep the discussion focused and make decisions at your own pace.
If you’re considering hard money lenders Pinellas County, use the next conversation to clarify possibilities, not to rush into a commitment. AHL HardMoney, LLC is headquartered in Tampa and serves Pinellas County. The company states that approvals often take 30 minutes and closings may take 5 to 15 days, though neither timeline is guaranteed. Every situation is individual, and understanding your next step can help you move forward with greater confidence.
With the right questions and a clear view of your priorities, you can approach what comes next with confidence.
Frequently Asked Questions
Do hard money lenders in Pinellas County consider borrowers with bad credit?
Yes, a difficult credit history doesn’t automatically rule out a conversation with every hard money lender. AHL works with borrowers regardless of credit history, but that doesn’t guarantee approval. Be ready to explain relevant circumstances, such as a recent financial setback, and focus on the property, financing purpose, and a realistic repayment plan. Credit is one part of the discussion, not a promise of an outcome.
How quickly can a hard money loan close in Pinellas County?
AHL states that approvals often take 30 minutes and closings may take 5 to 15 days, but neither timeline is guaranteed. The approval discussion and closing are different stages, and timing can vary with the individual transaction. If you’re working toward a deadline, share it early and avoid making commitments based on an estimated timeline until you understand the status and requirements of your specific request.
Can I use property equity for a cash-out refinance in Pinellas County?
Yes, a cash-out refinance can be a way to explore refinancing an existing mortgage while accessing available equity in the property. The amount of equity isn’t determined by an estimate of market value alone; existing mortgage balances and other obligations matter too. For example, an owner considering funds for a major expense should explain the property’s current financing and intended use so the request can be discussed in context.
What information should I prepare before contacting a Pinellas County hard money lender?
Prepare the property address, ownership details, estimated value, current mortgage or lien information, requested financing amount, and intended use. Add a brief explanation of how you expect to repay the loan. If a value or balance is approximate, identify it as an estimate. This gives hard money lenders Pinellas County a clearer starting point and helps avoid leaving out details that could change how the property-backed request is understood.
Can a hard money loan help with a foreclosure-related refinance in Florida?
A foreclosure refinance loan may be relevant to a borrower exploring refinancing in response to a foreclosure-related concern. It isn’t a guaranteed way to stop foreclosure or resolve a particular case. If you’re facing a time-sensitive situation, organize relevant notices, loan information, property details, and any known deadlines before discussing financing. Don’t assume a loan will close in time to address a deadline; outcomes depend on the specific situation.
Are hard money loans the same as traditional bank mortgages?
No. A hard money loan is real-estate-secured financing, while a traditional bank mortgage follows a bank’s mortgage process and criteria. That distinction can shape what information receives attention, but it doesn’t remove repayment obligations or make approval automatic. Before considering any financing, understand what property secures it, what you’re expected to repay, and how the proposed loan fits your plans.
Does AHL HardMoney serve St. Petersburg and Clearwater?
Yes. AHL HardMoney serves Pinellas County, including St. Petersburg and Clearwater. Its Tampa headquarters is outside Pinellas County, while its lending services reach borrowers in multiple Florida counties. If your property is in either city, identify its location and describe the financing purpose in your initial overview. That local detail helps frame the conversation around the property and the request you want to discuss.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


