
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
When comparing Citrus County hard money lenders, start with your property’s equity, the purpose of the funds, and how you plan to repay the loan. If traditional mortgage requirements don’t fit your situation, an equity-focused option may offer another path. Because hard money loans are short term, a clear repayment plan is essential.
To compare options, consider whether the property can support the request, how hard money differs from a standard mortgage, and what repayment timing would mean for your finances. This guide walks through the key factors: property, equity, purpose, timing, costs, and repayment strategy.
AHL HardMoney serves Citrus County borrowers with programs including cash-out refinance and foreclosure refinance. Its lending approach considers real estate equity regardless of credit history. AHL reports that approvals often occur within 30 minutes and closings can take 5 to 15 days; these are typical timelines, not guarantees. Here’s what to consider as you choose a next step.
Key Takeaways
- Compare Citrus County hard money lenders by property equity, loan purpose, timing, costs, and your repayment plan.
- Understand how real-estate-secured financing differs from a standard mortgage, and why the property plays a central role in the lending discussion.
- Match your goal, such as accessing equity, consolidating debt, or addressing foreclosure, with the relevant financing option.
- Prepare property details, ownership and lien information, debts, and a clear repayment outline to make your financing discussion more productive.
- AHL HardMoney offers Citrus County programs including cash-out refinance and foreclosure refinance.
Citrus County Hard Money Lenders: What Borrowers Are Comparing
Searching for Citrus County hard money lenders often starts with a practical question: can the equity in your property help meet a financing need that a standard mortgage process may not address? Hard money loans are secured by real estate, so the property is central to the lender’s assessment. The loan’s purpose and your plan to repay it matter as well.
Asset-based underwriting puts significant weight on property value and available equity. That doesn’t mean credit or income never matters. Conventional mortgage processes typically give close attention to credit, income, and the borrower’s ability to make payments over time. For an overview of this financing category, see What is a Hard Money Loan?
For a visual overview, watch this video about the hard money loan process:
How hard money loans differ from traditional mortgages
A lender may consider the property’s location, type, condition, estimated value, and existing liens, along with the amount requested and the reason for borrowing. These details help show how much equity may support the financing and whether the request fits the asset. Credit and other financial details may also be relevant, with their weight varying by lender and loan.
Traditional mortgages generally follow a more standardized review of the borrower’s finances and repayment capacity. Hard money terms and qualification criteria differ, so an asset-based approach is not automatic approval or a single set of terms. A request for funds tied to a defined property-related goal may be assessed differently from a request to refinance an existing loan.
Why Citrus County borrowers search locally
A local search connects the financing question to the property itself. A home in Inverness, a property in Crystal River, a residence in Homosassa, or land in Citrus Springs may each have different details for a lender to assess. The address and property characteristics help frame the discussion, while the purpose clarifies what the funds need to accomplish.
Equity access, refinancing, debt consolidation, and foreclosure-related financing are distinct goals, even when the same property is involved. If you’re exploring home equity loans, be ready to explain how you intend to use the funds and how you expect to repay the loan. AHL HardMoney serves Citrus County borrowers. Its local lending work is based on the property, the request, and the borrower’s circumstances.
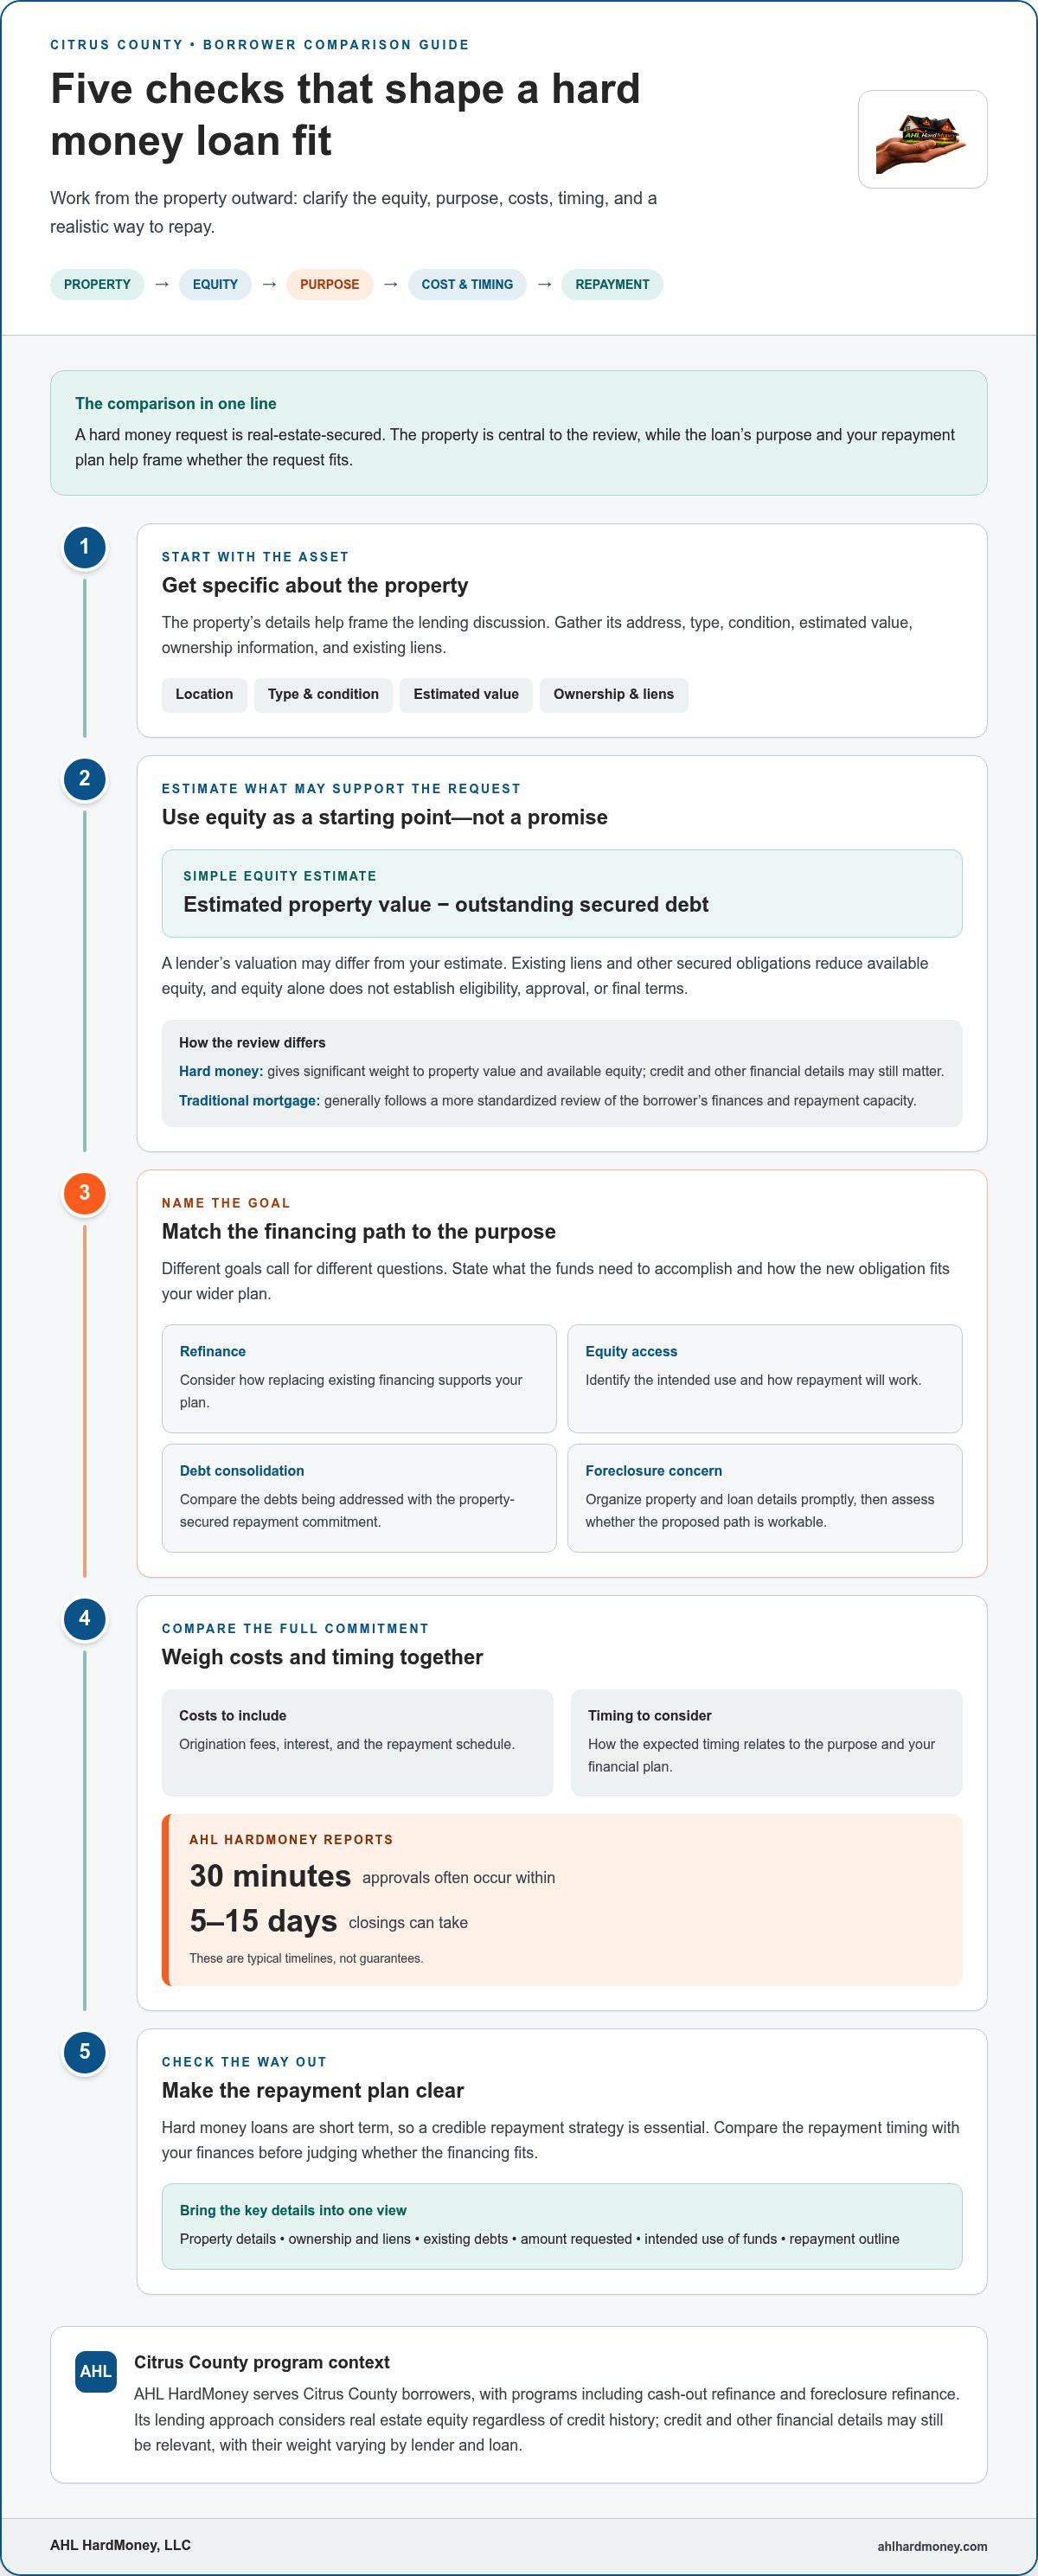
Use four anchors to judge fit: the property, available equity, financing purpose, and repayment plan. To compare total costs, include the loan’s origination fees and interest alongside its repayment schedule. If any of these details are unclear, clarify them before comparing options. That gives you a more useful basis for deciding whether an asset-based loan suits your situation.
How Equity, Loan Purpose, and Timing Shape Lender Fit
Equity is a starting point, not a loan promise. A useful comparison connects the property’s estimated value and secured debt to the amount requested, the reason for borrowing, and a realistic way to repay. That gives Citrus County hard money lenders a clearer picture of the request and helps you judge whether the financing path fits your plans.
What property equity can and cannot tell you
A simple estimate of equity is the property’s estimated value minus outstanding secured debt. For example, a property’s estimated value may leave a substantial difference after you subtract its mortgage balance. That rough calculation doesn’t establish how much financing may be available. A lender’s valuation may differ from your estimate, and existing liens or other secured obligations reduce the equity available to support a loan.
The amount you’re requesting matters, too. Funding a specific expense creates a different need from replacing an existing loan. Property condition and other details can also shape the review. Equity alone can’t establish eligibility, final terms, or approval. The FDIC’s Real Estate Lending Standards offer broader context on real estate lending standards, but they don’t determine the terms of every private loan.
Equity-based lender fit means aligning the property’s usable equity with your specific purpose and a credible plan to repay.
Match the financing purpose to the loan path
Start by identifying what the funds need to accomplish. This helps distinguish financing paths that may sound similar but serve different goals. If you want to access property equity, explore a cash-out refinance or home equity financing. Relevant details include existing loan balances, the amount you’re seeking, and how repayment will work.
Debt consolidation has a different focus: using property-secured financing to address existing debts. Foreclosure-related financing is different again. If foreclosure is a concern, move promptly, but don’t let speed replace a careful review of the property, obligations, loan terms, and repayment plan. A fast decision is useful only if the proposed path is workable.
- Refinance: Consider how replacing existing financing supports your broader plan.
- Equity access: Identify the intended use of the funds and how the new obligation fits your budget.
- Debt consolidation: Compare the debts being addressed with the repayment commitment tied to the property.
- Foreclosure concerns: Organize relevant property and loan details promptly, then assess whether the proposed financing offers a realistic way forward.
Compare timing alongside eligibility, costs, and repayment, not in isolation. AHL HardMoney serves Citrus County and considers real estate equity in its lending approach, including for borrowers with credit-history challenges. To learn more about the company, visit AHL HardMoney.
Compare Citrus County Hard Money Lenders With a Clear Framework
A directory can help you find lender names, but it won’t tell you whether a particular loan fits your property or repayment plan. Compare the role each option plays, what it says about underwriting, and whether timing is presented as an estimate or a commitment. The table distinguishes general lender categories from AHL’s stated approach without ranking providers on claims that aren’t supported by comparable evidence.
| Option | Role and underwriting focus | Purpose, timing, and repayment |
|---|---|---|
| Mortgage brokerage | Connects borrowers with mortgage options; underwriting depends on the lender and program. | Often associated with standard mortgage needs. Review the specific loan’s process and repayment terms. |
| Private-money lender | May assess real estate equity and property details as part of its decision. | Purpose, timing, and repayment structure vary by lender and request. Don’t assume a quick process or approval. |
| Directory platform | Lists lenders or loan categories; a listing itself isn’t an underwriting review. | Use it to identify options, not as evidence of eligibility, terms, or closing speed. |
| AHL HardMoney | A Tampa-headquartered Florida lender serving Citrus County. AHL says its approach considers real estate equity regardless of credit history. | AHL reports approvals often within 30 minutes and closings in 5 to 15 days. These are typical company-stated timelines, not guarantees; repayment depends on the loan terms. |
These categories aren’t interchangeable. A mortgage brokerage, private-money lender, and directory platform serve different roles, so compare like with like. A directory entry doesn’t show how a lender will evaluate your property, and a speed claim without context doesn’t establish when your loan could close. A meaningful comparison considers the specific request, costs, terms, and repayment plan.
Questions that reveal whether a lender fits your situation
Before discussing financing with AHL, organize the basics: property address and type, ownership, estimated value, existing liens, amount requested, and intended use. Ask what the equity review considers and what information will help evaluate the request. A focused overview connects the property to your financing goal.
- Does the property and intended use fit the loan being discussed?
- How are value, existing liens, and available equity evaluated?
- What information is needed to review the request?
- What is the expected repayment timing, and what do the loan terms say about extensions?
- What repayment or exit route is realistic if the original plan changes?
Keep the repayment questions front and center. A projected timeline is only one part of the decision. Understand the repayment obligation and possible next steps before relying on a short-term loan. AHL’s reported timing is not a promise of approval or closing by a particular date.
Compare each option’s role with the financing purpose and repayment plan you’ve identified. That turns a list of Citrus County hard money lenders into a practical comparison, without mistaking a directory listing or headline claim for a lending decision.
Prepare for a Citrus County Hard Money Loan Decision
A productive financing discussion starts with a clear picture of what you need, what property supports the request, and how you expect to repay. Preparing these details helps you explain your situation without treating a general document list as a universal requirement. The review depends on the property, the loan purpose, and your circumstances.
Use this sequence to get organized:
- Define the purpose. State what the funds are intended to address, such as refinancing, accessing equity, or consolidating debt.
- Gather property details. Note the address, property type, ownership, and what you know about its value or condition.
- Organize current obligations. Summarize mortgage balances and other liens secured by the property, along with debts relevant to your request.
- Outline repayment. Identify the expected source of repayment and when you believe it may be available.
Documents and details to organize before discussing financing
Having information at hand can make it easier to describe your request, but the items needed may vary. Consider gathering ownership details, a recent mortgage statement, available lien information, and property records or valuation documents. If income or other financial information relates to your circumstances, prepare a concise summary. Write down your desired timing and why that date matters.
Be direct about what’s known and what’s an estimate. For example, distinguish a documented mortgage balance from an approximate property value. If you’re considering a debt consolidation hard money loan, organize the debts involved and explain what you want consolidation to accomplish. This keeps the discussion tied to the actual purpose rather than a general request for funds.
Plan repayment before choosing a short-term loan
Define an exit plan before accepting the obligations of a short-term loan. Possible repayment routes might include refinancing, selling the property, or using another source of funds, but each depends on future circumstances and isn’t guaranteed. Consider what could delay your plan, which payments or obligations come due, and what you would do if your expected repayment source isn’t available on time.
Urgency can be real, particularly when a deadline or foreclosure concern is involved. Move promptly, but take time to understand the proposed terms, repayment schedule, and consequences of not repaying as planned. AHL reports that approvals often occur within 30 minutes and loans can close in 5 to 15 days. These are typical company-stated timelines, not promises for an individual request. Speed is useful only when the financing and repayment plan make sense together.
With property, ownership, lien, income, purpose, and repayment details organized, you’ll be better prepared to discuss a Citrus County financing request and assess whether the proposed path is workable.
Explore AHL HardMoney Financing for Citrus County Properties
AHL HardMoney, LLC is headquartered in Tampa and serves Citrus County borrowers as part of its Florida hard money lending work. Its financing options include cash-out refinance, home equity loans, foreclosure refinance, and debt consolidation. The right path depends on the property, the purpose of the request, and a repayment plan that fits your circumstances.
AHL serves borrowers across Florida, including in Tampa, Clearwater, Saint Petersburg, Palmetto, Largo, Newport Richey, Port Richey, Brooksville, Brandon, Orlando, Daytona, Napels, Ocala, Deltona, Deland, Jupiter, Palm Beach, Lakeland, and Boca Raton. Its equity-focused approach can be relevant when a financing need doesn’t fit standard bank criteria. AHL considers real estate equity regardless of credit history, but that doesn’t mean credit is automatically irrelevant or that equity guarantees approval. The property and the full request still matter.
When AHL’s equity-focused approach may be relevant
Consider AHL financing when you have real estate equity and a specific goal, such as accessing funds, addressing existing debt, or refinancing a property. A foreclosure concern calls for prompt, careful attention to the property, current obligations, and repayment plan. AHL offers foreclosure refinance loans for this purpose. Any financing request is subject to review.
What to bring to an initial financing conversation
A concise overview helps keep the discussion practical. Note the property’s Citrus County location and type, who owns it, any existing mortgage or liens, the purpose of the requested funds, and your expected repayment route. If timing matters, explain the relevant deadline and why. Property, ownership, debt, or income information can help describe your situation; the details needed depend on the request.
Before moving forward, make sure you understand the proposed repayment obligations and what your plan depends on. Refinancing or selling may be possible repayment routes in some situations, but neither is assured. Consider what you would do if your expected source of funds takes longer than planned. A short-term loan should fit both the immediate need and a realistic way to repay it.
AHL reports that approvals often occur within 30 minutes and loans can close in 5 to 15 days. Those are typical company-stated timelines, not guarantees; an individual request may take a different course. Speed can matter when the need is time-sensitive, but it shouldn’t replace a careful review of the loan’s terms and your repayment plan.
For borrowers comparing Citrus County hard money lenders, bring the property details, financing purpose, and repayment outline together for a focused discussion. This gives the conversation a practical starting point and helps you understand how the request may be assessed.
Move Forward With a Plan That Feels Workable
The most useful comparison of Citrus County hard money lenders leaves you with a decision you can explain: what the financing should accomplish, what repayment depends on, and which trade-offs you’re prepared to accept. Before moving ahead, write down one outcome that would make the loan worthwhile and one condition that would cause you to pause. This can help keep urgency from crowding out good judgment.
A financing conversation doesn’t commit you to borrowing. It gives you a chance to describe the property, intended use, and repayment expectations, then understand how those pieces may fit together. Bring your priorities and open questions. Use the discussion to identify a practical next step, whether that means refining your plan or pursuing a request.
Move forward with a plan that protects both your immediate goal and your longer-term stability. To discuss your Citrus County property, financing purpose, and repayment plan, contact AHL HardMoney.
Frequently Asked Questions
What is a hard money loan in Citrus County, Florida?
A hard money loan in Citrus County is financing secured by real estate, so the property backs the borrowing. Unlike a conventional mortgage, which commonly centers on the borrower’s income, credit profile, and long-term payment capacity, asset-based lending gives substantial attention to property value and equity. For example, a refinance request is assessed based on its details and purpose. Terms and eligibility depend on lender review, property, equity, and intended use.
Can I get a hard money loan in Citrus County with poor credit?
Possibly. Asset-based lenders may give property equity and loan purpose more weight than a conventional lender would, but that doesn’t mean credit history is ignored. AHL considers real estate equity regardless of credit history; each request still requires review, and approval isn’t assured. If a past credit setback is part of your concern, summarize the property, existing secured debt, intended use, and a practical repayment route.
How quickly can a hard money loan close in Citrus County?
AHL HardMoney reports that loans can close in 5 to 15 days and approvals often occur within 30 minutes. These are company-stated timelines, not guarantees or a promise for a particular Citrus County transaction. The actual schedule can depend on the application, property review, document readiness, and other transaction circumstances. If your need has a deadline, share it early and allow time for review.
What do Citrus County hard money lenders consider when reviewing a property?
Citrus County hard money lenders may consider estimated property value, existing liens, available equity, loan purpose, and repayment plan. A property with substantial debt secured against it may support a different request from one with fewer obligations. Criteria vary by lender and loan. An estimated value alone doesn’t establish eligibility or determine a specific borrowing amount, so treat online estimates as a starting point, not a lending decision.
Can I use a hard money loan to stop foreclosure in Citrus County?
Foreclosure-related refinancing may be an option to explore, but financing isn’t automatic and can depend on the property, available equity, timing, and review of the request. AHL offers foreclosure refinance loans. If foreclosure is a concern, act promptly and gather relevant property and loan information for a financing discussion. No lender can promise that a loan will be approved or that a home will be saved; consider the repayment obligations carefully.
Is a hard money loan the same as a home equity loan?
No. Both may involve borrowing against real estate equity, but their structures, underwriting, terms, and intended uses can differ. The name of a loan alone doesn’t establish how a request will be assessed or what repayment obligations apply. AHL offers both home equity loans and hard money financing. Which path may fit depends on the property, your financial circumstances, the purpose of the funds, and the terms offered after review.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


