
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
What if your property’s equity and a realistic repayment plan matter more than a less-than-perfect credit history? For borrowers facing debt pressure, urgent repairs, or foreclosure risk, understanding how Manatee County hard money lenders assess a loan can make the next step clearer.
It’s reasonable to ask whether credit history will affect your options, how much equity may support financing, and when repayment will come due. Hard-money lending is asset-based, but approval isn’t automatic. Lenders may also consider the property, existing secured debt, loan purpose, and repayment plan. A clear exit strategy matters, especially when the loan is short-term.
This guide explains how property-backed loans are evaluated, what information to prepare, and how to weigh terms and repayment expectations. It also connects common goals, such as consolidating debt, funding home improvements, or refinancing an existing loan, with possible financing options. With a clearer view of your equity, timeline, and repayment path, you can approach the lending conversation with more confidence.
Key Takeaways
- Estimate usable property equity by considering the property’s value alongside mortgages, liens, and other debts secured against it.
- Compare Manatee County hard money lenders by how the terms, timing, and repayment structure fit your situation.
- Define your loan purpose and a realistic repayment route before moving forward, especially for short-term financing.
- Prepare property details and relevant financial documents to make the lending discussion more focused.
- Consider whether cash-out refinance, home equity, or foreclosure refinance aligns with your next financial step.
What Manatee County Hard Money Lenders Do, and When Borrowers Consider Them
Property owners sometimes need financing that takes real estate and available equity into account, especially when a deadline or complicated financial situation makes conventional financing a poor fit. Manatee County hard money lenders provide short-term, property-secured financing. The real estate serves as collateral, and the borrower remains responsible for the loan’s repayment obligations.
This option may be relevant to a Palmetto homeowner seeking funds for a major repair or a property owner working through a time-sensitive transaction. But collateral doesn’t bypass review. Lenders assess the property and proposed loan, and borrowers need to understand the terms and have a plan to repay the debt.
For an overview of common features and uses, explore this hard money loan definition and watch the video below.
How a hard-money loan differs from a conventional mortgage
Conventional mortgage underwriting generally gives substantial attention to income, credit, debts, and the borrower’s ability to make scheduled payments. Asset-based lending places greater emphasis on the property’s value and equity, while still considering the borrower’s circumstances and repayment plan. Credit history may not be the sole basis for a decision, but that doesn’t mean a lender skips review or that every property qualifies.
Terms matter. A hard-money loan is generally intended for a shorter period than a long-term mortgage. Understand the payment schedule, any final balance due, and how you expect to repay or refinance. The property serves as collateral, but that doesn’t remove your obligation to repay. If your plan depends on selling or refinancing, consider what you’ll do if the process takes longer than expected.
When Manatee County property owners may explore this option
A borrower might explore property-backed financing to refinance existing debt, address a pressing tax or foreclosure concern, or fund improvements that make a home or investment property usable. For example, a homeowner may need to repair a property before listing it, while an investor may have a defined timeline to complete work and pursue a sale or refinance. Home improvement financing may be relevant to eligible project goals.
Whether a loan fits depends on the property, its equity after secured debts, the intended use of funds, and a credible repayment path. Before weighing options, map the deadline, project costs, and likely repayment source. A shorter timeline can be useful, but it can also leave less room for delays. Start with a clear purpose and a plan that still makes sense if the initial timeline shifts.
How Manatee County Hard Money Lenders Assess Property Equity
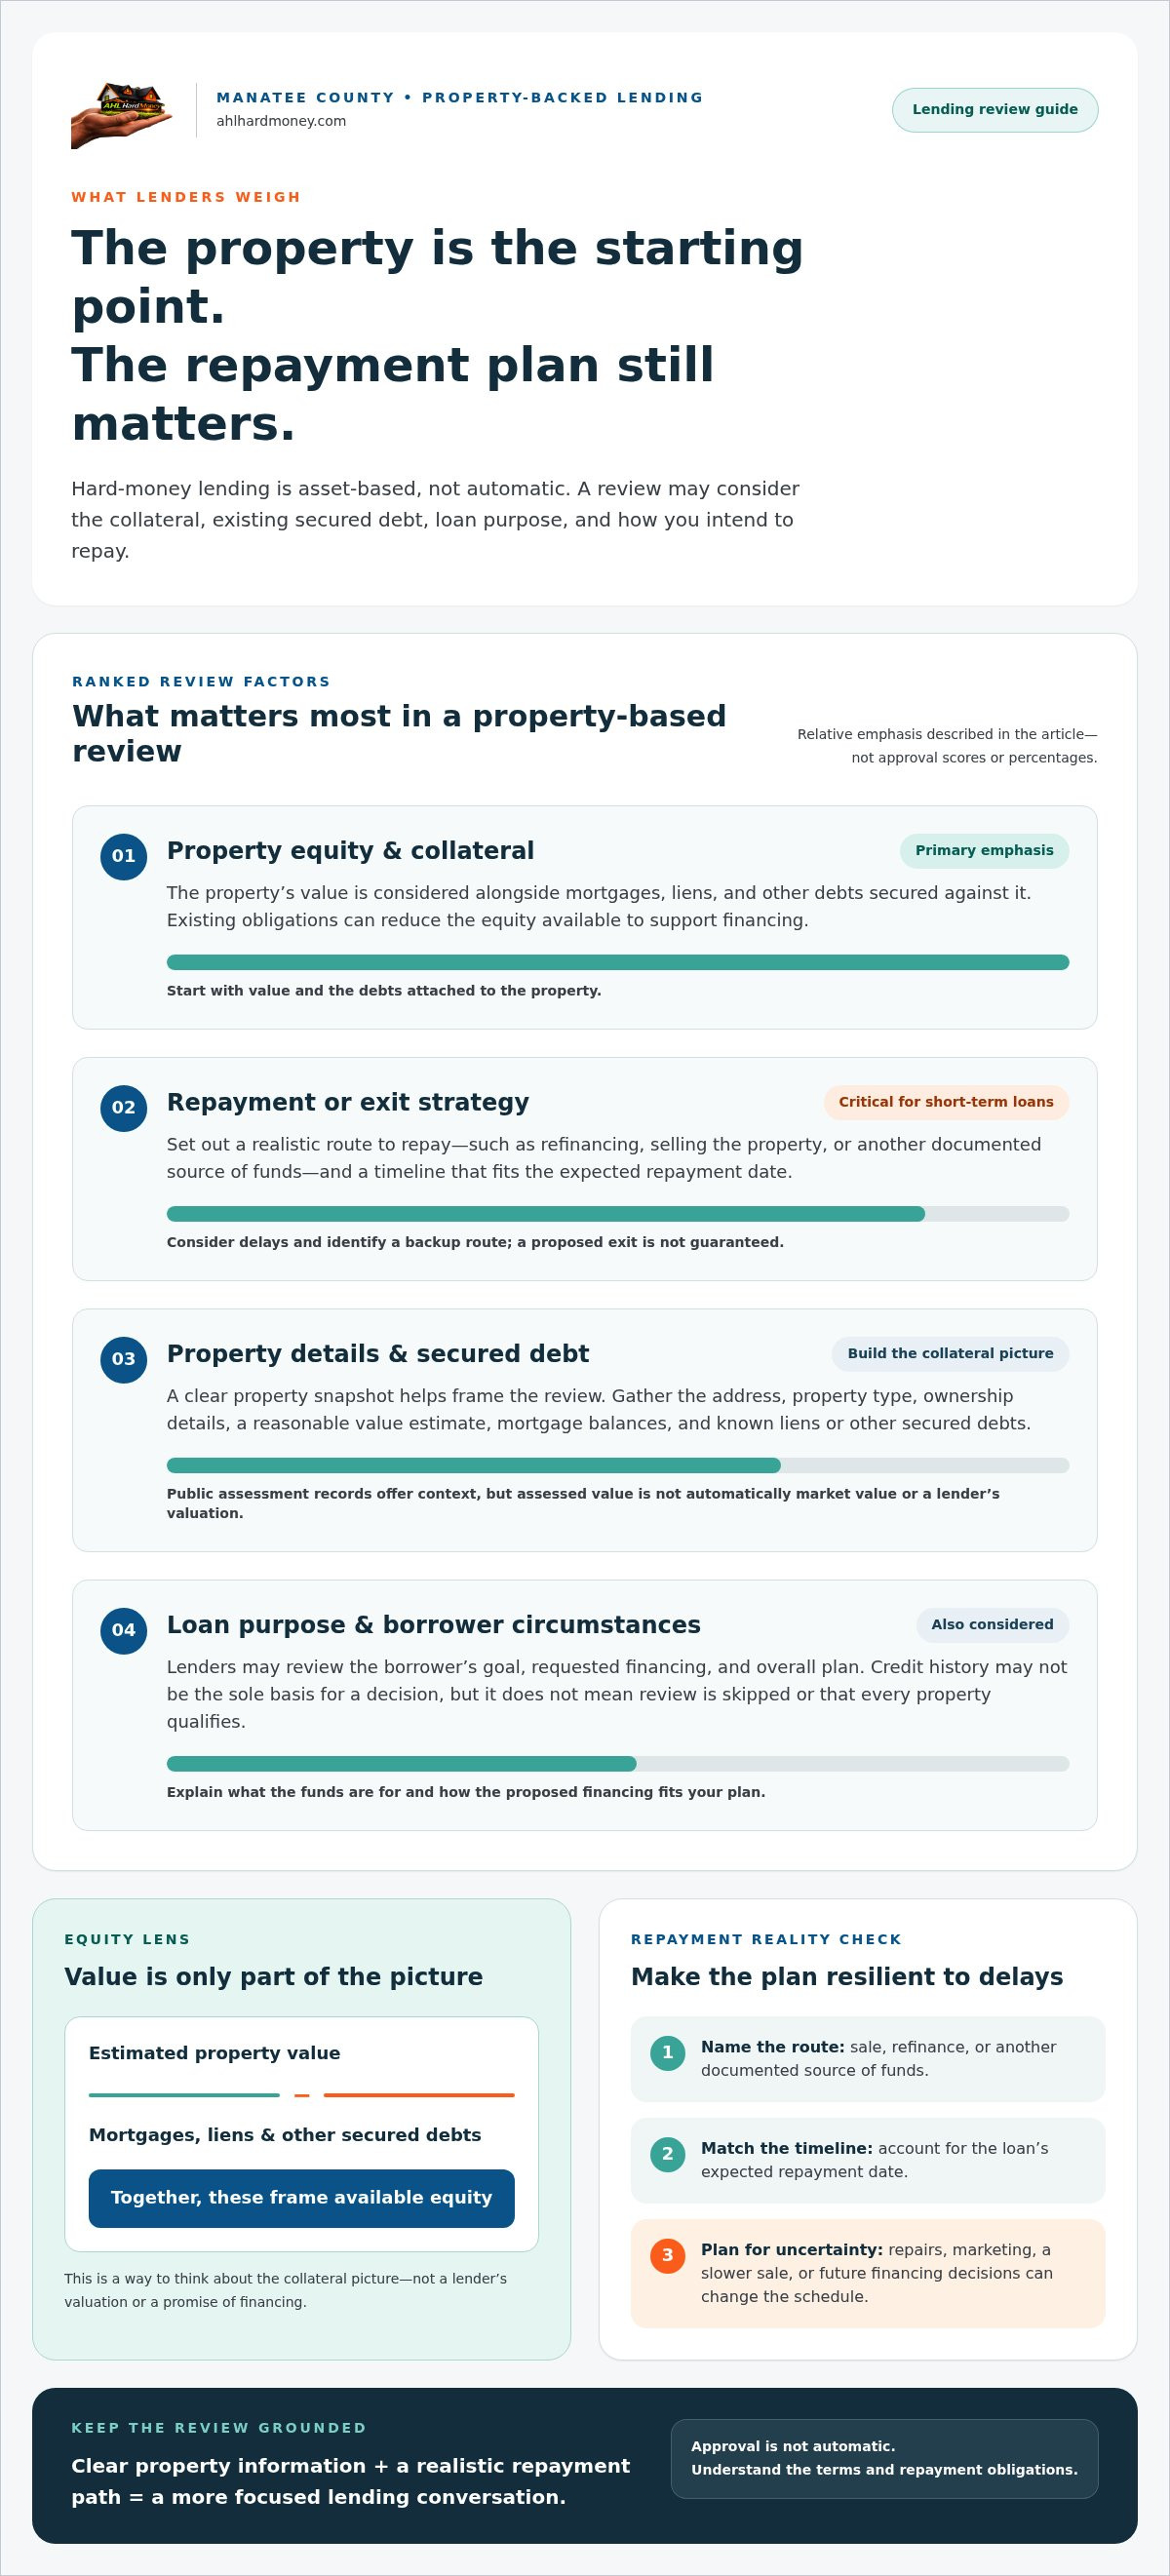
Equity isn’t simply a property’s estimated value. It must be considered alongside mortgages, liens, and other debts secured against the property. A home may appear valuable on paper, but a substantial mortgage or recorded lien can reduce the equity available to support additional financing. Manatee County hard money lenders may weigh this collateral picture heavily, while also reviewing the borrower’s goal and repayment plan.
AHL HardMoney’s lending approach focuses on property equity, and credit history isn’t the sole basis for its lending decisions. That doesn’t mean credit is irrelevant or approval is automatic. The property, existing obligations, requested financing, and borrower’s overall plan still matter. The Consumer Financial Protection Bureau (CFPB) provides general information about consumer financial topics that can help borrowers understand lending documents and obligations.
What property details help frame a lending review?
Gather a clear snapshot of the property and its current financial position. Useful details include:
- The property’s street address and type, such as a primary residence or investment property.
- Ownership details, including who holds title.
- A reasonable estimate of current value and the information behind it.
- Balances for existing mortgages, plus any known liens or other debts secured by the property.
Manatee County Property Appraiser records can provide local context, including public assessment information. An assessed value isn’t automatically the same as current market value or a lender’s valuation. Use public records as a starting point, not a promise of how a property will be valued in a lending review. If figures differ, note the source and date of each estimate.
Why the repayment or exit plan matters
An exit strategy is the planned route for repaying a short-term loan, such as refinancing, selling the property, or using another documented source of funds. The plan should include a realistic timeline that fits the loan’s expected repayment date. If you plan to sell, consider how repairs, marketing, or a slower-than-expected transaction could affect the schedule. If refinancing is the plan, consider what would need to be in place to pursue it.
A proposed exit isn’t a guaranteed future outcome. Property values, sale timing, and future financing decisions can change, so identify a backup route rather than relying on best-case assumptions. For Manatee County borrowers, presenting property information alongside a repayment plan shows both what may support the financing and how the debt is intended to be repaid. Borrowers exploring a property-based option can review AHL’s home equity loan information alongside their own figures.
Comparing Hard Money Lenders in Manatee County: Terms, Timing, and Trade-Offs
Compare more than the speed of a decision. The financing structure should fit the property goal, deadline, and realistic repayment route. Rates, fees, duration, and payment structure vary by property and transaction, so a term that works for one Manatee County borrower may not suit another.
Hard-money financing can be useful when timing or circumstances make conventional borrowing difficult, but it may cost more. Weigh that trade-off against the reason for seeking a short-term loan and the consequences if a planned sale, refinance, or other repayment source takes longer than expected. AHL HardMoney can close loans in 5 to 15 days, depending on the transaction.
Which loan purpose aligns with your Manatee County situation?
Start with the intended use of funds. A cash-out refinance may suit a property owner seeking to access equity while refinancing an existing mortgage. A home equity loan may address another property-backed borrowing need. Owners managing several obligations may consider debt consolidation, while borrowers funding repairs or upgrades may explore home improvement financing. The purpose helps clarify the loan structure and repayment plan.
For example, cash-out refinance financing may be relevant when accessing equity is part of a refinance goal. Debt consolidation financing is a separate option when the aim is to address multiple obligations. Each path depends on the property, requested financing, and repayment plan.
| Purpose | Possible repayment path | Timing to consider | Key question |
|---|---|---|---|
| Cash-out refinance | Refinance or another planned source | Does the deadline match the transaction? | How will existing secured debt be addressed? |
| Home equity | Documented repayment source | Can payments fit the expected term? | How much equity remains after secured debts? |
| Debt consolidation | Planned payments or refinance | Will the schedule support the goal? | What obligations will the funds address? |
| Property improvement | Sale, refinance, or other source | Can work and repayment align? | What if repairs take longer than planned? |
Questions that clarify the real borrowing commitment
Before deciding, compare the written terms, total repayment obligations, and collateral exposure. Understand the payment schedule, when any remaining balance is due, and what the loan documents say may happen after missed payments. Don’t rely on a headline rate or estimated closing date alone. Consider how the complete structure fits your finances.
Then test the exit plan against the deadline. If repayment depends on refinancing, what steps and timing does that require? If it depends on a sale, what happens if the property doesn’t sell on schedule? The useful comparison isn’t simply which option appears fastest. It’s which written commitment you can realistically meet, even if the plan is delayed.
How to Prepare for a Hard Money Loan on a Manatee County Property
A focused loan discussion starts with a clear purpose and a realistic way to repay. Before approaching Manatee County hard money lenders, organize the property facts, existing obligations, and timing behind your request. This preparation shows how the financing connects to your situation and gives you a stronger basis for reviewing proposed terms.
- Define the financing purpose. Write down what the funds will address, such as refinancing, consolidating obligations, improving a property, or managing a time-sensitive debt concern. Be specific about the intended use and amount you’re seeking, and distinguish estimates from confirmed costs. If funds are for repairs, gather a scope of work and available estimates so the project can be discussed clearly.
- Set out a repayment route and timeline. Identify how you expect to repay the loan, whether through a refinance, property sale, or another documented source. Note the steps required and when you expect each to happen. If you expect income or another source to support repayment, organize information that explains it. Consider a backup plan in case a sale, refinance, or project takes longer than expected.
- Gather property and ownership details. Prepare the full property address, ownership information, and a reasonable estimate of current value. Include relevant property details, such as its condition and planned improvements. For an investment property in Palmetto, distinguish its current condition from the improvements you intend to complete. This keeps estimates and project plans grounded in the property’s actual status.
- List existing secured debts and relevant finances. Gather current mortgage information, including balances and payment details, and note any known liens or other debts secured by the property. Organize income or repayment-source information that supports your proposed plan. Keep dates and figures current, and flag anything you’re still working to verify rather than presenting an estimate as final.
- Share information for an initial review, then examine the terms. Provide property and loan-purpose details in an organized form. AHL HardMoney often provides approvals within 30 minutes, though that is not a promise of approval or timing. An initial response isn’t a reason to skip careful review. Read the final written terms, repayment schedule, due dates, and responsibilities before deciding whether to proceed.
Keep a simple digital or printed folder with current documents and a one-page summary of your request. This makes it easier to spot missing information and compare proposed financing with your repayment plan. Don’t let urgency push you past the details: understand the full commitment and how the property may be affected if repayment doesn’t go as planned.
AHL HardMoney for Manatee County Borrowers: Explore a Property-Based Next Step
A property-backed loan should match your goal. AHL HardMoney, LLC provides hard-money financing to property owners in Manatee County and throughout Florida, including cash-out refinance, home equity loans, and foreclosure refinance. The property and its equity are central to the lending review, along with the intended use of funds and repayment plan.
AHL serves borrowers in Manatee County, including Palmetto, and communities across Florida such as Tampa, Clearwater, Saint Petersburg, Largo, Newport Richey, Port Richey, Brooksville, Brandon, Orlando, Daytona, Naples, Ocala, Deltona, Deland, Jupiter, Palm Beach, Lakeland, and Boca Raton.
Timing can also factor into the decision. AHL HardMoney can close loans in 5 to 15 days, depending on the transaction. Prepare for a review, and make sure the repayment schedule fits your circumstances before moving forward.
AHL loan paths for common property-financing needs
If you want to access eligible equity while refinancing an existing mortgage, cash-out refinance may be a potential route. A home equity loan may suit a different property-backed borrowing goal. AHL offers home equity loans that can be considered alongside property value, existing secured debt, planned use of funds, and repayment approach.
Foreclosure concerns call for prompt, clear information about the property and current obligations. A foreclosure refinance may be relevant for a property owner exploring whether refinancing could address the situation. AHL offers Florida foreclosure refinance loans; eligibility and terms depend on the individual situation, and financing isn’t assured.
Whichever path you’re considering, connect the loan purpose to a repayment route. Equity may support a request, but it doesn’t by itself establish that a particular loan is suitable. Think through how you expect to meet payments and repay the balance, and account for potential delays if your plan depends on a sale or refinance.
Take the next step with your Manatee County property details
To make an initial financing discussion more focused, organize a concise summary of:
- The property address, ownership details, condition, and estimated value.
- Current mortgage balances and any known liens or other debts secured by the property.
- Your funding purpose and the amount you’re seeking.
- Your proposed repayment source and the timing you’re working toward.
Clear, current information gives the review a practical starting point and helps identify questions about terms, repayment responsibilities, and what happens if the expected exit takes longer than planned. Bring estimates as estimates, and distinguish documented facts from assumptions. The goal is a financing discussion grounded in your property and plans, not a promise of approval.
Share your Manatee County property details and financing goal with AHL HardMoney to explore a property-based next step.
Make Your Next Property Decision With Clarity
A financing decision should support the next chapter you’re working toward, not create uncertainty about what comes after closing. Test your plan against realistic timing: What needs to happen first? What could cause a delay? What’s your alternative if repayment takes longer than expected? Clear answers can help you weigh whether a short-term, property-backed loan fits your circumstances.
As you consider Manatee County hard money lenders, focus on the written commitment, the role your property plays, and a repayment route you can explain clearly. You don’t need every detail settled to begin a conversation, but property information and a defined financing goal help make the discussion more focused.
AHL HardMoney works with Florida property owners, including borrowers in Manatee County, on property-backed financing. Review the final terms carefully and consider your ability to meet them before making a financing decision.
With a clear purpose and thoughtful repayment plan, you can move ahead with a better understanding of your options.
Frequently Asked Questions
Are hard money loans available for properties in Manatee County?
Yes. AHL HardMoney, LLC provides property-backed financing to borrowers in Manatee County. Each property and request is reviewed, so not every property or loan request will qualify. Be ready to share the address, ownership details, how the property is used, and your financing goal. These details help frame whether the property and proposed loan are a practical fit for review.
Can I qualify for a Manatee County hard money loan with poor credit?
Poor credit doesn’t automatically rule out a property-backed loan because credit history isn’t the sole basis of AHL’s lending approach. The property and overall request matter too. Explain major credit issues accurately and prepare a realistic repayment plan. The lender reviews the full situation, so no credit profile or property detail by itself guarantees approval.
How do hard money lenders calculate property equity?
Lenders generally consider a property’s value in relation to the mortgages and other secured debts attached to it. Missing lien or payoff information can change the equity picture. Gather current mortgage statements and details about known liens, then distinguish estimated value from a formal valuation. For a Manatee County property, public assessment records can offer context, but they don’t establish the lender’s valuation.
How quickly can a hard money loan close in Manatee County?
Closing timelines vary by property and transaction. Timing can depend on how quickly property and ownership details are reviewed, whether mortgage payoff information is available, and how promptly requested documents are supplied. Explain any time-sensitive need at the outset, but avoid making commitments based on an estimated date. Review the proposed timeline alongside the loan’s written conditions before relying on it.
What can I use a Manatee County hard money loan for?
Depending on the loan and property review, possible purposes include cash-out refinancing, home equity borrowing, debt consolidation, home improvements, tax obligations, or foreclosure refinancing. An owner planning necessary repairs may explore financing tied to the property, while another borrower may seek to address multiple debts. Explain how you intend to use the funds and repay the loan; the approved purpose and terms govern their use.
What happens if I cannot repay a hard money loan on time?
If repayment may be late, contact the lender before the due date and review the loan documents for the payment schedule and stated consequences. Depending on the agreement, missed payments may lead to additional obligations or action involving the property securing the debt. Don’t assume an extension or refinance will be available. Share the situation promptly, understand any proposed change in writing, and consider independent financial or legal guidance.
Is a hard money loan the same as a home equity loan?
Not exactly. A home equity loan describes borrowing based on equity in a property, while “hard money” generally describes property-backed financing evaluated with significant attention to the collateral. The terms can overlap: AHL offers home equity loans as part of its property-backed financing options. Compare the specific loan’s purpose, payment structure, duration, and repayment obligations rather than relying on the label alone.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


