
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
Could the equity in your Hernando County property matter more than a credit setback when you need financing? For borrowers exploring Hernando County hard money lenders, the answer often starts with the property and the purpose of the loan. You may be weighing whether your equity could support a request, how past credit issues affect the conversation, or whether refinancing fits your goal.
This guide explains how hard-money lending works and what a lender may consider when reviewing property equity and a financing request. You’ll learn how cash-out refinancing, private-money refinancing, and other property-backed options differ, what details to prepare, and what to expect from the general process.
AHL HardMoney, LLC serves Hernando County through an asset-based approach to financing. The company is headquartered in Tampa and serves borrowers in communities including Brooksville, Tampa, Clearwater, Saint Petersburg, Palmetto, Largo, Newport Richey, Port Richey, Brandon, Orlando, Daytona, Naples, Ocala, Deltona, DeLand, Jupiter, Palm Beach, Lakeland, and Boca Raton. A useful first step is to connect your property, its equity, and your intended use of funds.
Key Takeaways
- Hard-money financing is secured by real estate. Equity, existing liens, loan purpose, and a workable repayment plan shape the review.
- Cash-out refinancing and home equity financing serve different goals, so describe what you want the funds to accomplish before comparing pathways.
- Conventional financing, hard money, and delaying or restructuring a project have different trade-offs in documentation, timing, and repayment.
- Prepare for a conversation with Hernando County hard money lenders by defining your goal, gathering property details, listing liens, and mapping repayment.
- AHL reports approvals often within 30 minutes and closings in 5 to 15 days, depending on the transaction. These are possible timeframes, not guarantees.
Hernando County hard money lenders: what asset-based financing means
Hard money is financing secured by real estate, with the property’s equity playing a substantial role in the review. Rather than relying on a borrower’s credit profile alone, an asset-based review considers the property, existing debt, the requested loan purpose, and a practical repayment plan. This approach may be relevant to property owners in Brooksville, Spring Hill, and other Hernando County communities whose financing needs don’t fit conventional bank criteria.
The term hard money loan describes financing secured by real estate, but the label alone doesn’t determine whether a particular transaction fits. The property, existing obligations, and borrower’s plan all matter.
How property equity relates to a hard-money loan
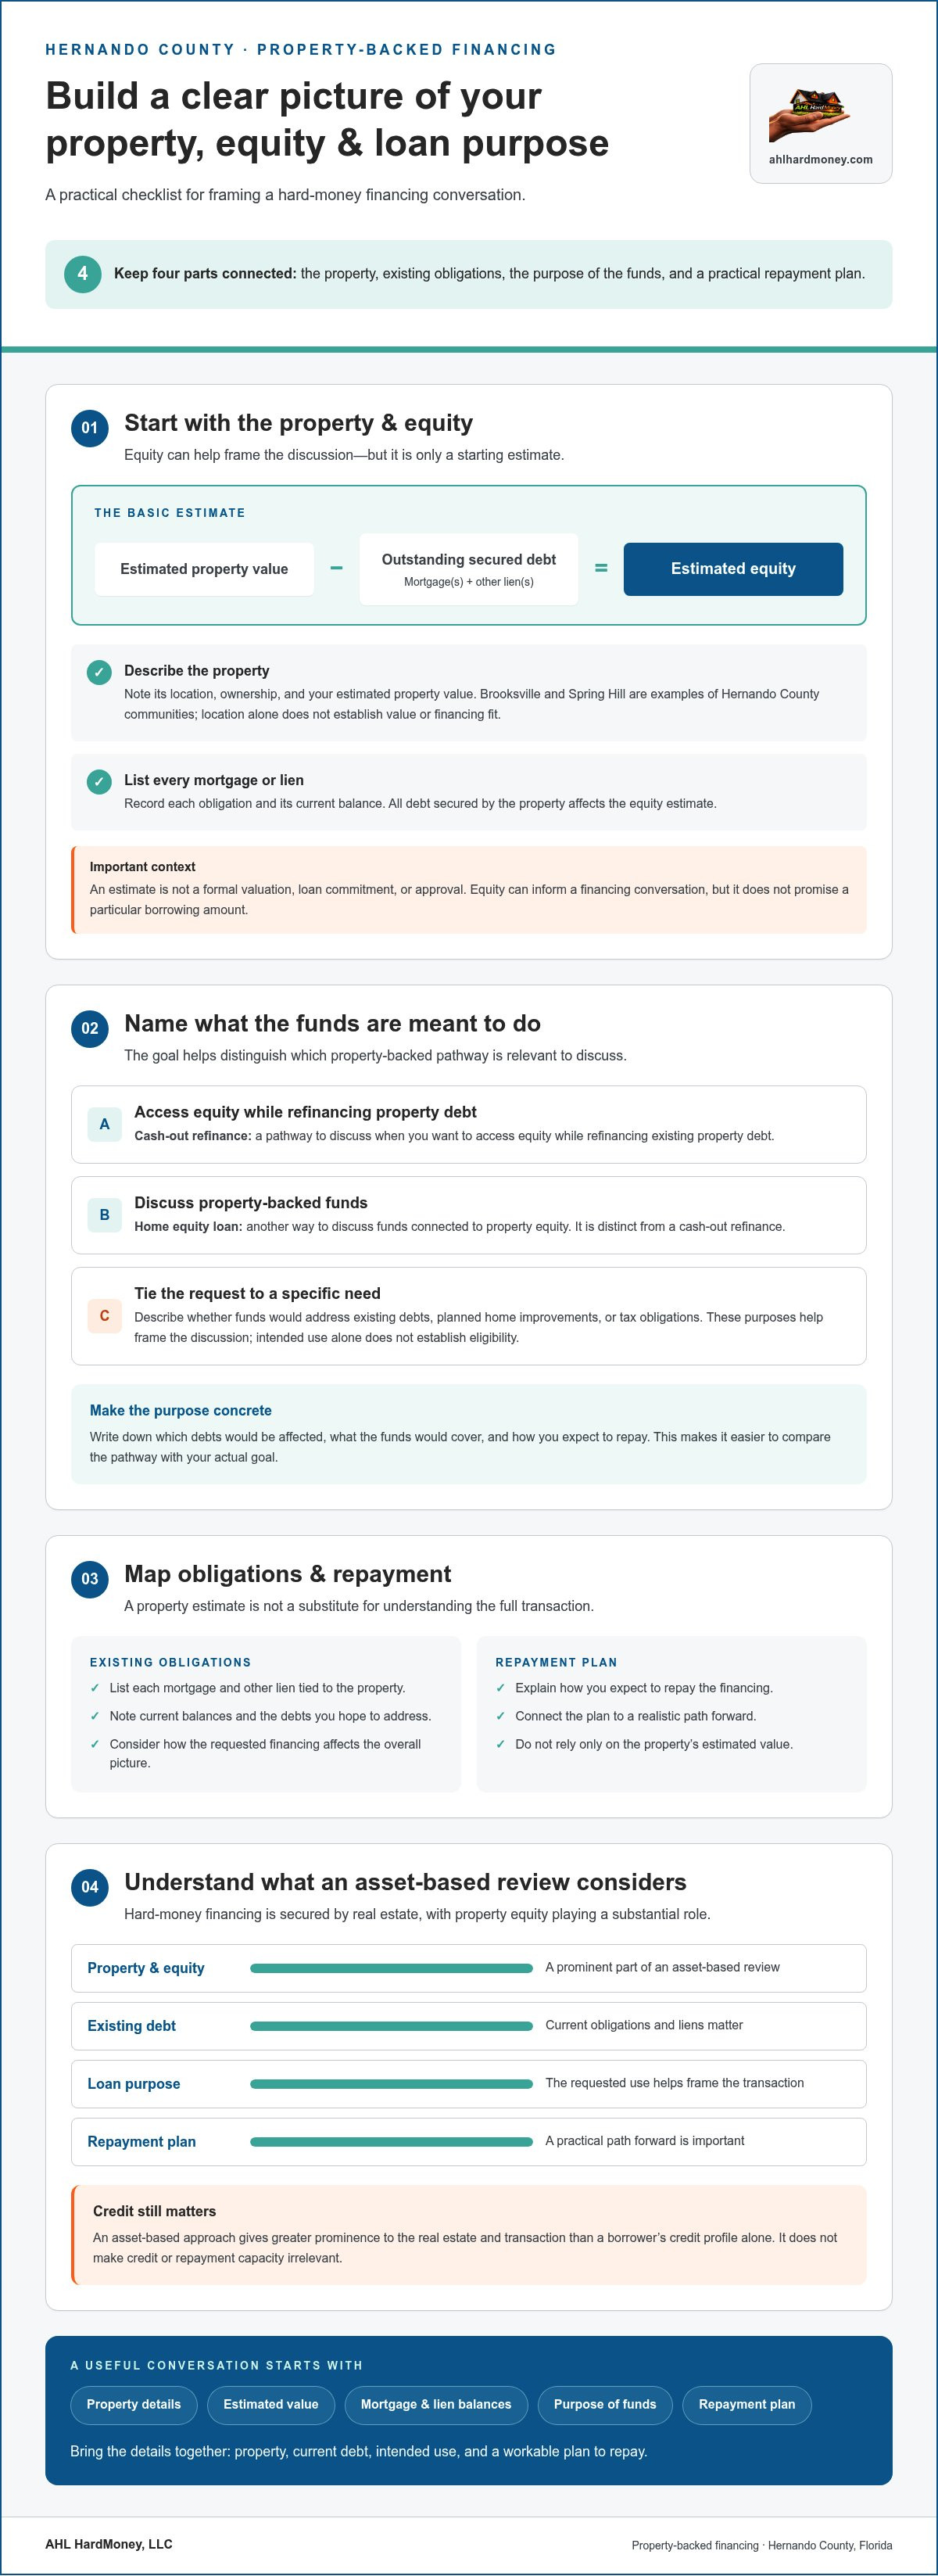
Equity is the estimated property value minus the outstanding debt secured by the property. If an owner has a mortgage and another lien, both obligations affect the calculation. An estimate can help frame a financing conversation, but it is not a formal valuation, loan commitment, or approval.
Existing liens matter because they represent claims against the property. A financing request may need to account for those obligations, the property’s assessed value, and the borrower’s intended use of funds. In practical terms, a rough estimate of market value is only a starting point. To understand the equity picture, list each mortgage or lien and its current balance, then compare the total with your estimated property value.
For homeowners exploring an equity-based path, AHL offers home equity loans. The property details and the intended use of funds help shape the review. Equity can inform the conversation, but it doesn’t promise that a particular amount can be borrowed.
How hard money differs from traditional bank financing
Traditional bank financing generally involves broader underwriting, which may weigh factors such as income, credit history, existing obligations, and property details. In an asset-based review, real-estate equity and the transaction take a more prominent role. That distinction can make it possible to discuss financing when credit history or other financial circumstances make conventional options challenging. It does not make credit or repayment capacity irrelevant.
Alternative financing still requires a clear view of the full transaction. Be prepared to explain the property, existing liens, the purpose of the requested funds, and how you expect to repay. A defined repayment plan should connect the financing to a realistic path forward, rather than relying only on the property’s estimated value.
When comparing Hernando County hard money lenders, ask more than, “How much equity might I have?” Consider how the property, current debt, intended use of funds, and repayment plan fit together. That fuller picture gives the discussion a useful starting point.
How Hernando County property and loan purpose shape financing
Start with the goal, not a lender ranking. Two property owners may have similar equity but need different solutions: one may want to access funds through a refinance, while another may need to address debts or planned repairs. The requested use, property details, current liens, and a workable repayment strategy help determine which pathway is relevant to discuss.
Match the financing goal to the relevant loan pathway
If you want to access equity while refinancing existing property debt, a cash-out refinance may fit the purpose. A home equity loan is another way to discuss property-backed funds. These are distinct pathways, and neither guarantees qualification. AHL offers both cash-out refinance financing and home equity loans for borrowers exploring these goals.
Other needs call for a purpose-specific conversation. Debt consolidation may be relevant when you want to address existing debts. Home-improvement financing connects a request to planned work on the property, while tax-related financing may be relevant when you need funds for tax obligations. Describe what the funds would cover instead of treating every request as interchangeable. Intended use helps frame the discussion, but it does not establish eligibility by itself.
Refinancing also differs from borrowing against equity without framing the request as a refinance. To compare these routes, write down which debts would be affected, how much funding you’re seeking, and how you expect to repay. Those specifics make it easier to assess whether a pathway relates to your actual goal.
Why the property details matter in Hernando County
Location identifies the property, but it doesn’t establish its value. A home in Brooksville and one in Spring Hill are both examples of Hernando County properties; neither location alone indicates equity or financing fit. Be ready to describe the property, its ownership, your estimated value, and any loans or other liens tied to it.
Those details connect the property to the requested purpose. If you’re seeking funds for improvements, explain the planned work and how repayment fits your broader plan. If you’re exploring debt consolidation, outline the obligations you hope to address. In either case, the review considers more than location or estimated value. Existing debt and the requested financing affect the full picture.
Before speaking with Hernando County hard money lenders, write down your primary goal and the key facts about the property. A clear explanation helps keep the conversation focused on a financing path that relates to your circumstances. AHL serves Hernando County, and a discussion of the property, existing obligations, and intended use of funds can help identify practical next steps.
Compare hard-money financing with your other Hernando County options
Choosing financing is a trade-off, not a race to the fastest answer. Compare how each path fits your purpose, property, documentation, timing, and repayment plan. Include the option to pause or reshape the project, not just the available ways to borrow.
| Decision factor | Conventional financing | Hard money | Delay or restructure |
|---|---|---|---|
| Financing purpose | May suit goals that fit a lender’s program and underwriting requirements. | May be considered for a property-backed need when equity and transaction details support further review. | Can give you time to reduce the project scope, change its timing, or seek a different funding plan. |
| Property equity | Property is reviewed as part of a broader financing assessment. | Equity and liens are central considerations, but an estimate alone doesn’t establish eligibility. | No new property-secured borrowing is required while you reassess. |
| Documentation | Expect documentation suited to the lender’s review of the borrower and transaction. | Be prepared to explain the property, existing obligations, requested use, and repayment strategy. | Gathering information can help you revise the plan before taking on debt. |
| Timing and repayment | Timing depends on the lender’s process; plan around its requirements and the transaction schedule. | Discuss the expected timeline and a realistic exit plan, such as a future refinance or sale, where appropriate. | May postpone the goal, but can avoid proceeding before repayment is clear. |
When an asset-based loan may deserve consideration
A time-sensitive property need may lead you to consider non-institutional financing, especially if conventional criteria don’t match your circumstances. Credit history can be considered in context, but it does not guarantee approval or make repayment secondary. Before proceeding, understand the payment obligations and how you expect to meet them.
Speed or flexibility isn’t a substitute for affordability. A shorter path to a decision doesn’t make a loan suitable if repayment depends on uncertain future funds. Compare the proposed terms with your budget and the outcome you need.
Questions to resolve before moving forward
Get specific before discussing options with Hernando County hard money lenders. Write down the amount you need and what it would cover. Identify the funds or event you expect to use for repayment, the likely timing, and what you would do if that plan changes. A refinance or sale may form part of an exit strategy, but neither should be treated as certain.
Review costs and written terms in the loan documents before making a decision. AHL offers debt consolidation financing for borrowers exploring that purpose, but the right fit depends on the full transaction. AHL’s asset-based lending fees include origination fees and interest on short-term loans secured by real estate equity. Consider the property, funding purpose, repayment plan, and costs together. To learn more, visit about AHL.
Prepare for a hard-money loan conversation in Hernando County
A focused conversation starts with a clear picture of your property and what you want the financing to accomplish. Before speaking with Hernando County hard money lenders, organize the essentials: your goal, property details, existing obligations, and a realistic repayment approach. You don’t need every answer settled, but knowing what you do know helps identify what still needs discussion.
Information to have ready about the property and loan
Gather the information you have before the conversation. It won’t guarantee approval or replace a full review, but it can help you explain your situation clearly and keep the discussion focused on the property and purpose.
- Define your goal. State what the funds would cover, such as refinancing, consolidating debt, or completing planned improvements. Identify the amount you’re seeking and how you arrived at it.
- Gather property facts. Note the property address, ownership details, property type, and your estimated value. Treat the estimate as a starting point, not a formal valuation.
- List existing obligations. Summarize mortgages and other property-secured debt, including current balances if available. Mention any liens or other claims you know about so they are not overlooked.
- Map repayment. Describe the source you expect to use to repay the financing and your anticipated timing. If your plan depends on a future refinance, sale, or other event, consider what you would do if it takes longer than expected.
Keep relevant property and debt information together, and be ready to explain how the requested funds connect to your goal. Clear details can make an initial review more productive, but they cannot guarantee a particular result.
How to think about timing and repayment
AHL reports that approvals are often completed within 30 minutes and closings may take 5 to 15 days, depending on the transaction. These are possible timeframes, not guarantees. Each request is different, and timing can depend on the transaction details and how ready the information is for review. An organized summary can help keep the conversation moving, but it cannot ensure a specific decision or closing date.
Look beyond speed. Before proceeding, make sure you understand the proposed repayment obligations and can explain how you expect to meet them. Consider whether the expected repayment source is realistic, what could change, and how that might affect your plan. Review the written terms before making a decision. A useful discussion connects the timing, property, and intended use of funds to a repayment path you understand.
A Hernando County hard-money lending next step with AHL
AHL HardMoney, LLC is a privately owned, non-institutional Florida lender headquartered in Tampa and serving borrowers throughout Florida, including Hernando County. For property owners comparing Hernando County hard money lenders, connect the financing goal to the property, its existing obligations, and a repayment plan. That gives the conversation a practical focus without assuming that a loan or outcome is guaranteed.
How AHL’s loan programs relate to common borrower goals
If your goal is to access property equity through refinancing, AHL’s cash-out refinance program may fit the purpose. Your estimated equity doesn’t guarantee available proceeds or approval; the property and full transaction are part of the review. If you’re exploring property-backed funds through a different route, AHL’s home equity loans offer another pathway to discuss.
Other goals call for a purpose-specific conversation. AHL offers private-money refinance for borrowers exploring refinancing outside conventional bank criteria. Its debt consolidation hard-money loans relate to the goal of paying down or combining debts. The right direction depends on what you want to accomplish, the property details, current debt, and how you expect to repay.
What happens when you start a conversation
Be ready to describe the property and its ownership, your financing purpose, existing mortgages or other property-secured obligations, and your repayment plan. You can also explain your timing needs and any factors that may affect the transaction. These details give the discussion a practical starting point. If you’re unsure which financing purpose best describes your situation, begin with the outcome you need and the obligations you want to address.
AHL is identified by NMLS ID 380601. Its team can discuss the property and financing goal with you and consider how the available information relates to potential options. Credit history may be part of the broader picture, but it does not by itself establish whether a transaction will be approved. Understand the terms and repayment responsibilities before moving forward.
You don’t need a perfect script to begin. Bring the property facts you have, explain your goal plainly, and ask questions about the proposed path and written terms. That keeps the next step grounded in your circumstances, not assumptions.
Take the next step with a clear financing goal
Choosing among Hernando County hard money lenders is one part of making a sound financing decision. First, define what a successful outcome would look like. Will the financing address a specific need, and will the plan still make sense if your circumstances or timing change? These questions can help you approach a lender conversation with your priorities in view.
You don’t need every detail settled before you begin. A clear description of your goal, the property involved, and the outcome you’re working toward can open a practical discussion about next steps. Take time to understand any proposed path and decide whether it fits your circumstances. Choose a plan you can explain and feel prepared to manage.
Your property may offer a way to explore financing options. Start with your goal and the details you have, then discuss a potential next step with AHL.
Frequently Asked Questions
Are hard-money lenders available in Hernando County, Florida?
Yes. AHL serves borrowers in Hernando County, including property owners seeking property-secured financing. The phrase “Hernando County hard money lenders” can describe different lenders and loan pathways, so start with the property and your intended use of funds. Property owners in Brooksville and other county communities can discuss their financing goals with AHL.
Can I qualify for a hard-money loan in Hernando County with poor credit?
Poor credit doesn’t automatically rule out a discussion, but it doesn’t guarantee approval either. An asset-based review gives substantial attention to the property and transaction, while credit history may still be considered. Be prepared to explain relevant credit challenges and describe your repayment plan. For example, if a past late payment followed a one-time disruption, explaining the context can help present a fuller picture.
How quickly can a hard-money loan close in Hernando County?
There isn’t one closing schedule for every transaction. Timing can depend on the property review, existing obligations, completeness of the information, and other transaction details. If you have a target date, discuss it before making commitments that depend on funding. Keep a backup plan if a purchase, payoff, or project deadline cannot move.
What property information should I prepare before discussing a loan?
Start with the property address, ownership information, and a reasonable estimate of its value. If available, gather a recent mortgage statement, records of other property-secured obligations, and correspondence about liens. These materials help clarify what debt is connected to the property. Also write down the financing purpose and expected repayment source so the conversation can address the full transaction.
Can a hard-money loan help with debt consolidation?
It may be an option to discuss if you own property and want to explore property-secured funds for debt payoff. AHL offers debt consolidation hard-money loans, but eligibility and terms depend on review of the specific transaction. Before discussing a request, list the debts you hope to address and consider how consolidation would affect your repayment plan. Don’t assume that combining balances will make the overall obligation affordable.
Are hard-money loans only for investment properties?
Not every hard-money loan is limited to investment property, and not every loan suits an owner-occupied home. Property type and intended use are part of the transaction review. AHL offers several real-estate-secured loan pathways, but fit depends on the particular property and financing purpose. Describe how the property is used and what you want the funds to accomplish.
Is a hard-money loan the same as a home equity loan?
No. “Hard money” generally describes property-backed financing reviewed substantially around the real estate and transaction. A home equity loan is a particular way to seek funds based on property equity. The terms can overlap in a lender’s offerings, but the names aren’t interchangeable. AHL offers both home equity loans and other hard-money financing pathways, so your goal can help frame which one to discuss.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


