
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
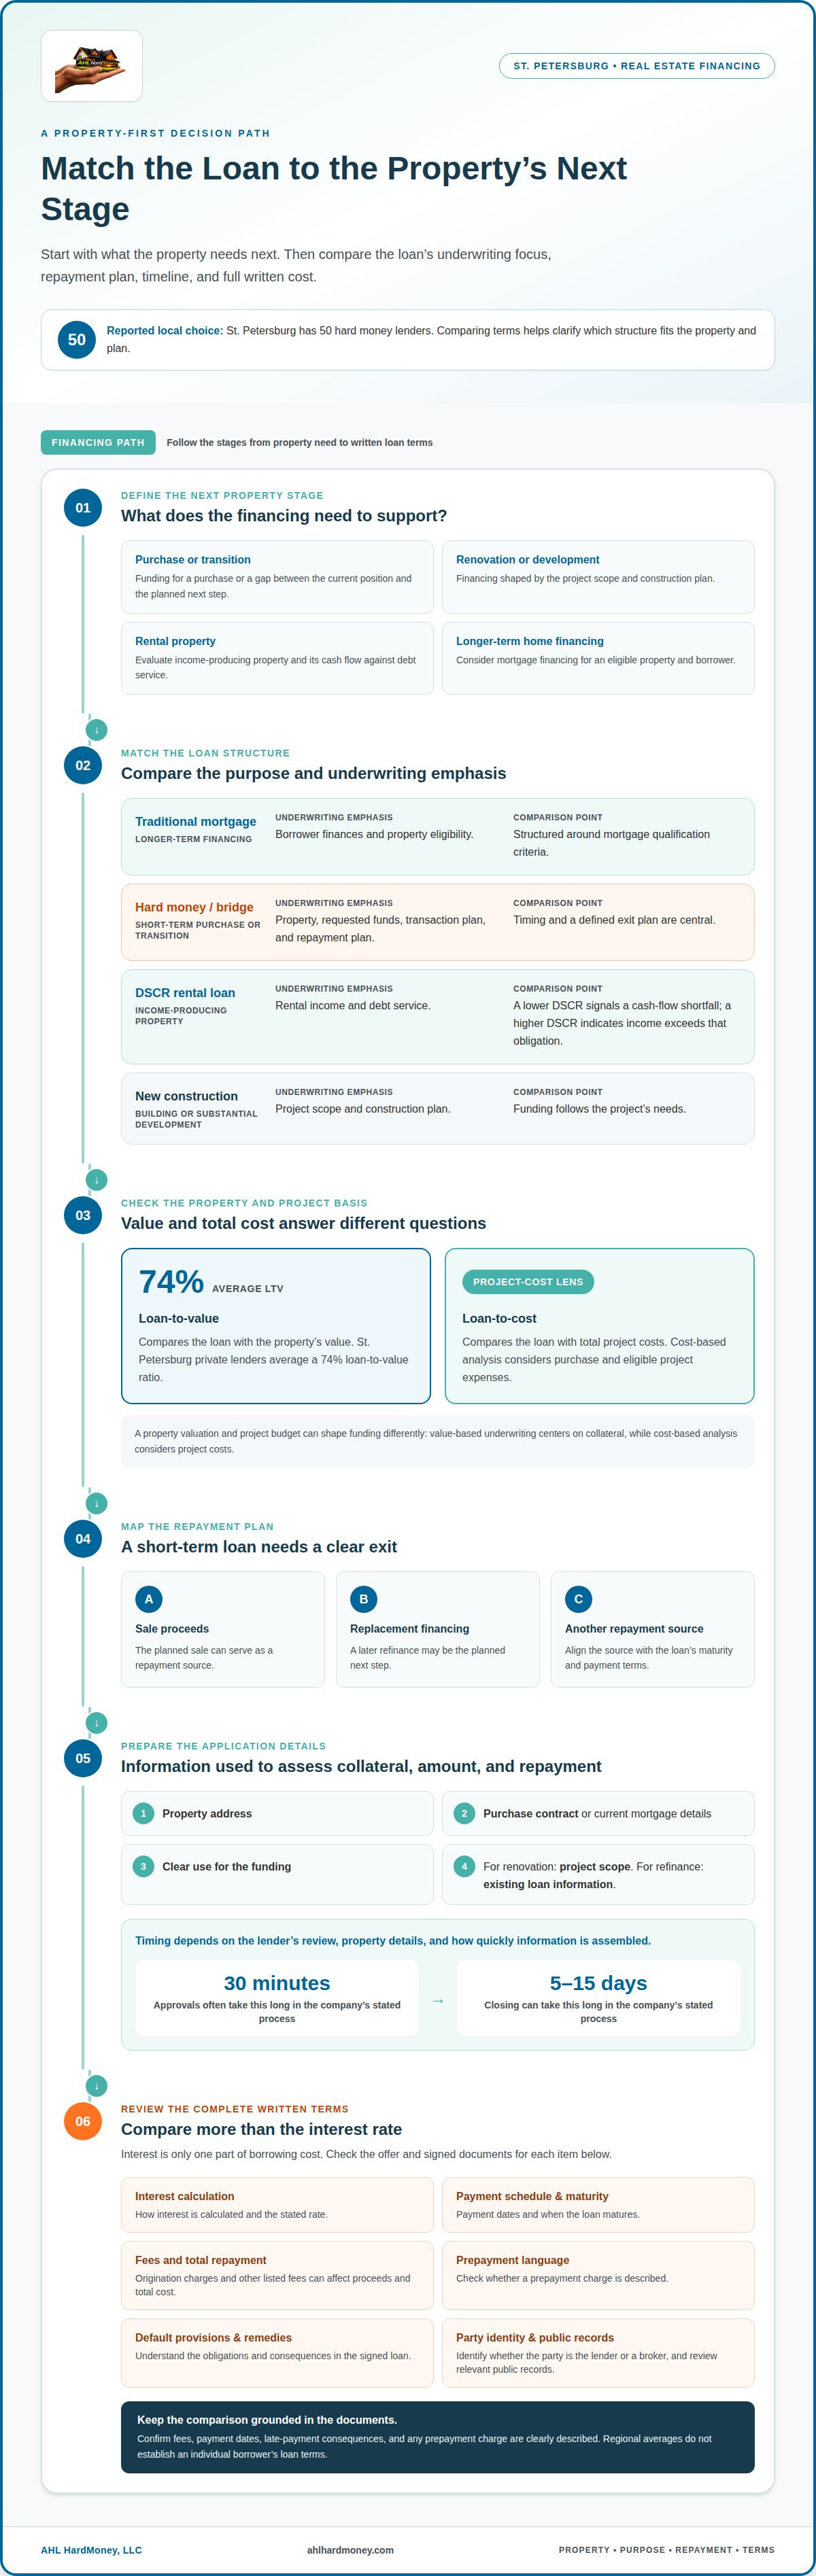
St. Petersburg has 50 hard money lenders, so borrowers have options when a conventional loan doesn’t fit their timing or property plans. St Petersburg private money lenders generally assess a loan around the property’s value and the borrower’s plan for it, rather than relying only on the criteria used for a traditional mortgage. Comparing the terms matters: faster access to funds can come with different costs, repayment periods, and qualification priorities.
If you’re weighing a property purchase, refinance, or another real estate financing need, it’s reasonable to want a clear picture before choosing a path. This guide explains how hard money loans work, how they differ from traditional loans, and what private lending options are available in St. Petersburg. You’ll also find a practical comparison of loan features and guidance for identifying financing that may suit your goals.
Key Takeaways
- Learn how hard money loans use property value and financing goals to shape lending decisions, and how Florida rates can vary by region.
- Compare private financing with traditional loans by looking at approval priorities, timelines, repayment terms, and overall fit.
- See what the reported count of 50 hard money lenders in St. Petersburg means when you’re assessing local options.
- Understand how loan-to-value and loan-to-cost ratios affect the amount of funding a property purchase or project may support.
- Explore how private money refinance, cash-out refinance, home equity loans, and foreclosure refinance loans can address different real estate financing needs.
What is Hard Money Loan?
A hard money loan is real estate financing secured primarily by property. AHL HardMoney, llc serves the entire state of Florida, including St. Petersburg, with property-backed financing. Loan terms depend on the property, the funding purpose, and the repayment plan.
Florida’s reported private-money average interest rates vary by region. In the third quarter of 2026, the Southwest region averaged 9.82%, Central East averaged 9.99%, and Northeast averaged 9.56%. These are regional averages, not a guaranteed rate or a lender’s offer for a St. Petersburg property.
| Florida region | Average interest rate | How to interpret it |
|---|---|---|
| Southwest | 9.82% | Regional market average |
| Central East | 9.99% | Regional market average |
| Northeast | 9.56% | Regional market average |
Choose a financing structure by weighing the property, funding purpose, repayment plan, and full written terms, not just the regional average. A direct lender may assess the real estate and exit strategy alongside borrower details. For investment properties, expected income and the planned hold period help frame the loan request.
Funding speed depends on the lender’s review, property details, and how quickly the required information is assembled. In the company’s stated process, approvals often take 30 minutes, and closing can take 5 to 15 days. Those timings distinguish a streamlined private loan process from a mortgage process that may involve more steps.
Applications commonly call for the property address, purchase contract or current mortgage details, and a clear use for the funding. A renovation request may also need a project scope; a refinance may require existing loan information. The lender uses these materials to assess collateral, requested amount, and repayment plan.
Loan-to-Value and Loan-to-Cost Ratios
Loan-to-value compares the loan with the property’s value; loan-to-cost compares it with total project costs. St. Petersburg private lenders average a 74% loan-to-value ratio. The measures answer different questions: value-based underwriting centers on collateral, while cost-based analysis considers purchase and eligible project expenses. A project budget and property valuation can therefore shape funding differently.
Rules, Risks, and Loan Terms
Florida lending and mortgage-broker rules depend on the transaction and each party’s role. Review hard money terms carefully: check how interest is calculated, the payment schedule, maturity date, prepayment language, default provisions, and remedies. This shows the obligations and consequences attached to the signed loan.
To assess a lender’s licensing and reputation, identify whether the party is the lender or a broker, then review relevant public records and the written loan terms. Compare the documents with the stated offer. Confirm that fees, payment dates, late-payment consequences, and any prepayment charge are clearly described before signing.
Interest is only one part of borrowing cost. Origination charges and other fees can affect the amount received and total repayment, so compare every listed charge alongside the rate. The regional figures above describe averages; they do not establish an individual borrower’s loan terms.
Hard money loans versus traditional loans
Choose financing by matching the loan structure to the property’s next stage. Traditional mortgages, hard money loans, bridge financing, DSCR rental loans, and construction loans serve different purposes. Their underwriting priorities, closing processes, and repayment plans can determine whether funding suits a purchase, renovation, rental, or refinance. Comparing St Petersburg private money lenders with traditional financing starts with understanding those differences.
| Loan option | Underwriting emphasis | Common purpose | Key comparison |
|---|---|---|---|
| Traditional mortgage | Borrower finances and property eligibility | Longer-term home financing | Structured around mortgage qualification |
| Hard money or bridge loan | Property and transaction plan | Short-term purchase or transition | Focuses on timing and a defined exit |
| DSCR rental loan | Rental income and debt service | Income-producing properties | Evaluates property cash flow |
| New construction loan | Project scope and construction plan | Building or substantial development | Funding follows a project’s needs |
A traditional mortgage may fit a borrower seeking stable, longer-term financing for an eligible property. Its underwriting reviews the borrower and property under the mortgage program’s criteria. Hard money financing is more transaction-focused: the property, requested funds, and repayment plan shape the loan. That distinction can matter when a purchase or refinance has timing needs that don’t align with a conventional process.
Bridge loans address a financing gap between a current position and a planned next step. For example, an investor may need purchase funding before completing renovations or arranging a later refinance. The exit plan is central: sale proceeds, replacement financing, or another repayment source should align with the loan’s maturity and payment terms.
DSCR rental property loans assess whether property income can cover debt service. A DSCR compares rental income with debt service, helping investors assess a property's cash flow. A rental property with a lower ratio brings a cash-flow shortfall; a higher ratio indicates income exceeds that obligation. Investors comparing single-family and multifamily properties can use this measure to evaluate rental performance.
New construction loans suit projects where financing must account for building work, rather than only the purchase of an existing property. The project scope, construction budget, schedule, and completion plan shape the funding request. This differs from a bridge loan, which typically solves a timing gap, and a DSCR loan, which centers on rental income.
Compare the property’s stage, underwriting basis, repayment source, and expected hold before choosing. St Petersburg private money lenders may be relevant when a purchase needs short-term financing or an income-producing rental calls for cash-flow-based review. A local lending approach can help clarify how property-focused financing fits a real estate plan.
Number of hard money lenders in St. Petersburg
St. Petersburg has 50 hard money lenders operating in the city. That count gives borrowers a sense of the local market’s breadth, but it doesn’t tell you which lender’s capital, property criteria, or loan program fits your investment. The useful next step is to compare the financing purpose and underwriting approach, not simply count names.
“Lender” can describe different roles in a transaction. A direct lender provides capital, while a broker helps arrange financing between a borrower and a funding source. Ask who makes the credit decision, who funds the loan, and which party appears in the loan documents. Those distinctions clarify where decisions sit and whom you’ll work with through closing.
Property type is another key filter. Residential homes, multifamily buildings, and properties involving construction can have different valuation and project considerations. A purchase loan also differs from financing secured by property the borrower already owns. Describe the asset and its intended use clearly, then compare how the financing evaluates its condition, value, and repayment plan.
For a St. Petersburg application, identify whether the collateral is residential or multifamily, or tied to a construction or purchase project. Lenders assess property details alongside the requested funding and repayment strategy. Borrower qualifications can include credit, relevant experience, available equity, and the ability to carry payments; the weight given to each varies with the loan structure.
Use a consistent comparison process across the 50-lender market:
- Match the purpose: Separate purchase financing from refinance, renovation, or construction needs.
- Clarify the decision-maker: Establish whether the contact lends directly or arranges capital.
- Compare underwriting: Note how the property, credit profile, project plan, and repayment source affect review.
- Read the terms together: Evaluate the rate, fees, payment schedule, maturity, and default provisions as one package.
A lower rate alone doesn’t establish a better fit. For example, a borrower buying a residential property may prioritize a workable closing timeline, while a construction investor needs financing suited to project stages and a clear completion plan. In either case, compare the full written terms against the property’s expected use and repayment source.
The count of 50 is a starting point, not a ranking or measure of approval odds. St. Petersburg borrowers can narrow the field by matching the property category, capital need, and exit plan to a lender’s program. That makes the comparison practical: focus on who funds the transaction, what the underwriting evaluates, and whether repayment terms align with the investment.
Private hard money lending in St. Petersburg
Private hard money lending connects real estate investors with property-backed capital. In St. Petersburg, the average hard money loan amount is approximately $287,500, and the median offered term is 17 months. Those figures provide market context, not a required loan size or term. A lender considers the property, funding purpose, available equity, and repayment plan when structuring a transaction.
This illustrates how purchase financing can combine borrower equity and borrowed capital. It doesn’t establish a universal down payment; a hard money lender assesses the specific property and transaction.
Purpose shapes the lending conversation. A purchase has a defined acquisition target; a refinance replaces or restructures existing property debt. Renovation financing centers on planned improvements, while debt consolidation uses real estate equity toward eligible debts. For each purpose, clarify how you’ll use the funds and how you expect to repay the loan.
Term length deserves close attention. A 17-month median term signals that hard money financing is typically structured around a shorter holding period than long-term rental ownership. Investors should align the maturity date with a practical exit, such as selling the property or arranging a refinance. The repayment plan should account for project progress, market conditions, and the time needed to complete the exit.
Equity is another central consideration. It represents the owner’s stake in the property after accounting for secured debt. A lender may review property value and existing obligations alongside the requested amount. For a rental investment, expected income and operating expenses also help assess whether the project can support the planned borrowing.
Before accepting a private loan, organize the details that explain the transaction:
- Property: Identify the asset, its current condition, and intended use.
- Purpose: State whether funds support a purchase, refinance, renovation, or another real estate need.
- Repayment: Describe the planned sale, refinance, rental income, or other exit source.
- Terms: Review the interest calculation, payment schedule, maturity, fees, and default provisions together.
St. Petersburg investors can use the average loan amount and 17-month median term as reference points, then assess their own project requirements. A clear purpose and credible repayment path help frame the request. The right structure depends on how the property’s equity, use, and timeline work together, rather than on the loan amount alone.
Investors should include this charge in their review of the complete borrowing cost, alongside payment timing, maturity, and the planned exit, before deciding whether the financing fits the property and repayment strategy.
St. Petersburg Private Lender LTV and LTC Ratios
St. Petersburg private lenders offer an average loan-to-value ratio of 74%. LTV compares the loan amount with a property’s value. Loan-to-cost, or LTC, instead compares financing with a project’s total cost. These measures help explain how collateral value and project expenses can shape a real estate funding request.
The example illustrates the arithmetic, not a standard offer. A lender assesses the property and transaction separately.
The distinction matters most when purchase price and project costs differ. An investor buying a property for renovation may need to account for both acquisition and planned work. LTV focuses on the property’s value; LTC relates funding to the costs included in the project budget. Understand which basis a proposed ratio uses.
| Measure | Calculation basis | Useful for understanding |
|---|---|---|
| LTV | Loan amount compared with property value | How much financing is secured against the asset |
| LTC | Loan amount compared with total project cost | How funding relates to acquisition and project expenses |
To interpret an LTV quote, divide the loan amount by the property value, then convert the result to a percentage. For LTC, divide the proposed loan by the costs counted in the project budget. Confirm the valuation and cost assumptions used in each calculation. Different assumptions can produce different ratios for the same property.
A 74% average is a market reference, not a promise of funding at that level. Property condition, valuation, existing liens, project scope, and repayment plan all affect a lender’s review. A refinance also differs from a purchase: existing debt and available equity influence the amount under consideration.
Before comparing proposals, line up the same inputs: property value, requested loan, existing debt, and project costs. Then compare each lender’s stated LTV or LTC basis, payment terms, maturity, and fees. This helps show whether a proposal reflects the property’s value, the project’s cost, or both.
For a real estate investor, the practical question is how the ratio affects required equity and the exit plan. A lower loan share may mean bringing more capital to closing; a project-based calculation may account for costs beyond purchase. Use the written figures to test whether the financing aligns with the intended use and repayment path.
AHL HardMoney: Private Money Refinance
AHLHardMoney™ offers Private Money Loans and Refinance Loans for borrowers seeking property-backed financing. These options may suit a homeowner or investor who wants to restructure existing property debt and needs an alternative to a traditional mortgage. The right fit depends on the property, financing purpose, and repayment plan.
Other relevant options include Cash Out Refinance, Home Equity Loans, and Foreclosure Refinance Loans. These serve different needs, from accessing property equity to addressing mortgage pressure. Reviewing the purpose alongside the loan terms can help clarify which route matches your situation.
Contact AHLHardMoney™ to discuss your private money refinance needs and take the next step toward financing.
Choose a Financing Path That Fits Your Next Move
Your next step is to connect the property’s role with the financing purpose. A refinance may help reshape existing property debt, while equity-based financing can support a different plan. Before moving forward, define what the funds need to accomplish and how the resulting loan fits your broader real estate goals. That clarity makes a conversation about St Petersburg private money lenders more focused and keeps the decision grounded in your intended outcome.
AHLHardMoney™ offers Private Money Loans, Refinance Loans, Cash-Out Refinance, and Home Equity Loans. Each addresses a distinct property financing need, so start with the change you want the loan to support. Consider how the proposed structure aligns with your repayment plan and the property’s future use.
A clear purpose can make a complicated financing decision more manageable. Move forward with a plan that reflects your property and your goals.
Frequently Asked Questions
What private money lenders serve St. Petersburg, Florida?
AHLHardMoney™ serves the entire state of Florida, including Saint Petersburg. Its focus counties are Hillsborough, Pasco, Pinellas, Polk, Manatee, Citrus, and Hernando. Its service-area cities include Tampa, Clearwater, Saint Petersburg, Palmetto, Largo, Newport Richey, Port Richey, Brooksville, Brandon, Orlando, Daytona, Napels, Ocala, Deltona, Deland, Jupiter, Palm Beach, Lakeland, and Boca Raton. Match the property location and financing purpose when comparing terms.
Which St. Petersburg private lenders offer fix-and-flip, rental, or bridge loans?
AHLHardMoney™ offers Purchase Loans and Refinance Loans for real estate investors planning property transactions. For a fix-and-flip, rental, or bridge strategy, outline the acquisition, intended work, holding plan, and repayment exit. Those details help frame the financing need and clarify whether purchase or refinance financing is the closer fit. The loan’s written purpose and terms should align with the investment plan.
What are typical private money loan rates, fees, and points in St. Petersburg?
Rates and fees depend on the case and are provided after a quote request; property value, loan purpose, term, and repayment structure affect the proposed terms. A point is 1% of the loan amount (1 point = 1% of loan); 100 basis points = 1 point. Compare the interest rate and every charge in the written offer, since points are only one part of borrowing costs.
How do St. Petersburg private lenders compare with banks and other hard money lenders?
Private lenders and banks can differ in their underwriting priorities, documentation, and loan structure. AHLHardMoney™ states “No Hard Credit Inquiry” and accepts any credit profile, while its property-backed programs include purchase and refinance financing. To compare lenders, review how each evaluates the property and intended use, then assess payment terms, maturity, fees, and repayment plans together. The full written terms show how the financing fits your situation.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


