
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
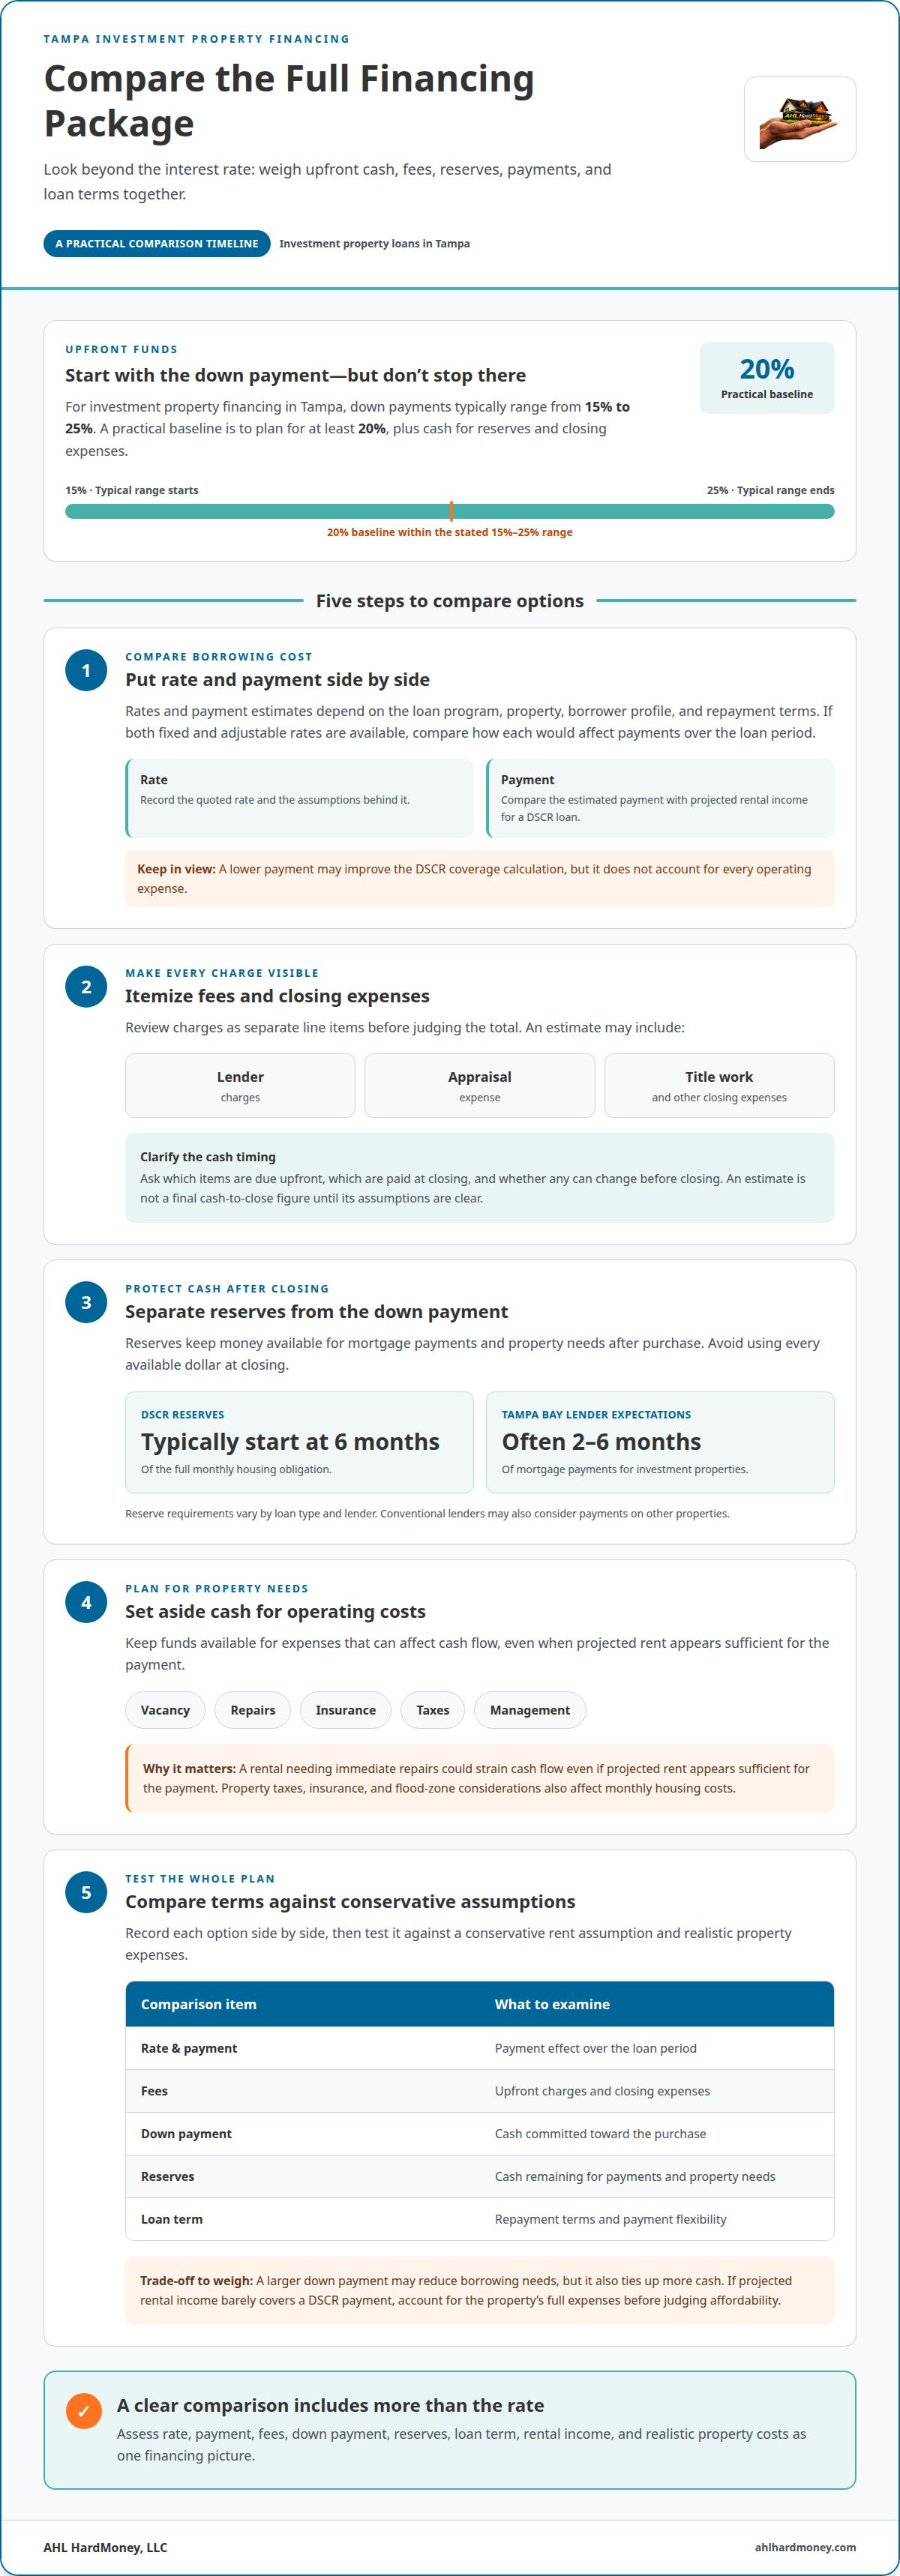
The down payment is only the starting point. For investment property financing in Tampa, down payments typically range from 15% to 25%, depending on the loan program, property and borrower profile. A practical baseline is to plan for at least 20%, while also setting aside cash for reserves and closing expenses.
That upfront amount matters, but it is only part of the financing picture. Rental income may help show whether a property can support its payments, while rates, fees, credit, reserves, and loan terms affect the funds and flexibility you’ll need. Private-money financing may also fit a purchase that calls for an asset-focused approach.
This guide explains how lenders may assess rental income, what to weigh when comparing down payments and loan terms, and why projected rent does not tell the full cash-flow story. You’ll also learn how reserves, rates, and fees shape the decision, and where Florida private lenders may fit when timing or property condition makes financing more complex.
Key Takeaways
- Learn how rental income and property-based qualification methods can shape a Tampa investment loan.
- Compare financing by looking beyond the interest rate to fees, cash reserves, loan terms, and the property’s full operating costs.
- Understand when Florida-based private-money financing may suit a time-sensitive purchase or a property that needs work.
- Explore how different loan types align with your investment plan, property, and financing needs.
- See how AHL HardMoney’s refinance and home equity options may fit specific financing situations.
Can rental income help me qualify for a Tampa investment loan?
Yes. Lenders may consider projected rental income when evaluating whether an investment property in Tampa can support its mortgage payments. The approach depends on the loan type, credit profile, reserves, and property value.
DSCR Credit and Reserve Requirements
A debt-service coverage ratio (DSCR) loan weighs property income against its full housing payment, rather than relying only on personal income. A 1.00x ratio is a common underwriting baseline, but a ratio above 1.0 doesn’t prove the property will generate profit. Tampa-area investment lenders commonly seek credit scores of 620 to 680. DSCR reserves typically start at six months of the full monthly housing obligation.
DSCR Loan-to-Value Requirements
Loan-to-value (LTV) compares the loan amount with the property’s appraised value. Standard Florida DSCR purchase files commonly have a maximum LTV of 75 percent, so the remaining purchase funds must come from other sources. The appraisal and accepted property value therefore affect borrowing capacity. A lower loan amount may also change the payment used in the DSCR calculation, affecting how projected rent compares with the mortgage obligation.
Debt-to-Income and Reserve Requirements
Conventional investment loans commonly verify personal income, assess debt-to-income ratios, and may limit how many properties a borrower can finance. Lenders also commonly require cash reserves for several months of rental-property payments, sometimes including payments on other properties. Tampa Bay investment-property lenders often look for reserves covering 2-6 months of mortgage payments. Review the full picture: credit, debts, documented income, property obligations, and accessible cash.
Credit is one part of approval across loan types, but its role varies. Conventional underwriting may weigh personal income and debt-to-income closely; DSCR underwriting focuses more on property income and payment coverage. The U.S. Census Bureau’s population estimate for July 1, 2025 (V2025) was 413,554 people. Tampa’s population scale makes comparable rents and realistic occupancy assumptions important when assessing returns.
Short-term rental rules depend on the property’s location and applicable local restrictions. Loan eligibility also depends on whether the lender accepts projected rental income. Some short-term rental lenders assess platform income, while Tampa Bay DSCR lenders may use rental comparables or historical performance.
Prices, rents, and yields vary by property and neighborhood. Use comparable Tampa and Hillsborough County properties to assess your specific rental plan.
Property taxes, insurance, and flood-zone considerations affect the monthly housing cost used in a loan assessment. Higher carrying costs leave less rental income available for the mortgage, even when projected rent looks strong. Include these expenses when evaluating affordability and potential returns.
To apply, organize the purchase details, property information, income or rental projections, credit and debt information, and evidence of available reserves. The lender uses these items to assess repayment, collateral, and approval. Owners considering equity against free-and-clear Florida property can also assess how existing ownership fits their financing plan.
Key risks include vacancy, repairs, operating costs, and rent projections that don’t match actual performance. Tampa metro rental vacancy reached 10.7 percent in the most recent reading described in the market snapshot. Stress-test the budget against empty periods and property expenses; a DSCR above 1.0 alone doesn’t establish a profit.
Comparing rates, fees, down payments, and reserves
Compare the full financing package, not just the interest rate. A lower rate may come with different fees, cash requirements, or loan terms. For investment property financing in Tampa, give the funds you’ll need beyond the down payment equal attention.
Rates affect scheduled payments, but the estimate depends on the loan program, property, borrower profile, and repayment terms. If both fixed and adjustable rates are available, compare how each would affect payments over the loan period. With a DSCR loan, compare the payment with projected rental income. A lower payment may improve the coverage calculation, but it does not account for every operating expense.
Review fees as separate line items before judging the total. An estimate may include lender charges, appraisal, title work, and other closing expenses. Ask which items are due upfront, which are paid at closing, and whether any can change before closing. A broker can help explain the sources of each charge and how the chosen program affects them. Don’t treat an estimate as a final cash-to-close figure until its assumptions are clear.
Reserves serve a different purpose from the down payment: they keep funds available for mortgage payments and property needs after purchase. Set aside money for vacancy, repairs, insurance, taxes, and management instead of using every available dollar at closing. A rental that needs immediate repairs, for example, could strain cash flow even if projected rent appears sufficient for the payment.
Use a side-by-side comparison to make trade-offs clear. Record the rate, payment, fees, down payment, reserve expectations, and term for each option. Then test the estimate against a conservative rent assumption and realistic property expenses. If projected rental income on a DSCR loan barely covers the payment, a larger down payment may reduce borrowing needs, but it also ties up more cash. This makes investment property financing in Tampa easier to assess against your rental plan.
Review the whole financing structure before choosing. A practical next step is to discuss the property, timeline, and cash priorities with a financing team; learn more about the people behind the financing process. That conversation can help clarify which figures drive the estimate and which trade-offs matter most.
Florida-based private lenders
Florida private lenders can provide an asset-focused route for real estate purchases that need flexible underwriting or a faster closing. Hard Money Loans may suit a distressed-property purchase, a buyer competing with cash offers, or a short-term bridge need. The property and proposed financing structure are central, alongside the borrower’s repayment plan.
Rates vary by lender, collateral, loan structure, and repayment plan. Regional figures offer context, not a Tampa quote: Southwest Florida’s average private-money interest rate was 9.82% in the third quarter of 2026, based on 77 loans secured by Lee County properties. Florida’s Central East region averaged 9.99% that quarter. Those regional benchmarks are not interchangeable with a Tampa loan estimate.
Private financing also has a different timeline from a longer, document-intensive process. Tampa Bay hard money loans can often close in 5 to 10 business days, depending on title and appraisal timelines. That speed can help with a time-sensitive purchase, but the appraisal, title review, and property condition still shape the closing schedule. A delayed title issue can affect when funds are available.
Before choosing a structure, match the loan to your real estate plan. A purchase that needs repairs may call for a different approach than a stabilized rental or refinance. Write down the intended use, expected holding period, repayment source, and exit plan. For example, if bridge financing will support renovations, align the loan term with the work and the next financing or sale step.
Review the full loan terms, not just the rate. Compare the repayment schedule, maturity date, payment frequency, collateral, extension provisions, and any fees disclosed in the loan documents. Confirm how the property value is determined and what documents support the proposed loan amount. These details show the obligations attached to the financing.
Prepare a clear package for the lender. Include the purchase contract or refinance details, property address, condition information, project budget when relevant, and repayment plan. Organize these details before underwriting begins so the property and transaction are easy to understand. Keep funds available for closing costs and property needs rather than committing every dollar to the purchase.
Private-money financing works best when it has a defined purpose and exit plan. For a Tampa buyer facing a tight closing window or a property that needs work, weigh speed against the loan’s total obligations and repayment timeline. If the projected exit depends on rent, test the plan against vacancy and operating costs before committing.
Private-money lenders serving Tampa and Florida
Private-money lending can help address a real estate purchase with a tight timeline, unusual property condition, or bridge-financing need. Florida recorded approximately $44.8 billion in private-money loan volume across 16,172 loans in the second quarter of 2026. That statewide activity shows the market’s scale, but it doesn’t tell a Tampa borrower which loan structure fits their property or repayment plan.
Regional data offers context, not a personal qualification decision. Florida’s Central East region had an average private-money loan amount of $361,641 in the third quarter of 2026. A Tampa property’s value, condition, available equity, and transaction purpose can all shape the amount considered. Use regional figures as background, then assess the subject property and proposed financing individually.
Start by identifying what the financing needs to accomplish. A borrower buying a property that needs repairs may need short-term funds before renovation or rental income begins. An owner refinancing an existing property may have a different goal, such as changing the debt structure. In either case, match the loan term and payment plan to a realistic exit, such as a sale, refinance, or operating income.
Location matters in the underwriting file. For a Hillsborough County property, provide a clear address, ownership or purchase details, condition information, and a supportable value. If the building is intended for housing, the expected use and current occupancy also help explain the transaction. Organizing these details early gives the lender a clearer picture of the property and requested financing.
Review the proposed terms as a complete package. Focus on the payment schedule, maturity date, collateral, applicable fees, and conditions that affect closing. Understand how the property value is evaluated and which title or appraisal steps remain. A fast process can still depend on third-party timelines, so align the purchase contract with the financing schedule.
Qualification depends on the lender’s underwriting approach and the property’s equity, condition, and intended use. Credit and personal income may matter differently across programs, while the real estate asset can remain central to an asset-based loan. Compare the repayment plan with the loan term. If repayment relies on a future refinance, consider whether the property can support that transition.
For Tampa-area financing, prepare one consistent account of the transaction: the property, funds requested, use of proceeds, and exit plan. Keep purchase or refinance records, valuation details, and project information organized. This makes key questions easier to address before closing and helps you understand how the financing connects to the property’s next step.
What loan types are available for financing investment property in Tampa?
Tampa investors may compare conventional investment mortgages, debt-service coverage ratio (DSCR) loans, and private-money financing. The right category depends on the property, intended use, income documentation, and repayment strategy. First identify whether you’re buying a stabilized rental, a property that needs work, or a building you’ll partly occupy.
Conventional investment loans assess the borrower as well as the property. Lenders commonly verify personal income, review debt-to-income ratios, and may limit the number of financed properties. This approach may suit buyers with documented income and a property that meets standard underwriting requirements. Compare the qualification process and payment structure with expected rental income before choosing.
A DSCR loan focuses on whether property income can cover the mortgage obligation, rather than relying primarily on personal income. It may suit an investor whose property cash flow is central to the application. Projected rent, the appraisal, property expenses, and proposed payment all affect the assessment. A rental plan with a clear basis for its income makes the financing case easier to evaluate.
Private-money or hard-money financing is asset-based and may suit a distressed-property purchase, a buyer competing with cash offers, or a short-term bridge need. It may be relevant when the property’s condition or purchase timeline makes conventional underwriting a poor fit. Consider the repayment path before borrowing. For example, align the financing term with the renovation project and intended exit.
Owner occupancy can open a different route for some multi-unit purchases. FHA and VA loans are generally intended for primary residences, not properties used solely as rentals. A Tampa buyer purchasing a multi-unit property and living in one unit may sometimes qualify for owner-occupied financing. That differs from buying a property solely to rent, so clarify intended occupancy from the outset.
Property size can also change the financing conversation. That figure applies to the stated one-unit limit, not every property type or loan program. Buildings with five or more units call for consideration of other loan options, since unit count affects how the transaction is evaluated.
Compare options by matching each loan’s qualification basis, payment schedule, term, and property requirements to your plan. A stabilized rental may suit income-based underwriting, while a time-sensitive purchase that needs repairs may call for bridge financing. For a multi-unit purchase, decide whether you’ll occupy a unit or rent every unit before evaluating the available route.
AHL HardMoney
AHL HardMoney, llc can help Tampa property owners explore investment property financing Tampa options when a refinance or existing property equity is central to the plan. Its offerings include Cash Out Refinance, Home Equity Loans, Private Money Refinance, and Foreclosure Refinance Loans. These options may be relevant when you’re restructuring existing debt or considering how property equity could support your next financial step.
Bring the property details, current financing, intended use of funds, and repayment plan into the discussion. That context helps connect your goals with the relevant option and clarify the financing structure. AHL HardMoney, llc provides hard-money financing to borrowers throughout Florida, with approvals often within 30 minutes and loan closings in 5 to 15 days.
Contact AHL HardMoney, llc to discuss your property and financing goals.
Set your next financing step with purpose
Before moving ahead, define what success looks like for the property. Consider whether your priority is acquiring an asset, reorganizing current debt, or using equity for a planned need. Then align the financing discussion with that goal, your expected holding period, and a realistic repayment path. This makes investment property financing in Tampa a decision tied to your investment strategy, not just a loan estimate.
For property owners whose plans involve existing real estate, AHLHardMoney™ offers Cash-Out Refinance, Home Equity Loans, and Private Money Loans. These options address different financing goals, so start with the property and the purpose behind the request. A clear picture of both helps focus the discussion on a relevant next step.
Bring your goals to the conversation with AHLHardMoney™ and explore a financing path that fits your situation. A clear plan can help you move forward with greater confidence.
Your investment plan can take shape one informed decision at a time.
Frequently Asked Questions
How much down payment do I need for an investment property in Tampa?
Plan for a down payment commonly ranging from 15% to 25%, with at least 20% a useful planning baseline. The amount depends on the loan program, property details, and borrower profile. Also budget for closing expenses and cash reserves, since the down payment isn’t the only cash needed to complete a purchase and manage the rental afterward.
Can I buy a rental property in Tampa Bay through an LLC?
An LLC may be part of a rental-property purchase, but the financing and ownership documents need to reflect the intended structure. Underwriting may consider the entity’s formation and ownership records, the property, and the repayment plan. Clarify whether the loan and title will use the LLC or an individual borrower before finalizing the purchase contract, because requirements depend on the loan program.
Can I get a loan for a rental property if it’s not currently rented?
Yes, a vacant property can still be considered for financing. Projected rent may be estimated using an appraisal rent schedule and comparable local rentals, while some short-term rental lenders assess projected platform income or historical performance. Prepare a realistic rental plan that explains the intended use and expected income. The lender’s approach determines how projections factor into qualification.
How fast can I close with a hard money lender?
AHL HardMoney, llc states that loans can close in 5 to 15 days, regardless of credit history. That is the company’s stated closing timeframe, not a promise for every transaction. Title and appraisal timelines, property records, and complete application materials can affect progress. For a purchase with a set contract deadline, organize the transaction documents early and account for the steps needed before closing.
What down payment is required for a Tampa investment property loan?
Tampa investment-property loans commonly call for 15% to 25% down, and planning for at least 20% is a practical starting point. The required contribution can change with the loan program, number of units, and borrower profile. Keep reserves and closing funds separate from the down payment.
What credit score, debt-to-income ratio, and cash reserves do Tampa investment property lenders require?
Tampa Bay investment-property lenders commonly seek credit scores of 620 to 680. Conventional loans often verify personal income and assess debt-to-income, while DSCR underwriting focuses more on property income relative to its housing payment. Reserve expectations also vary: lenders commonly look for 2-6 months of mortgage payments, and DSCR requirements typically start at six months of the full monthly housing obligation.
How do conventional, DSCR, portfolio, and hard money loans compare for Tampa rental properties?
Conventional loans typically review personal income and debt-to-income. DSCR loans focus on whether property income covers its housing payment. Portfolio loans are held by the lender rather than sold as standard conforming loans, so terms depend on the lender’s program. Hard money is asset-based and may suit a distressed purchase, short-term bridge need, or time-sensitive transaction. Compare qualification, term, payment, and exit plan.
What closing costs, loan fees, and prepayment penalties should Tampa investors expect?
Costs depend on the loan structure and transaction, so compare estimates line by line rather than assuming one standard total. Review lender charges, appraisal and title expenses, and other listed closing costs. Read the loan documents for prepayment terms, including whether a penalty applies, when it applies, and how it is calculated. Keep expected cash to close separate from post-closing reserves.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


