
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
The right financing for a Tampa rental may start with equity you already own, not just the property you plan to buy. If you’re comparing Tampa rental property loans, consider whether your goal is to purchase a rental, refinance a property, or access equity in real estate you already own.
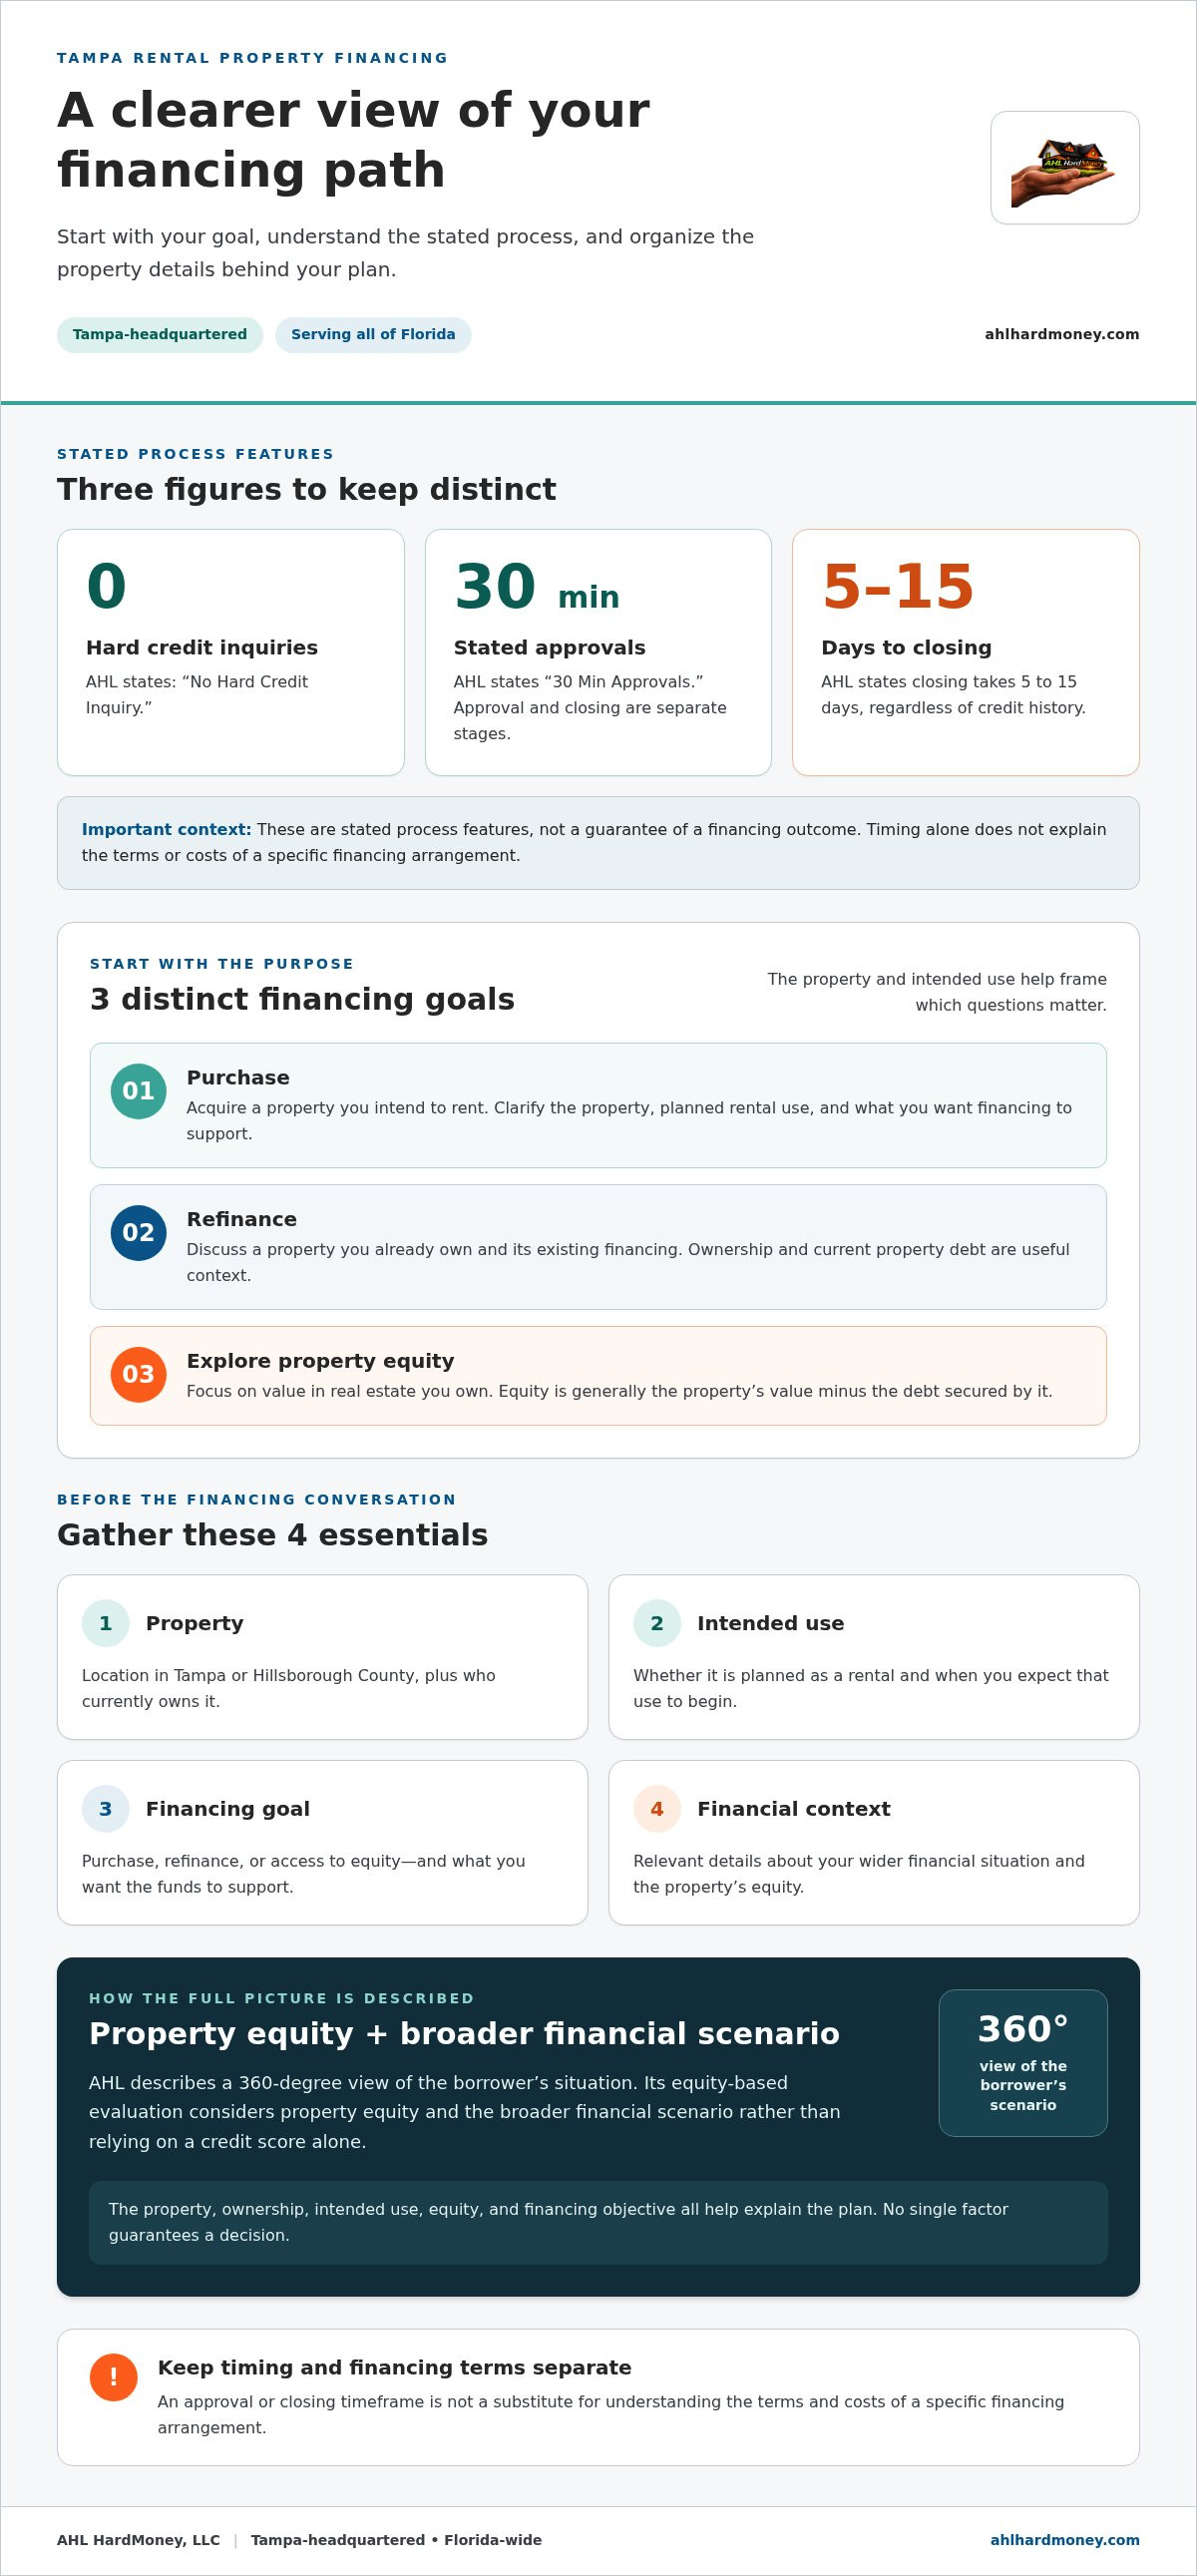
The right path depends on the property, how you plan to use it, and your wider financial situation. This guide compares purchase and equity-focused options, explains how a cash-out refinance and home equity loans may fit different goals, and outlines what to prepare for a financing conversation. AHLHardMoney™ takes a 360-degree view of a borrower’s financial scenario and states No Hard Credit Inquiry and 30 Min Approvals, with closing in 5 to 15 days.
We’ll cover the key financing paths, the property and borrower details to gather, and how a Tampa-headquartered lender serving the entire state of Florida can help you discuss your plan.
Key Takeaways
- Match Tampa rental property loans to your goal, whether you’re financing a purchase or exploring a refinance.
- Understand how hard-money financing relates to real estate equity and how AHLHardMoney™ considers a borrower’s broader financial scenario.
- Compare Hard Money Loans, Private Money Loans, Purchase Loans, and Refinance Loans by the goal you need to fund.
- Organize details about the property, ownership, intended use, and financing goal to make your lending conversation more focused.
- AHLHardMoney™ is headquartered in Tampa and serves the entire state of Florida, with No Hard Credit Inquiry, 30 Min Approvals, and closing in 5 to 15 days.
Tampa Rental Property Loans: Start With the Property and Your Investment Goal
A rental-property loan is financing connected to real estate you intend to rent. The right conversation starts with what you plan to do: buy a rental, refinance a property you own, or access equity in real estate. These are distinct goals, even when they’re part of the same investment plan. Identify the property and purpose of the funds before comparing financing paths.
That’s a practical starting point for Tampa rental property loans. Tampa and Hillsborough County provide the local context, but the city alone doesn’t determine which approach fits. The property’s intended use, ownership status, equity, and your wider financial situation all help frame the discussion. For an overview of real estate investment approaches, see Understanding Real Estate Investing.
What makes a rental-property financing goal different?
A purchase goal is about acquiring a property you intend to rent. A refinance goal concerns a property you already own and its existing financing. An equity goal focuses on the value available in property you own. Being clear about which goal applies helps explain what you want the funds to support. Rental plans, occupancy, and credit circumstances are useful context, not automatic approval criteria.
For example, one investor may be planning a Tampa-area purchase, while another owner may want to explore equity in a property in Hillsborough County. Those situations call for different questions about the property and how the funds would be used. If you’re considering equity in a property you own, AHL’s information on a free-and-clear Florida property offers related context about property ownership and financing discussions.
Which Tampa property and borrower details matter first?
Start with the property’s location, who owns it, and whether it’s already a rental or will be rented after purchase. Then state your financing goal plainly: acquire a property, refinance existing financing, or explore available equity. AHL considers the borrower’s broader financial scenario alongside the property, so organizing both sides of the picture makes it easier to explain your plan.
Before comparing options, jot down these basics:
- Property: Its location in Tampa or Hillsborough County and current ownership status.
- Intended use: Whether it’s planned as a rental and when you expect that use to begin.
- Financing goal: Purchase, refinance, or access to equity, and what you want the financing to support.
- Financial context: Relevant details about your overall situation and the property’s equity.
You don’t need to choose a loan label before asking questions. A clear description of the property, its intended rental use, and your goal gives the conversation a practical starting point. From there, you can discuss which financing path aligns with your circumstances and investment objective.
How Tampa Hard-Money Rental-Property Financing Considers the Full Picture
Hard-money lending is a non-institutional form of financing connected to real estate and property equity. It offers a different way to approach a financing discussion than looking at a borrower’s credit score alone. Equity-based evaluation considers the property’s equity and the borrower’s broader financial scenario, rather than relying on a credit score alone.
For Tampa rental property loans, that distinction can be useful if your financial circumstances don’t fit a conventional template. AHLHardMoney™ describes its approach as a 360-degree view: the property, your overall situation, and your objective all matter. No single factor guarantees a decision, but a fuller picture can make the conversation more relevant to your investment plan.
How property equity fits into the financing conversation
Equity is generally the property’s value minus the debt secured by it. A property with no mortgage has no existing mortgage debt to subtract; a mortgaged property has a different equity position. The property details and your goal belong together: an owner exploring equity may have a different financing purpose from an investor seeking to acquire a rental.
If you’re considering a Florida property with no mortgage, AHL’s Florida property with no mortgage information offers related context. In a financing discussion, be ready to describe ownership, any existing property debt, and what you intend to do with the funds. Those details help explain your objective, whether it involves a rental property or another real estate plan.
What AHL’s stated process and timing mean
AHL states No Hard Credit Inquiry and 30 Min Approvals. These are process features, not a guarantee of a particular financing outcome. The company also states that closing takes 5 to 15 days, regardless of credit history. Approval and closing are separate stages, so keep their timing distinct as you plan around an investment opportunity.
Timing alone doesn’t tell you what financing will cost. Don’t treat an approval or closing timeframe as a substitute for understanding the terms and costs of a specific financing arrangement. The CFPB’s mortgage information and consumer protections provides general resources about mortgage topics and consumer protections.
AHLHardMoney™ is headquartered in Tampa and serves the entire state of Florida. To learn more about the company’s approach before discussing financing, visit AHLHardMoney™ and its lending approach.
Compare Tampa Rental Property Loan Paths by the Goal You Need to Fund
Compare financing paths by what you need the funds to accomplish: acquire a rental, refinance a property you own, or access equity. Tampa rental property loans can involve different options depending on that objective. Use the comparison below to organize your questions and explain your plan.
| Your goal | Relevant AHL program | Questions to discuss |
|---|---|---|
| Acquire a property intended for rental use | Purchase Loans, Hard Money Loans, or Private Money Loans | Where is the property, who will own it, and what is the intended rental use? |
| Refinance an existing property | Refinance Loans, Hard Money Loans, or Private Money Loans | What financing is already connected to the property, and what is the refinance meant to accomplish? |
| Access equity as part of refinancing | Cash-Out Refinance | How would the funds support your investment objective, and what property equity is involved? |
| Explore equity through a home equity path | Home Equity Loans | What do you plan to use the funds for, and what is the property’s ownership and debt status? |
Financing a rental purchase versus refinancing an existing property
A Purchase Loan relates to acquiring a property. Bring the property details and intended rental use into that discussion, along with your broader financing goal. A Refinance Loan is a path to discuss if you already own the property and want to consider changing its financing. The existing debt, ownership, and purpose of the refinance help explain what you’re aiming to do. A program name alone doesn’t establish terms or determine whether it fits your situation.
If refinancing is connected to accessing equity, compare that purpose with a cash-out refinance option. A cash-out refinance involves refinancing while seeking access to property equity; a Home Equity Loan is a separate equity-focused path. For more Florida context, see this Florida cash-out refinance equity guide.
When an equity-focused loan path deserves consideration
Start with why you want to access equity. If your goal involves refinancing the property, Cash-Out Refinance may be relevant to discuss. If you’re exploring a home equity route, Home Equity Loans offer another path to consider. Neither label guarantees a particular outcome. Explain how the funds relate to your rental-property plan and share the property’s ownership and existing debt context.
Hard Money Loans and Private Money Loans are also financing paths to discuss alongside a purchase or refinance goal. Compare them based on the purpose you need to fund, the property involved, and your wider financial picture. This keeps the conversation grounded in your investment plan rather than assumptions about approval, loan terms, or strategy.
Prepare for a Tampa Rental Property Loan Conversation
A focused conversation starts with a clear picture of the property and what you want the financing to accomplish. For Tampa rental property loans, organize the details you know instead of trying to predict which factors will determine an outcome. AHL considers the borrower’s wider financial scenario alongside the property, so explain both your real estate plan and the context behind it.
A practical checklist for the property and rental plan
Use this sequence to organize your notes. It’s a preparation guide, not a required-document list or a promise of qualification. Keep the information accurate, flag anything you’re still working out, and describe your plan in everyday terms.
- Identify the property. Note its address or location in Tampa or elsewhere in Hillsborough County, and describe the property as you understand it.
- Clarify ownership. State whether you already own the property, who holds ownership, and whether any property debt is attached to it.
- Describe the intended use. Explain whether the property is already a rental or is intended for rental use after purchase. Include your anticipated timing without treating it as an approval condition.
- State the financing goal. Say whether you’re considering a purchase, refinance, or access to equity, and what you want the funds to support.
- Summarize the financial context. Organize relevant information about your overall financial scenario and the property’s known equity and existing debt. Don’t estimate a loan amount without a basis for doing so.
These details connect the property to your plan. An owner considering a refinance can distinguish that goal from a purchase, while an investor preparing to acquire a rental can explain the intended use and timing. You don’t need a polished forecast to start the discussion. A straightforward account of what you know, what you intend, and what remains undecided provides a practical starting point.
How AHL’s Florida service area applies to Tampa borrowers
AHLHardMoney™ is headquartered in Tampa and serves the entire state of Florida. Its focus areas are Hillsborough, Pasco, Pinellas, Polk, Manatee, Citrus, and Hernando Counties. For Tampa borrowers, that means a local starting point within a Florida-wide service area, whether the property is in Hillsborough County or elsewhere in the state.
Wherever the property is located, bring the same organized overview to the conversation. Its location, ownership, intended rental use, known equity, and your financing objective all help explain the request. Add relevant information about your broader financial situation so the discussion can consider the whole scenario, rather than treating the property or a single borrower detail in isolation.
You don’t need every answer in advance. Start with the facts you have, distinguish confirmed details from plans, and make your goal easy to understand. That gives you a clearer foundation for discussing a financing path without assuming that one property feature or financial detail guarantees a particular result.
Move Forward With AHLHardMoney™ for a Tampa Rental Property
Once you’ve identified the property and clarified your goal, the next step is a financing conversation based on your situation. AHLHardMoney™ is headquartered in Tampa and serves the entire state of Florida. For investors considering Tampa rental property loans, that means you can discuss a purchase, refinance, or property-equity objective with a Florida-based lending partner.
What borrowers can expect from AHLHardMoney™
AHLHardMoney™ takes a personalized approach and considers a 360-degree view of a borrower’s financial scenario. The company accepts any credit profile and works with owner-occupied and non-owner-occupied properties. Its stated features include No Hard Credit Inquiry and 30 Min Approvals. Closing takes 5 to 15 days, regardless of credit history. These are process details, not a guarantee of approval or a particular financing outcome.
Displayed ratings offer another point of reference: Google 4.9, Facebook 4.9, and BBB 5.0. Consider them alongside the details of your own plan. A productive discussion connects the property, its ownership and equity context, your intended rental use, and your broader financial picture, rather than relying on one detail alone.
Take the next step with your property goal in hand
Be ready to explain what you want to do: purchase a rental property, refinance an existing property, or explore access to property equity. Add the property’s location, ownership status, intended use, and any known existing property debt. You don’t need every detail resolved. A straightforward summary gives the conversation a useful starting point.
For more background on asset-based financing in Florida, explore this Florida hard-money lending guide. It can help put the financing approach in context as you organize your questions and decide what you want the funds to support.
Bring your property goal and relevant details together to discuss how they fit your overall financial scenario. AHLHardMoney™’s Tampa headquarters and Florida-wide service provide a local starting point for investors across the state.
Turn Your Rental Property Plan Into a Clear Next Step
Before moving forward, test your investment goal: Can you explain what the financing would help you do, how the property fits that plan, and what you need to understand before making a decision? That clarity helps keep the conversation focused, whether you’re pursuing Tampa rental property loans for a new acquisition or exploring an existing property’s potential.
Connect the financing path to the intended use of the funds and the wider investment picture. You don’t need every detail settled. A clear goal and an honest account of what you know can help you make a more informed decision.
Your investment plan is yours to shape. Move forward thoughtfully, ask focused questions, and take the next step with AHLHardMoney™.
Frequently Asked Questions
Can I get a Tampa rental property loan with challenged credit?
AHL accepts any credit profile and states No Hard Credit Inquiry. This doesn’t guarantee approval or a particular financing outcome. To make the discussion useful, explain what you want to finance and share relevant details about the property and your broader financial situation. For example, clarify whether you’re purchasing a rental, refinancing a property you own, or seeking to access its equity.
How quickly can AHL approve and close a Tampa rental property loan?
AHL states 30 Min Approvals, and closing takes 5 to 15 days, regardless of credit history. Approval and closing are separate steps, and the stated timing isn’t a promise of a particular outcome. If you’re planning around a purchase or investment milestone, explain the timing that matters to your plan.
Can I use a rental property to access equity?
Accessing equity in an owned rental property may be a goal to discuss through Cash-Out Refinance or Home Equity Loans. These are distinct paths, so start with the purpose of the funds and the property’s current ownership and debt situation. For instance, explain whether the funds relate to another investment or a different financial objective. The property and your circumstances inform the conversation, not an assumed approval.
Does AHLHardMoney™ serve rental-property borrowers outside Tampa?
Yes. AHLHardMoney™ serves the entire state of Florida, not just Tampa. Its Florida reach includes communities such as Clearwater, Saint Petersburg, Palmetto, Largo, Newport Richey, Port Richey, Brooksville, Brandon, Orlando, Daytona, Napels, Ocala, Deltona, Deland, Jupiter, Palm Beach, Lakeland, and Boca Raton. Share the property’s location and intended use to set the right local context for the discussion.
Can AHL finance a rental property purchase?
AHL offers Purchase Loans and accepts both owner-occupied and non-owner-occupied properties. If you’re looking to acquire a rental, describe the property you’re considering and how you intend to use it. Clarify whether you’re still evaluating a potential purchase or already have a specific property in mind. That context helps focus the conversation on your acquisition goal without assuming a particular property or rental strategy will qualify.
What information should I prepare before discussing a rental property loan?
Prepare the property’s location, ownership status, intended rental use, and your financing objective. Note any existing property debt and what you understand about its equity, along with relevant information about your wider financial situation. Clear notes can help you explain the plan, identify unanswered questions, and keep the conversation centered on your needs.
Does AHL offer conventional or DSCR rental-property loans?
AHL’s listed programs include Hard Money Loans, Private Money Loans, Purchase Loans, Refinance Loans, Cash-Out Refinance, and Home Equity Loans. For a rental-property objective, start with the purpose of the financing and the property involved. That gives you a practical basis for discussing which of AHL’s programs relates to your plan.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


