
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
A lower monthly payment can still cost more over time. For borrowers considering a debt consolidation loan with bad credit in St. Petersburg, FL, approval and terms depend on the lender’s eligibility criteria and the borrower’s financial profile. Payment history makes up 35% of a credit score, so the way you manage payments after consolidating can matter.
It’s reasonable to want one manageable payment and a clearer path through multiple balances, especially when credit challenges narrow your choices. This guide explains how consolidation may affect your credit, what to compare when weighing loan costs against credit card interest, and which options may fit borrowers with bad credit. You’ll also learn what lenders commonly consider when reviewing eligibility, including income, debt payments, and whether a loan is secured by home equity.
Key Takeaways
- See how opening a consolidation loan and managing it over time can influence your credit profile.
- Learn what to weigh beyond the monthly payment, including repayment length and borrowing costs.
- Compare unsecured borrowing with home-equity options and understand the risk of using your home as security.
- Understand the factors lenders may consider when reviewing applications from borrowers with credit challenges.
- Explore when debt consolidation hard-money financing may be relevant to your situation.
How consolidation may affect credit scores
A consolidation loan replaces several credit card balances with a new account, while the old cards may remain open. Its effect on your credit profile depends on the lender’s application process and how you manage the accounts afterward. For St. Petersburg borrowers, consider both the new payment and the spending habits that follow.
Payment history makes up 35% of a credit score. That makes on-time payments on the new loan especially important after consolidation. A missed payment can harm the score, even if the loan initially helped simplify several due dates. Setting a reliable payment routine before the first bill arrives can reduce the chance of overlooking a due date. Keeping old credit card accounts current also matters if they still have balances.
Prequalification and a formal application can involve different types of credit checks. Prequalification may use a soft inquiry, which typically does not affect a credit score. A full application may involve a hard inquiry, which can affect the score. The inquiry type matters, so review the lender’s explanation before moving from an initial estimate to an application. Avoiding several formal applications in a short period can also help limit unnecessary credit checks.
A new loan and changes to paid-off card balances can affect your credit profile in different ways. Consider these common mechanisms:
- Credit card balances: Paying down revolving balances can reduce the portion of available card credit being used.
- New account: A new loan changes the mix of accounts and adds a recent application to the profile.
- Payment record: Consistent payments build a stronger record over time; missed payments can work against it.
For example, paying several cards with a loan may lead to lower card balances appearing in your credit record later. But using those cards again can leave you with both a loan payment and renewed card debt. Consolidation changes how balances are structured; it doesn’t erase the debt. The benefit depends partly on keeping card spending manageable.
Home equity adds a separate consideration. Using a home equity loan to consolidate debt may replace unsecured card balances with debt secured by the home. If the borrower cannot repay, the home may be at risk of foreclosure or sale to pay the debt. For a St. Petersburg homeowner, Florida property and foreclosure concerns can matter alongside the score when home equity secures debt. Compare the credit impact with the consequences of changing which assets secure repayment.
Convenience of one monthly payment
Replacing several card due dates with one loan payment can simplify monthly budgeting. Instead of tracking separate minimum payments and billing dates, you follow one repayment schedule. This works best when the new payment fits your budget and the old card balances are paid off. Consolidation organizes debt, but doesn’t reduce the amount owed by itself.
Imagine card payments due on different dates throughout the month. A consolidation loan can bring those balances into one account with one scheduled payment. You’ll still need to plan for other bills, but fewer debt due dates can make cash flow easier to track. A calendar reminder or automatic payment can help you stay on schedule, while a monthly review shows whether card balances are staying down.
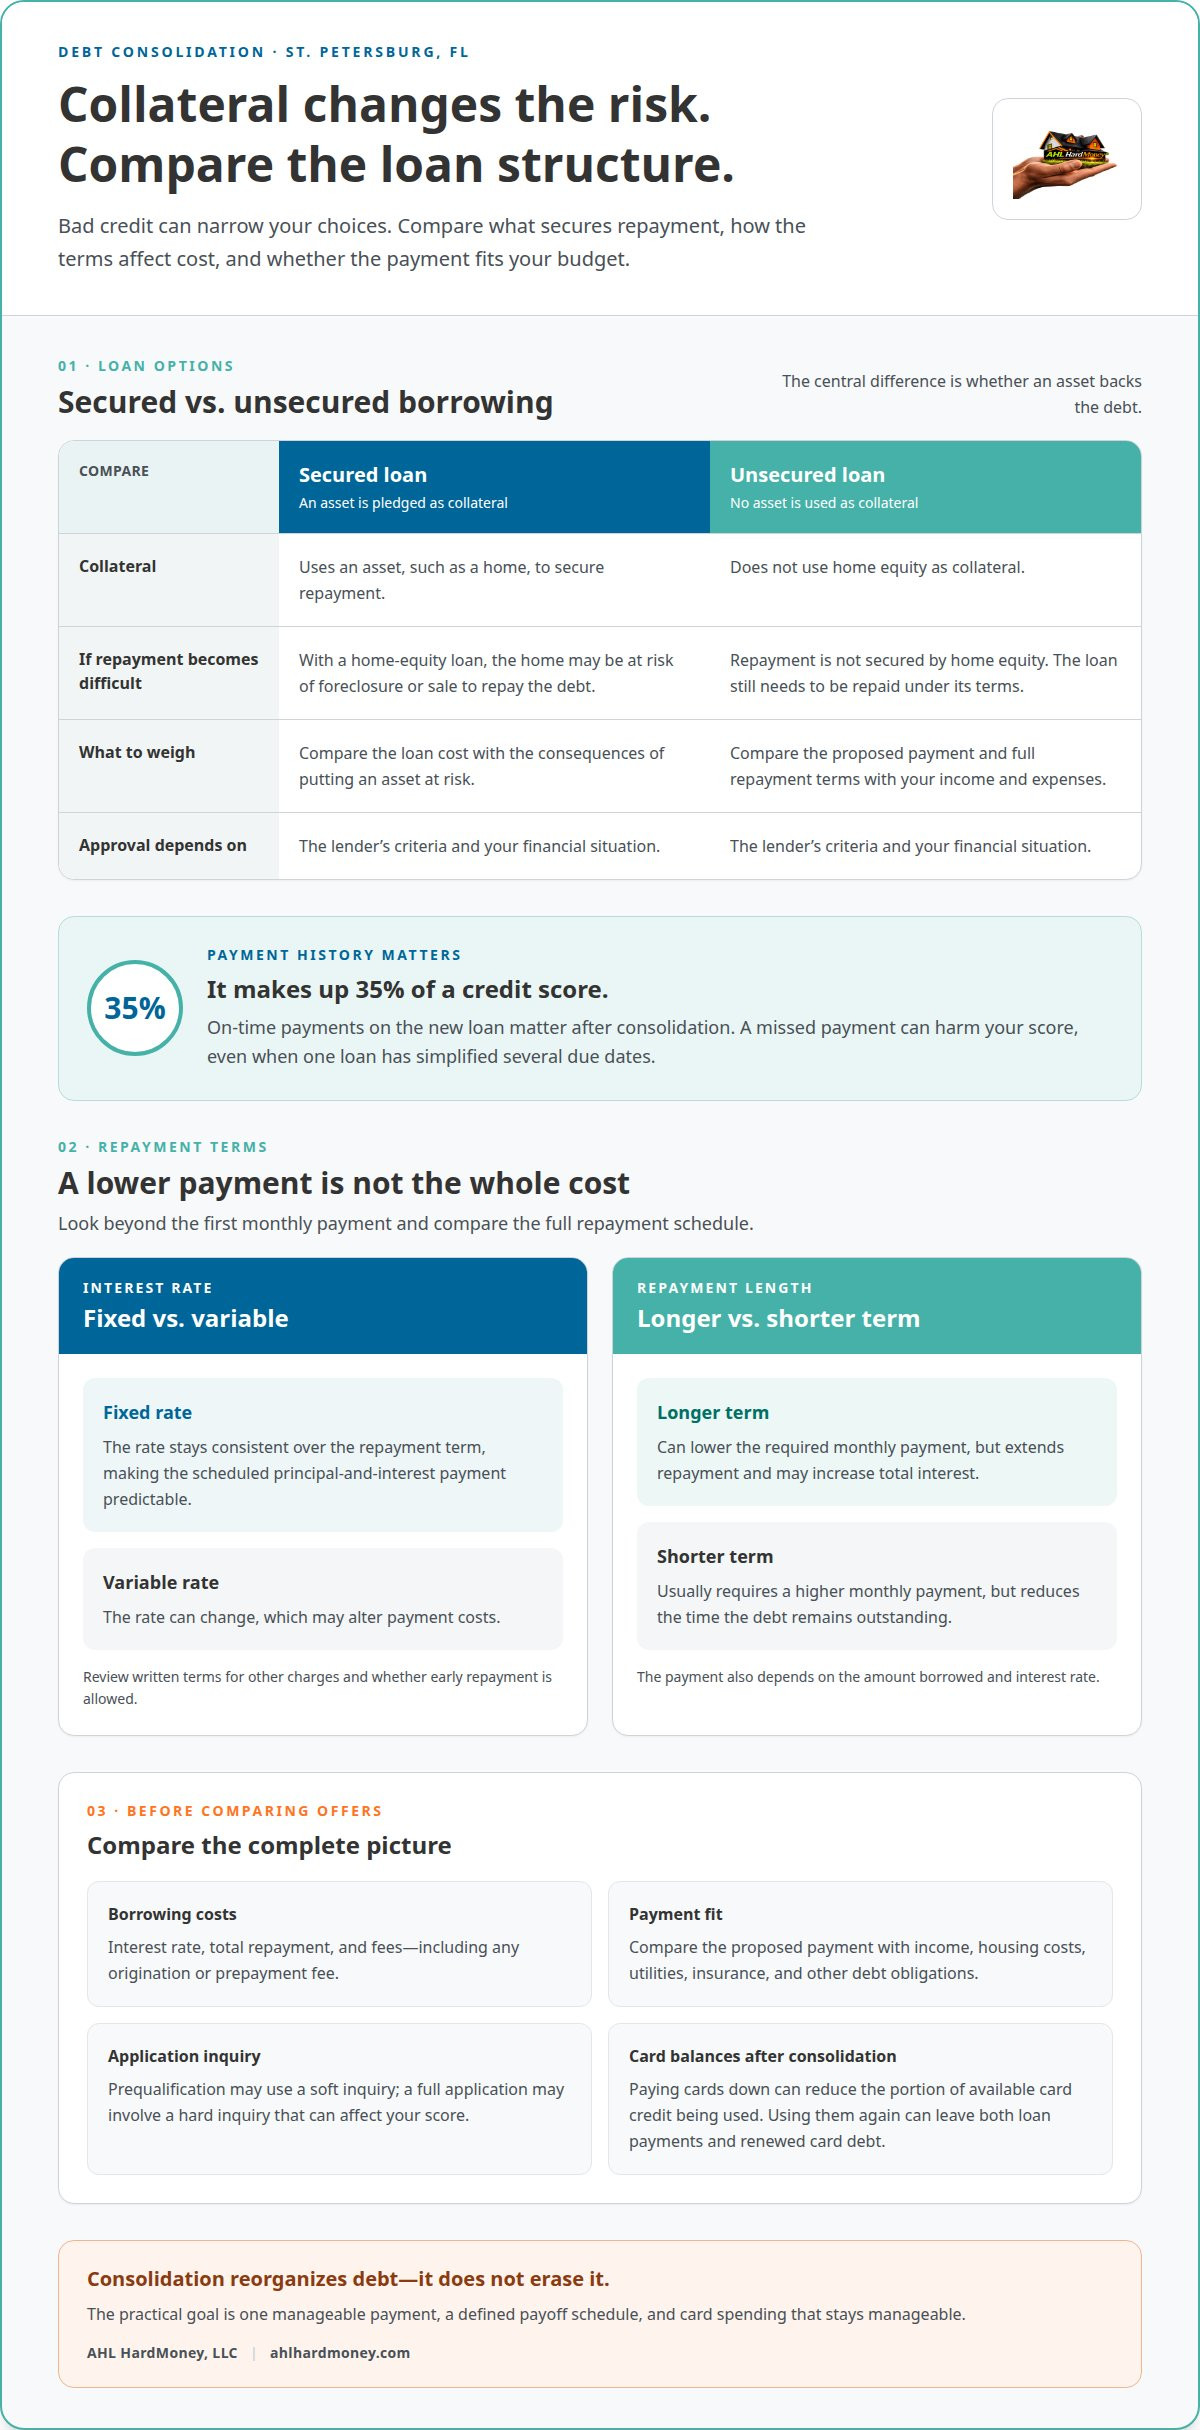
A monthly payment depends on the amount borrowed, interest rate, and repayment term. A longer term can lower the required payment but extend repayment and potentially increase total interest. A shorter term usually requires a higher monthly payment but reduces the time the debt remains outstanding. Compare the full repayment schedule, not just the first payment.
A fixed-rate loan keeps the interest rate consistent over the repayment term, making the scheduled principal-and-interest payment predictable. A variable rate can change, which may alter payment costs. Fixed payments don’t rule out other charges or determine whether early repayment is allowed. Review the written terms for those details.
Before signing, check whether the agreement includes a fee or restriction for paying extra or clearing the balance early. Also distinguish a prepayment fee from an origination fee, which is charged when a loan begins. These costs affect whether consolidation makes sense, even if the monthly payment looks manageable.
Plan payments around your actual income and essential expenses, not an ideal month. Compare the proposed payment with housing costs, utilities, insurance, and other debt obligations. If income changes, a payment that once seemed comfortable can become difficult to maintain. Leave room for routine expenses and reduce the risk of missed due dates.
For an unsecured personal loan, repayment doesn’t use home equity as collateral. A secured loan may connect repayment to an asset, so convenience must be weighed against that added consequence. A clear overview of the approach to loan guidance can help frame what to consider before moving forward. Keep the goal practical: one manageable payment, a defined payoff schedule, and no return to growing card balances.
Debt consolidation loan options for borrowers with bad credit
Bad credit can narrow available choices, but you can compare secured loans, unsecured loans, and options that don’t involve a new loan. The right fit depends on the repayment terms, any collateral at risk, and whether the payment fits your income.
Secured and Unsecured Loans
A secured loan uses an asset, such as a home, as collateral; an unsecured loan does not. A home equity loan can consolidate balances, but missed payments can put the home at risk of foreclosure or sale to repay the debt. Compare the interest rate, total repayment, fees, and due dates. The lender’s criteria and your financial situation also affect approval.
Alternative Consolidation Options
Banks, credit unions, and online lenders have different application processes and eligibility standards. A debt management plan is another option: a counselor may arrange structured repayment with participating creditors instead of issuing a new loan. Compare how each approach handles interest, fees, monthly payments, and access to credit cards. If an option includes skipped payments, check how that affects interest and repayment.
Lender and Local Credit Union Options
For borrowers with bad credit in St. Petersburg, banks, credit unions, and online lenders may offer consolidation loans, but their terms and approval standards vary. Compare income review, collateral requirements, and repayment terms rather than focusing only on whether you can apply online. AHLHardMoney serves the entire state of Florida, including St. Petersburg.
Risks of Loan Features
A co-signer can help support an application, but also takes on responsibility for repayment under the loan agreement. Missed payments can affect both borrower and co-signer, so both should understand the commitment. High-interest loans can make a smaller monthly payment misleading if repayment lasts longer. Same-day funding isn’t a standard feature across options; timing depends on application review and disbursement. Don’t treat speed as a reason to overlook the full terms.
Before choosing a home equity loan, make the risk to your home central to the decision. A borrower who doesn’t repay may risk foreclosure or being forced to sell the home to pay the debt. Consider whether the planned payment will remain manageable throughout repayment and whether another approach avoids putting the home at stake. Read the agreement closely, including what counts as nonpayment and what may follow, and ask the lender to explain unclear terms. Weigh those consequences against the purpose of consolidating balances.
Lender eligibility for borrowers with bad credit
Bad credit doesn’t automatically determine whether a debt consolidation application qualifies. Lenders weigh credit history alongside income, existing debt payments, and the requested loan structure. Most lenders require applicants to have at least a 620 FICO score, but a score alone doesn’t show whether the monthly payment fits a borrower’s finances.
Debt-to-income ratio can also shape an eligibility decision. Lenders commonly set a debt-payment threshold at 43% of income, while borrowers are advised not to let monthly debt payments exceed 50% of income. These figures describe different considerations: one is a threshold lenders commonly use, and the other is a personal budgeting guideline. For example, a borrower with steady income but high monthly obligations may face a different review than someone with fewer debts.
When comparing a debt consolidation loan for bad credit in St. Petersburg, FL, distinguish a lender’s eligibility rules from the terms of a particular loan. Requirements depend on the product and lender, especially when comparing secured borrowing with unsecured credit. Before signing, review the agreement and disclosures for the interest rate, payment schedule, collateral terms, and consequences of missed payments.
An online application typically gathers information for an eligibility review. Depending on the lender and loan, you may be asked about income, employment, recurring debt payments, credit history, and, for secured financing, available equity. Provide accurate details so the lender can assess the requested amount and repayment schedule. Identify the balances you want to consolidate so the amount reflects your payoff needs.
For a practical review, organize your decision around these factors:
- Credit profile: Check whether the lender’s minimum score criteria fit your current record.
- Income and obligations: Compare monthly debt payments with income, including housing and other recurring bills.
- Collateral: If equity secures the loan, weigh the risk to the property against repayment terms.
- Loan terms: Compare the interest rate, payment schedule, and total repayment obligation.
Credit union membership may matter because some products are available only to members. Banks and online lenders can have different eligibility standards and application processes. Compare the actual criteria and terms rather than assuming one lender type is more flexible for every borrower seeking a debt consolidation loan for bad credit in St. Petersburg, FL.
If a lender declines your application, find out which factor affected the decision before applying again. A high debt-payment burden, limited income, credit history, or insufficient equity may affect eligibility. Addressing the relevant issue can help align a future application with your financial position.
Comparing consolidation costs with credit card interest
A lower monthly payment doesn’t automatically mean lower borrowing costs. Compare the interest rate, repayment term, fees, and total amount repaid. If you’re weighing consolidation against credit card interest, consider whether the new structure reduces overall cost while keeping payments manageable.
Consider three example balances: a store card with $3,000 at 20.63% APR, Credit Card #1 with $1,865 at 17.99% APR, and Credit Card #2 with $2,000 at 15.95% APR. The different APRs show why a single loan rate can’t be compared with one card alone. Review each balance and its rate before assessing a consolidation offer.
Compare how long repayment will last. A lower rate can still mean more interest overall if the repayment period is extended. A shorter term may cost more each month but reduce the time interest accrues. Compare scheduled payments and total repayment under each option, rather than judging by the first payment alone.
Fees can affect how much of the loan is available to pay existing balances. If an origination fee is charged, the proceeds may be less than the amount borrowed. That matters if the proceeds won’t cover every card balance. Include fees in your cost comparison and account for any remaining balances that will continue accruing interest.
A 0% APR balance transfer card may offer an introductory no-interest period lasting up to 21 months. That period can create room to repay transferred balances without interest, but the benefit depends on paying down the debt before the introductory period ends. Compare any transfer costs and the rate that applies afterward with the proposed consolidation terms.
Credit card balances may not be the only debts you’re managing. Medical bills and other interest-bearing debt can also affect the amount needed and the repayment plan. List each balance, its interest rate, and its due date. Then compare their combined cost with the proposed loan’s terms, including fees and repayment length.
For a clear comparison, use the same payoff goal for each option. Add the remaining interest and fees over the full repayment period, then compare total costs and monthly obligations. A consolidation loan makes sense only if its terms suit your budget and debt payoff plan.
LendingTree reports an average debt consolidation loan APR of 27.16% for fair credit scores from 580 to 669. Lower rates could save hundreds to thousands in total interest.
AHL HardMoney: Debt Consolidation Hard Money Loans
AHL HardMoney, llc offers Debt Consolidation Hard Money Loans for borrowers considering consolidation in St. Petersburg. Its hard-money financing may suit borrowers whose credit history makes conventional borrowing difficult and who are considering property-based financing. AHL HardMoney, llc also offers Cash-Out Refinance, Home Equity Loans, and Refinance Loans for different borrowing needs.
Approval often takes within 30 minutes, and loans can close in 5 to 15 days, regardless of credit history. Those timelines don’t replace careful review: compare the proposed repayment terms with existing debts and consider the obligations involved before moving forward. A home-secured approach also calls for weighing the property-related risks against the goal of consolidating balances.
For details about the debt consolidation loan bad credit St Petersburg FL option, review how it may fit your circumstances.
Contact AHL HardMoney, llc to discuss your debt consolidation needs.
Choose a Next Step That Fits Your Financial Goals
Make your next move with a clear purpose: decide what you need the financing to accomplish and what repayment commitment fits your plans. A workable choice should support your broader financial priorities, not simply rearrange balances. If you’re considering a debt consolidation loan for bad credit in St. Petersburg, FL, focus on a plan you can realistically manage.
AHLHardMoney, LLC offers Debt Consolidation Hard Money Loans, along with Cash-Out Refinance, Home Equity Loans, and Refinance Loans. These programs serve different borrowing needs. Consider which financing structure suits your circumstances and whether using property as collateral is appropriate for you.
Before proceeding, decide what you want to clarify: which debts you hope to address, what payment structure you’re seeking, or whether a property-based option merits consideration. A focused conversation with AHLHardMoney can help you understand the next steps without pressure to choose before you’re ready.
Take the process one thoughtful step at a time. A clear plan can help you move forward with confidence.
Frequently Asked Questions
What credit score and income requirements do local lenders use for bad-credit consolidation loans?
Requirements vary by lender, and credit score is only one part of an application. AHLHardMoney states “No Hard Credit Inquiry” and accepts any credit profile for its Florida loan programs. It serves the entire state of Florida, with focus areas in Hillsborough, Pasco, Pinellas, Polk, Manatee, Citrus, and Hernando Counties. Compare how other lenders assess income, current obligations, and repayment capacity alongside credit history. A credit union may also require membership for certain products.
What APRs, fees, and loan amounts are available for bad-credit debt consolidation in St. Petersburg?
APR, fees, and available amounts depend on the lender, loan structure, borrower profile, and collateral. Don’t assume advertised unsecured-loan terms apply to property-secured financing. Compare each written offer’s APR, payment schedule, total repayment, and any origination or application charges. For AHL HardMoney, cost depends on the case and is provided after a quote request; factors include the loan structure and property equity. Avoid comparing offers by payment alone.
How can a lender calculate whether a debt consolidation loan will lower your total cost and monthly payment?
For a practical comparison, gather each card’s current balance, APR, minimum payment, and expected payoff period. Then compare those costs with the new loan’s full repayment schedule, including fees. A lower monthly payment may result from extending repayment, so check whether total interest and fees also decrease. Include any balances the loan won’t pay off.
What information should St. Petersburg residents provide when applying for a debt consolidation loan with bad credit?
Prepare details about income, existing debts, and the property if the loan will use real estate as collateral. AHL HardMoney’s listed application documents include property documents, income verification, tax returns, and K-1s, where applicable. A clear list of balances and creditor payoff information can also help explain the amount sought and intended use. Provide accurate, consistent details so the lender can assess the request against the proposed repayment structure.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


