
Article by
Dan Conneally - NMLS 339916, LO13164, BK3246524, CQ1072086
Dan Conneally has been successfully helping Florida families with thier real estate related situations for the last 21+ years, regardless of credit or past financial background.
While Dan is effective with institutional lending, he particuarly shines when matters require unique strategies involving noninstitutional resources.
Check out his legions of testimonials from real Florida families at Google, Facebook and the BBB to get a sense of the caliber and effectiveness he achieves. Dan has appeared on television speading the message of hope to good folks that need diligent, discrete, nonjudgy care.
A bruised credit score doesn’t always get the final say when your home has substantial equity. If you’re searching for a fast home equity loan Clearwater FL, asset-based financing may offer another path when bank approvals feel slow or credit requirements stand in the way.
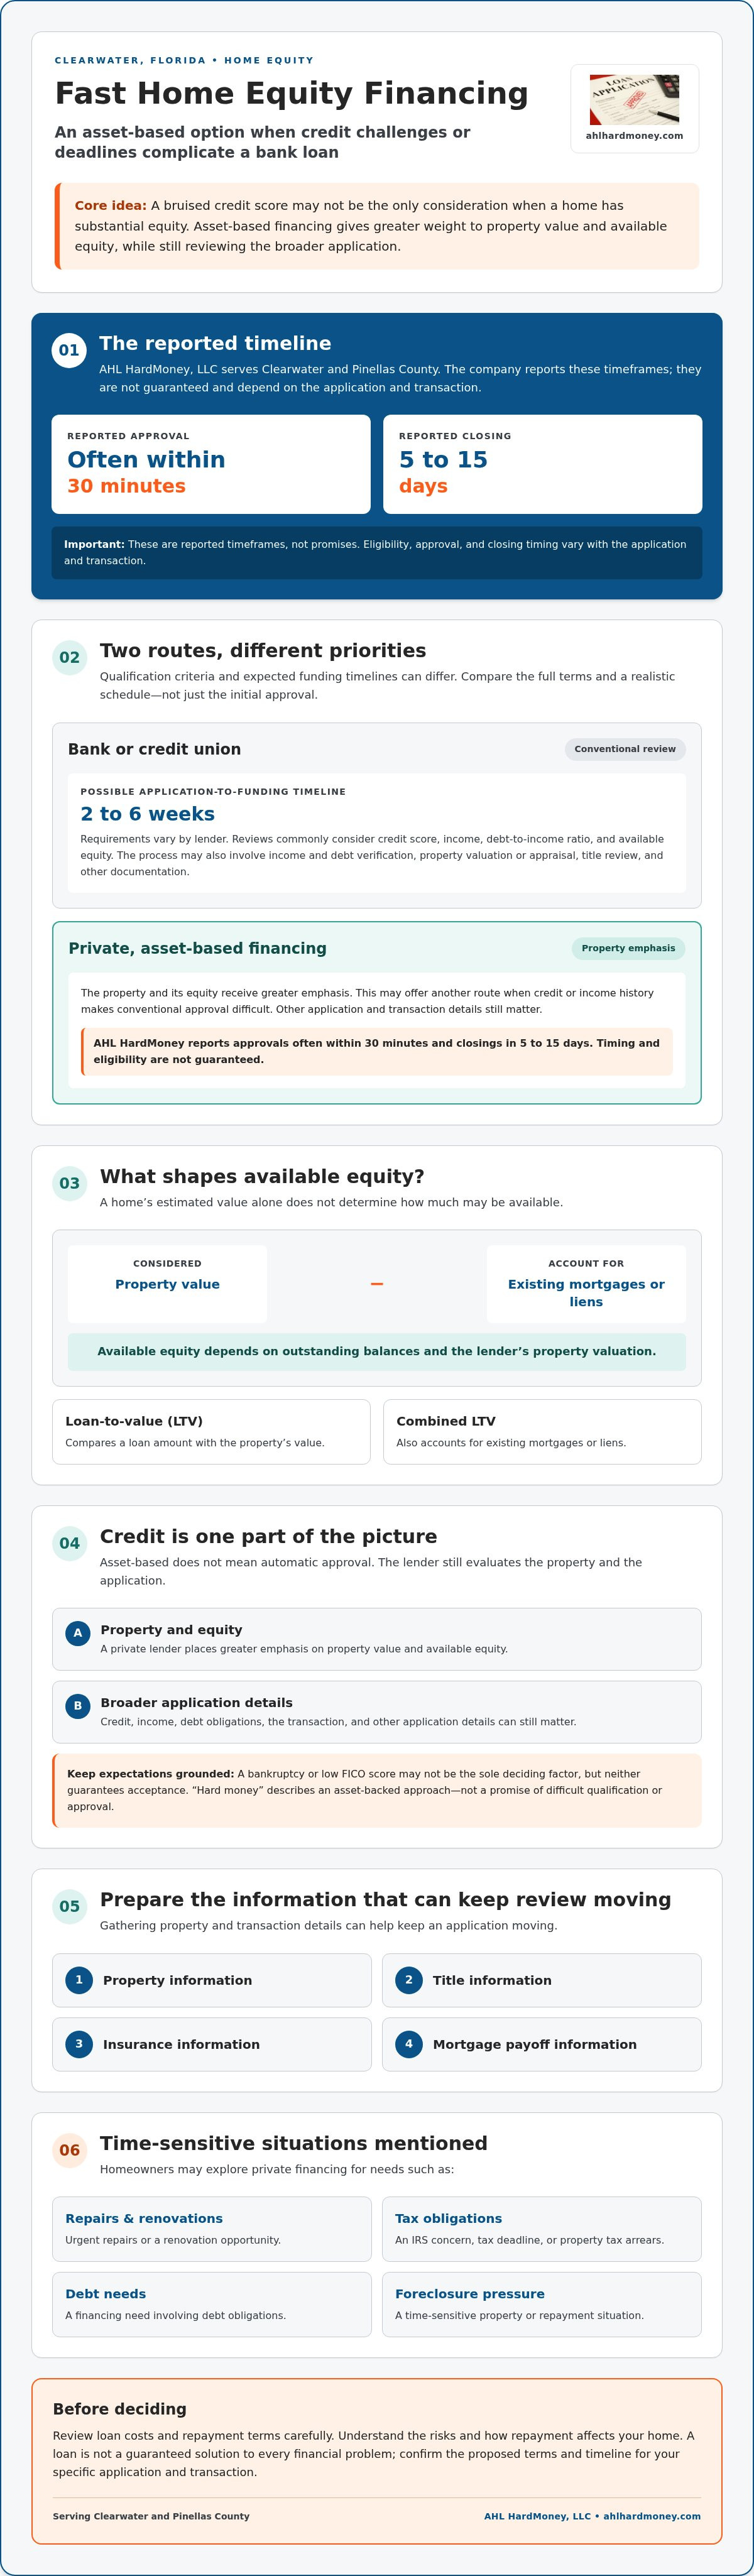
That urgency can be real. A tax deadline, foreclosure pressure, or major expense may not wait while a traditional lender reviews paperwork. AHL HardMoney, llc considers property equity alongside the broader application, including challenging credit or tax circumstances. The company serves Clearwater and Pinellas County and reports approvals often within 30 minutes and closings in 5 to 15 days. These are not guaranteed timeframes. Eligibility and timing depend on the application and transaction.
This guide explains how a fast home equity loan works, what a lender may consider beyond your FICO score, and how to prepare for a faster review. It also covers trade-offs and options for time-sensitive needs, so you can assess whether borrowing against your home fits your situation.
Key Takeaways
- A fast home equity loan Clearwater FL may offer an asset-based alternative when credit challenges make traditional approval difficult.
- Private lending and bank home equity loans can differ in qualification criteria and funding timelines.
- Your home’s value and existing mortgage balances help determine how much equity may be available.
- Gather property, title, insurance, and payoff information to help keep an application moving.
- AHL HardMoney serves Clearwater and Pinellas County and reports approvals often within 30 minutes and closings in 5 to 15 days.
What is a Fast Home Equity Loan in Clearwater, FL?
A fast home equity loan Clearwater FL homeowners may consider is an asset-based loan secured by their property. Rather than relying mainly on credit history and income, a private lender gives substantial weight to the home’s value and available equity. The term home equity loan can describe different borrowing structures. Here, the focus is financing backed by real estate, with terms and qualification based on the property and application.
This distinction can matter when a deadline is approaching or a past credit issue makes a conventional application harder. Clearwater homeowners may explore private financing for repairs, renovations, debt needs, tax obligations, or foreclosure pressure. A loan is not a guaranteed solution to every financial problem, so review the proposed terms and timeline carefully.
For a quick visual overview of borrowing with credit challenges, watch this video:
Equity-Based Lending vs. Traditional Mortgages
Traditional banks generally assess credit, income, debt obligations, and property value together. Private asset-based lending places greater emphasis on property value and equity, though other application details still matter. Loan-to-value (LTV) compares a loan amount with the property’s value. Combined LTV also accounts for existing mortgages or liens. The home’s estimated value alone does not show usable equity: outstanding balances and the lender’s valuation affect the calculation.
“Hard money” describes an asset-backed approach, not a promise that qualification is difficult. It can offer another route for borrowers whose credit history does not tell the whole story. Loan costs, repayment terms, and risks still deserve close review.
Why Clearwater Residents Need Speed
Deadlines don’t always wait for a lengthy review. A renovation opportunity, urgent repair, IRS concern, or property tax arrears may call for a timely plan. Conventional applications can take weeks, so an estimated 45-day process may not suit a pressing need. AHL HardMoney, LLC reports approvals often within 30 minutes and closings in 5 to 15 days. Actual timing depends on the application and transaction.
For homeowners facing foreclosure pressure, explore whether a Florida foreclosure refinance loan may fit the situation. Compare the full terms, confirm the timeline, and understand how repayment affects your home before moving forward.
Hard Money vs. Bank Home Equity Loans: A Comparison
Choosing between a bank loan and private, asset-based financing often comes down to priorities: potentially more favorable terms for borrowers who meet conventional criteria, or a faster review that places greater weight on property equity. If you need a fast home equity loan Clearwater FL, compare qualification requirements and realistic funding timelines, not just the initial approval.
- Bank and credit union loans: Lenders commonly review credit score, income, debt-to-income ratio, and available equity. A home equity loan process may take 2 to 6 weeks from application to funding, and requirements vary by lender.
- Hard money loans: The property and its equity receive greater emphasis, which may help when credit or income history is complicated. AHL HardMoney, LLC reports approvals often within 30 minutes and closings in 5 to 15 days, subject to the application and transaction.
The Reality of Bank Timelines in 2026
A bank’s review can involve more than a credit check. Depending on the lender and property, the process may include income and debt verification, a property valuation or appraisal, title review, and other documentation. If an issue surfaces late, an application can be delayed or declined after weeks of waiting. A 45-day timeline is not universal, but it illustrates why borrowers with firm deadlines should confirm the expected schedule early.
The Hard Money Advantage for Clearwater Borrowers
Asset-based financing may move faster when the lender centers its evaluation on the property, equity, and transaction details rather than treating credit score and debt-to-income ratio as the main hurdles. The lender still needs to assess the property and application, so “asset-based” does not mean automatic approval. A bankruptcy or low FICO score may not be the sole deciding factor, but neither guarantees acceptance.
Preparation helps whichever route you choose. Be ready to provide property details, existing loan payoff information, and requested financial or ownership documents. Ask what valuation, title work, insurance details, and closing steps apply. Get a clear estimate of the full timeline before committing.
If replacing an existing mortgage while accessing equity better fits your needs, review the details of a cash out refinance. Compare repayment terms and costs carefully. A private loan’s speed can be useful, but it should also fit your longer-term financial plan.
Qualifying for a Fast Home Equity Loan with Bad Credit
A low FICO score, past bankruptcy, or uneven income does not tell the whole story. In asset-based lending, available property equity can carry more weight than it typically does in a conventional application. That’s the “equity is king” idea, not a promise of approval. Lenders still review the property, existing debts, title, and repayment plan.
Leveraging Your Property Value
Start with a practical estimate: subtract mortgage and other lien balances from the property’s estimated value. Then ask how the lender calculates its maximum loan-to-value (LTV), which compares the loan amount with the property value. The lender’s valuation and LTV limit determine how much equity may be usable, not your estimate alone.
A property with no mortgage may simplify the payoff picture, although title issues or other liens can still affect the process. Learn more about free and clear Florida property. If debt consolidation is part of your plan, consider whether a debt consolidation hard money loan fits your circumstances. Borrowing against your home adds risk, so compare the new payment and repayment plan with your current obligations.
Income Documents and Complex Situations
“No income proof” should not be taken to mean “no review.” Documentation requirements vary by lender and loan structure. A lender may request bank statements or other information to understand your ability to make payments, even when property equity is central to qualification. Ask what records are required before applying, especially if you’re self-employed, retired, or have complex tax filings.
Foreclosure pressure or a tax lien can complicate an application, but neither alone determines whether a loan is possible. Share relevant notices and payoff information early, and ask how liens affect available equity and closing. Clearwater borrowers exploring options for foreclosure pressure can review a Florida foreclosure refinance loan. Do not assume borrowing will resolve every situation.
Plan the Exit Before You Borrow
Before pursuing a fast home equity loan Clearwater FL, map out how and when you’ll repay or refinance it. Identify the expected source of repayment, the steps needed to reach it, and a backup plan if timing changes. A clear exit strategy matters because your home secures the loan, and missed payments can put it at risk. Review all terms and make sure the plan is realistic for your finances.
5 Steps to Secure Your Clearwater Home Equity Loan Fast
A fast home equity loan Clearwater FL application may move more smoothly when you know what comes next and provide requested information promptly. AHL HardMoney, LLC reports approvals often within 30 minutes and closings in 5 to 15 days. Timing depends on the property, title, documentation, and transaction details. Use these steps to prepare from inquiry to funding.
1. Make an Initial Inquiry
Share the property address, your estimate of its value, any mortgage or lien balances, and the amount you’re seeking. Be upfront about your timeline and reason for borrowing. This gives the lender a starting point to assess the property and explain what information it needs. An approval can often come within 30 minutes, but that is not a guarantee of final approval or closing.
2. Gather Property and Payoff Information
Prepare the documents the lender requests. These may include ownership or title information, proof of property insurance, current mortgage statements, and payoff details for existing loans or liens. Requirements vary, so request a file-specific checklist instead of assuming a short list covers every application. You can also review this guide to hard money lenders in Florida for additional background.
3. Complete the Property Valuation
The lender needs to establish the property’s value to assess available equity and LTV. Valuation methods and timing vary by lender and property. Asset-based lending does not mean an appraisal or other property review is automatically skipped. Ask what valuation is required, who coordinates it, and whether the lender needs access to the home or additional property details. Prompt responses can help prevent avoidable delays.
4. Clear Underwriting and Closing Conditions
After reviewing the property, title, and requested documents, the lender will identify any remaining conditions before closing. Respond quickly to questions and confirm payoff figures, ownership details, and insurance information are accurate. Before signing, read the loan documents carefully. Check all fees, payment terms, any interest-only provisions if offered, and the consequences of missed payments.
5. Sign and Confirm Funding
At closing, review and sign the final documents, then confirm how and when funds will be disbursed. Don’t assume a wire will arrive immediately after signing. Ask about the funding process, account verification, and any remaining steps. AHL HardMoney, LLC reports closing in 5 to 15 days when a transaction is ready to proceed.
Why Choose AHL HardMoney for Your Clearwater Equity Needs?
A fast home equity loan Clearwater FL borrowers consider should involve more than a quick headline. You need to understand how the lender reviews your property, what steps remain, and what repayment involves. AHL HardMoney, LLC is a direct lender serving Clearwater and Pinellas County from its Tampa headquarters. You work with the lender handling the financing rather than relying on a broker to pass your application between companies.
AHL HardMoney reports approvals often within 30 minutes and closings in 5 to 15 days. These are reported timeframes, not guarantees. The property, title, documentation, and transaction all affect how quickly a loan can close. Ask who will handle your file, what decisions are pending, and what could delay funding. Direct communication can help you understand the process and respond to requests for information.
A Local Perspective for Clearwater Homeowners
Clearwater and the wider Pinellas County area include many different property and borrower circumstances. A Tampa-based lender serving this market may be familiar with the region, but a home’s value cannot be determined from location alone. Property condition, valuation, existing liens, and title details still matter. AHL HardMoney’s asset-based approach emphasizes equity, which may be relevant for homeowners whose credit or income history does not fit a conventional profile.
AHL HardMoney lists markets including Clearwater, Saint Petersburg, Tampa, Palmetto, Largo, Newport Richey, Port Richey, Brooksville, Brandon, Orlando, Daytona, Naples, Ocala, Deltona, DeLand, Jupiter, Palm Beach, Lakeland, and Boca Raton. Whether you’re in Clearwater or another listed market, make sure the proposed loan fits your repayment plan. For a look at a nearby market, see this guide to hard money lenders in Pasco County.
Loan Options and a Clear Next Step
Different property and borrower situations may call for different financing paths. AHL HardMoney offers home equity loans and HardMoney Lite™. Ask whether either option fits your needs and what its terms require. You can review the HardMoney Lite™ program, then compare repayment terms, costs, and risks before moving forward.
To start a review, share the property address, your estimate of its value, current mortgage or lien balances, and your timeline. AHL HardMoney reports that approvals often come within 30 minutes, but an initial review is not a final commitment. Confirm the documents needed and the steps between approval and closing.
Apply for a Clearwater home equity loan.
Take the Next Step With a Clear Plan
A fast home equity loan Clearwater FL homeowners consider can offer an alternative when conventional credit or income requirements are a poor fit. The key is understanding how property equity, existing liens, and the lender’s review affect qualification and timing. Before moving forward, make sure the repayment plan and loan terms suit your situation.
AHL HardMoney, LLC is a Florida hard money lender serving Clearwater and Pinellas County. The company reports approvals often within 30 minutes and closings in 5 to 15 days, depending on the application and transaction. An initial approval is not a guarantee, so ask what conditions remain and what could affect the closing schedule.
Review the details, compare your options, and take the process one step at a time. With accurate information and a realistic plan, you can make a considered decision about your home’s equity.
Frequently Asked Questions
How fast can I actually get a home equity loan in Clearwater?
A fast home equity loan Clearwater FL application may receive an initial approval quickly, but approval and funded closing are different milestones. The actual timeline depends on property review, title, requested documents, and closing steps. Ask which conditions remain and confirm the expected funding date before relying on the proceeds for a deadline.
Can I get a home equity loan in Florida with a 500 credit score?
It may be possible, but a 500 credit score neither guarantees approval nor rules it out by itself. AHL HardMoney prioritizes property equity over credit history while still reviewing the property and the full application. Available equity, existing liens, title, and repayment plans may all matter. Ask how the lender evaluates your circumstances, and be prepared to provide accurate property and payoff information.
What is the maximum LTV for a Clearwater hard money equity loan?
There isn’t one maximum loan-to-value (LTV) figure that applies to every Clearwater hard money equity loan, and AHL HardMoney’s maximum isn’t specified here. LTV compares the loan amount with the property’s value. Combined LTV also accounts for existing mortgages or liens. Ask what limit applies to your property and whether the valuation method, existing balances, or title findings affect the amount available.
Do I need an appraisal for a fast home equity loan?
You may need a property valuation, but whether that means a formal appraisal depends on the lender, property, and transaction. Asset-based lending still requires the lender to assess the home and available equity. A faster process does not necessarily eliminate valuation or title review. Ask what valuation method will be used, whether an appraisal is required, who arranges it, and whether you need to provide access or additional property details.
Can I use a home equity loan to stop a foreclosure in Pinellas County?
Equity-based financing may be one option to explore, but a loan is not guaranteed to stop foreclosure or resolve every lien or deadline. AHL HardMoney offers foreclosure refinance loans, and eligibility depends on the property, available equity, title, timing, and application review. If you’re facing foreclosure in Pinellas County, gather your notices and payoff information, then promptly discuss your options with your lender and a qualified housing or legal professional.
What documents are required for a hard money equity loan in Florida?
Requirements vary by lender and property, so request a file-specific checklist early. Be ready to share the property address, ownership or title details, insurance information, and current mortgage or lien payoff figures. The lender may also ask for identity, financial, or other application documents. Sending complete, accurate information promptly can help the review move forward, but the lender will confirm exactly what’s needed for your circumstances.
Are there prepayment penalties on Clearwater hard money loans?
Don’t assume a hard money loan has a prepayment penalty, or that it doesn’t. The answer depends on the written terms of the specific loan, and no standard prepayment policy is confirmed here for Clearwater loans. Before signing, ask whether paying early triggers a penalty, minimum interest, or other conditions, and request an explanation of how any charge is calculated. Make sure your repayment or refinance plan accounts for those terms.
Can I get a home equity loan if I am self-employed with no tax returns?
Possibly, but ask the lender what documentation it accepts for your application. Asset-based lending gives substantial weight to property equity, yet that doesn’t mean income or repayment capacity will never be reviewed. A lender may request other financial records, such as bank statements, depending on the file. Explain your self-employment and tax-document situation early, and confirm what alternatives are acceptable before relying on approval.
Disclaimer:
While Dan is not a real estate attorney, he is a Full Time, Licensed Florida Mortgage and Real Estate Broker Professional coupled with 21+ years of successful strategies, methodologies and techniques that have proven effective to the benefit of Florida families.
While not every conversation is a deal, we promise to leave you better off then before you called. We serve everyone we come in contact, with the highest levels of integrity and dignity.
We invite you to make the call 📲


